Ind AS 7 – Statement of Cash Flows: Direct vs Indirect Method & Complete Guide
Page content
Reviewed by CA Nikhil Gupta · Last reviewed 4 June 2025
📋 Table of Contents
| Structural block | What it covers |
|---|---|
| Objective and scope | Requires information about historical changes in cash and cash equivalents through a statement classifying flows into operating, investing and financing activities. Applies to every entity presenting Ind AS financial statements. |
| Operating activities | Cash effects of the entity’s principal revenue-producing activities — can be shown by the direct method (major classes of gross receipts/payments) or the indirect method (adjusting profit for non-cash items and working-capital movements). |
| Investing activities | Cash flows from acquisition and disposal of long-term assets and other investments not classified as cash equivalents — capex, investment purchases/sales, loans given. |
| Financing activities | Cash flows that change the size and composition of the entity’s equity capital and borrowings — share issues/buybacks, dividend payments, debt drawdown/repayment. |
| Special items | Specific guidance for interest and dividends (consistently classified period to period), taxes on income (usually operating unless specifically identifiable with financing/investing), foreign currency cash flows, and non-cash transactions (excluded from the statement but disclosed separately). |
| Disclosure | Components of cash and cash equivalents and a reconciliation to the balance sheet; restricted cash balances not available for use by the group must be disclosed. |
1. Overview & Why Cash Flows Matter
The P&L account shows profit — but profit does not equal cash. A company can report strong profits while running out of cash (due to high debtors, inventory build-up, or capital expenditure), or report losses while generating strong operating cash flows (e.g., depreciation-heavy businesses like telecom or infrastructure).
Ind AS 7 mandates a Statement of Cash Flows as part of the complete financial statements. It helps users:
- Assess the entity's ability to generate cash and cash equivalents
- Evaluate the entity's liquidity and solvency
- Compare operating performance across companies without accounting policy distortions
- Understand how the company finances its investments
Warren Buffett famously prefers "owner earnings" (operating cash flows minus maintenance capex) over reported earnings — Ind AS 7 gives investors the data to compute this.
1.1 Cash and Cash Equivalents
The statement reconciles the opening and closing balance of cash and cash equivalents, which include:
- Cash on hand
- Demand deposits with banks
- Short-term, highly liquid investments with original maturities of 3 months or less (e.g., liquid mutual funds, 91-day T-bills)
- Bank overdrafts (deducted from cash and cash equivalents if repayable on demand and form an integral part of cash management)
2. Three Types of Activities
| Activity | Definition | Examples |
|---|---|---|
| Operating | Principal revenue-generating activities | Cash from customers, payments to suppliers, salaries, taxes paid |
| Investing | Acquisition/disposal of long-term assets and investments | Capex (PPE purchase), proceeds from asset sale, purchase/sale of investments |
| Financing | Changes in equity and borrowings | Share issue proceeds, loan repayments, dividends paid, interest paid on borrowings |
Every cash movement must be classified into one of these three buckets. The sum of the three gives the net change in cash during the period.
3. Indirect Method (Operating Activities)
The indirect method starts with net profit (or loss) before tax and adjusts for non-cash items and working capital changes to arrive at cash generated from operations. It is the method used by the vast majority of Indian companies.
Adjustments for non-cash/non-operating items:
Add: Depreciation & Amortisation ₹XX
Add: Finance Costs (interest expense) ₹XX
Less: Interest Income (₹XX)
Less: Dividend Income (₹XX)
Add: Loss on sale of assets ₹XX
Less: Gain on sale of assets (₹XX)
Add: Impairment losses ₹XX
Add: Provision for doubtful debts ₹XX
Operating Profit Before Working Capital Changes ₹XXX
Working Capital Changes:
(Increase)/Decrease in Trade Receivables (₹XX)
(Increase)/Decrease in Inventories (₹XX)
Increase/(Decrease) in Trade Payables ₹XX
Increase/(Decrease) in Other Liabilities ₹XX
Cash Generated from Operations ₹XXX
Less: Income Taxes Paid (₹XX)
The logic: Depreciation reduces profit but is not a cash outflow (added back). Interest expense reduces profit but is classified under financing (added back here, then shown under financing outflows). An increase in debtors means profit was recognized but cash not yet received — so deducted from operating cash flows.
4. Direct Method (Operating Activities)
The direct method shows actual cash receipts from customers and actual cash payments to suppliers, employees, and others. Ind AS 7 encourages the direct method as it provides more useful information, but most companies use indirect because it is easier to prepare from accounting records.
Cash paid to suppliers (₹XX)
Cash paid to employees (₹XX)
Cash paid for other operating expenses (₹XX)
Income taxes paid (₹XX)
5. Investing Activities
Investing activities are cash flows from acquisition and disposal of long-term assets and investments (other than those held as trading securities or cash equivalents).
Proceeds from sale of PPE ₹XX
Purchase of intangible assets (₹XX)
Purchase of investments (shares, bonds) (₹XX)
Proceeds from sale of investments ₹XX
Loans given to subsidiaries/associates (₹XX)
Loan repayments received ₹XX
Interest received (if classified here) ₹XX
Dividends received (if classified here) ₹XX
For most manufacturing and infrastructure companies, investing cash flows are significantly negative (net outflow) because capital expenditure exceeds asset disposal proceeds — this is healthy and expected for growing businesses.
6. Financing Activities
Financing activities are cash flows resulting in changes to equity and borrowings of the entity.
Payment for buyback of shares (₹XX)
Proceeds from long-term borrowings ₹XX
Repayment of long-term borrowings (₹XX)
Payment of lease liabilities (principal) (₹XX)
Dividends paid to shareholders (₹XX)
Interest paid (if classified here) (₹XX)
7. Special Items: Interest, Tax, Dividends
Ind AS 7 paragraphs 31–34 prescribe the interest/dividend classifications; the IAS 7 choice was removed. Separate the financial-institution case from other entities:
| Cash flow | Financial institutions | Other entities |
|---|---|---|
| Interest paid | Operating | Financing |
| Interest received | Operating | Investing |
| Dividends received | Operating | Investing |
| Dividends paid | Financing | Financing |
For a financial institution, interest paid and interest/dividends received are operating cash flows. Dividends paid are financing cash flows. For other entities, interest paid is financing and interest/dividends received are investing. Consistency supports the prescribed classification; it does not permit a prohibited alternative.
8. Free Cash Flow & Key Ratios
Investors derive several key metrics from the cash flow statement:
| Metric | Formula | Interpretation |
|---|---|---|
| Free Cash Flow (FCF) | Operating CF – Capex | Cash available after maintaining/growing asset base |
| Operating CF Margin | Operating CF ÷ Revenue | Cash generation efficiency; should trend with EBITDA margin |
| Cash Conversion | Operating CF ÷ Net Profit | >1x means quality earnings; <1x may signal aggressive accruals |
| Capex Intensity | Capex ÷ Revenue | Higher for capital-intensive sectors (telecom, metals) |
| FCF Yield | FCF ÷ Market Cap | Cash return on investment; comparable to earnings yield |
9. Case Studies: Indian Companies
TCS: consolidated cash-flow bridge, FY2024–25
| Operating bridge / movement | ₹ crore |
|---|---|
| Profit for the year (including NCI) | 48,797 |
| Depreciation/amortisation | 5,242 |
| Operating profit before working capital | 67,853 |
| Net working-capital change | (3,359) |
| Operating cash before tax | 64,494 |
| Tax paid, net | (15,586) |
| Operating cash flow | 48,908 |
| Net investing flow | (2,318) |
| Net financing flow | (47,438) |
| Net cash movement before exchange | (848) |
Cash reconciles: ₹9,016 opening − ₹848 movement + ₹174 exchange = ₹8,342 closing. Financing includes dividends ₹44,864 crore and interest ₹840 crore; the ₹17,000 crore buyback is the prior-year comparative. CFO / owner-attributable profit = 48,908 / 48,553 = 1.00731x; using group profit ₹48,797 gives 1.00227x. State which denominator is used.
APSEZ: consolidated cash generation and capex, FY2024–25
| Audited consolidated item | ₹ crore |
|---|---|
| Operating cash inflow | 17,226.28 |
| PPE/intangible capital cash outflow | 8,048.92 |
| Net investing outflow | 9,787.27 |
| Net financing outflow | 6,915.52 |
| Depreciation/amortisation | 4,378.93 |
| Interest/finance charges paid | 2,578.50 |
| Simple CFO less the stated capex cash outflow | 9,177.36 |
Under this explicitly stated simple FCF definition, ₹17,226.28 − ₹8,048.92 = ₹9,177.36 crore positive. Net investing includes items beyond capex; do not substitute its entire amount for capital expenditure. Net financing is an outflow, so this statement does not support the former story of an operating cash deficit funded by net borrowing. This FCF measure is an analytical calculation, not an additional statutory cash-flow line.
Eternal: consolidated operating cash is not the same as profit, FY2024–25
| Reported consolidated item | ₹ crore |
|---|---|
| FY2024–25 profit | 527 |
| FY2024–25 operating cash inflow | 308 |
| FY2023–24 operating cash inflow | 646 |
| FY2024–25 share-based payment expense | 798 |
| FY2024–25 net investing outflow | 7,993 |
FY2024–25 operating cash is positive, but below the prior year’s already-positive ₹646 crore: it is not the first full positive year. The ₹798 crore share-based expense is a non-cash operating reconciliation item, not a cash receipt; working-capital movements and other adjustments still affect CFO. Investing flows include securities, deposits and acquisitions separately from operating performance. Positive CFO alone does not prove that future equity financing will be unnecessary.
10. IGAAP vs Ind AS 7
🔴 IGAAP (AS 3)
- Also has three activities classification
- No explicit encouragement of direct method
- Bank overdrafts treated as financing
- No requirement to disclose non-cash transactions
- Lease payments: operating lease as operating CF
- Less guidance on components of cash equivalents
🟢 Ind AS 7
- Encourages direct method (though indirect permitted)
- Bank overdrafts part of cash & equivalents if repayable on demand
- Must disclose significant non-cash transactions separately
- Lease payments split: principal (financing), interest (financing/operating)
- Restricted cash must be reconciled
- More detailed guidance on classification choices
Ind AS 116 Impact on Cash Flows
Under Ind AS 116 (Leases), operating lease payments are no longer classified entirely as operating outflows. Instead:
- Principal portion of lease liability payment → Financing outflow
- Interest portion of lease liability payment → Financing or Operating (per accounting policy)
This significantly changed operating cash flows for companies with large operating lease portfolios (retail, aviation, restaurants). Flipkart/Myntra's lease costs on warehouses shifted from operating to financing CF post-Ind AS 116 adoption.
✅ Key Takeaways — Ind AS 7
- Cash flows classified into three buckets: Operating, Investing, Financing
- Indirect method (most common): starts with PBT, adjusts for non-cash and working capital changes
- Cash equivalents: maturities ≤ 3 months only
- Apply the prescribed Ind AS 7 interest/dividend classifications; do not import IAS 7’s options into Ind AS.
- Ind AS 116 shifted lease principal payments to financing activities
- Non-cash transactions (asset swaps, conversion of debt to equity) must be disclosed but not on the face of the statement
- Free Cash Flow = Operating CF – Capex — the most-watched investor metric
Updated analysis for Tax Year 2026-27: Cash Flow Statement: Indirect Method Worked Example and Reconciliation
Added and reviewed on 9 October 2026. This section adds worked examples and current-year controls to the guide above; where the two differ, follow the statute and the latest notification.
Start with a clean cash definition
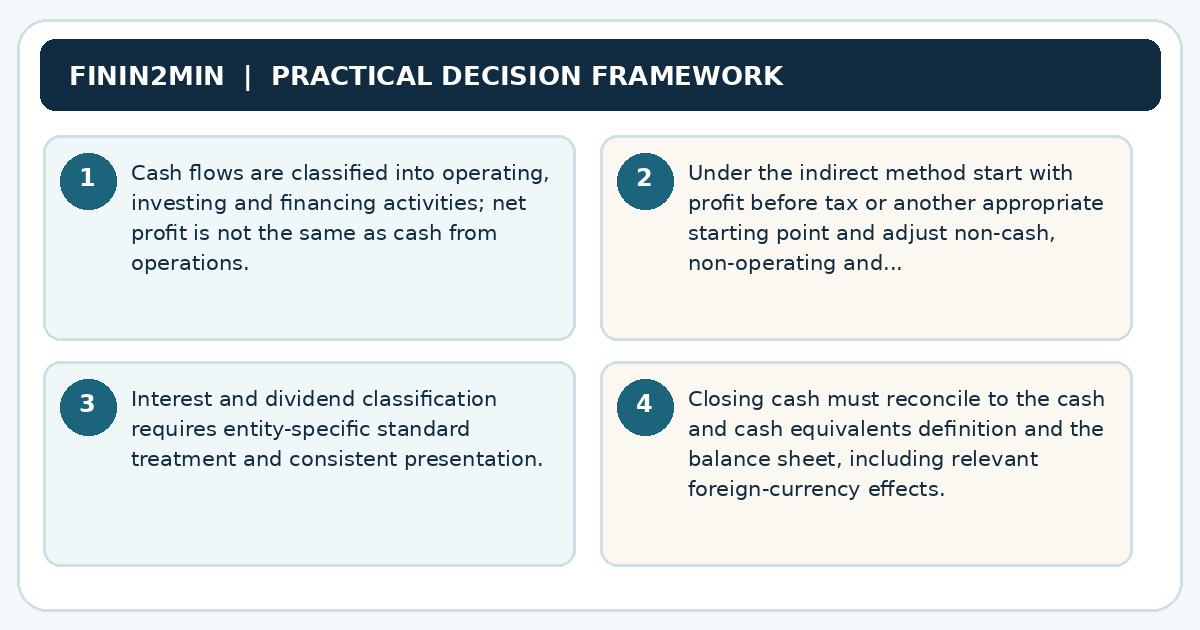
A statement of cash flows explains the movement in cash and cash equivalents over the reporting period, not the movement in all bank-related GL balances. Cash equivalents are short-term, highly liquid investments readily convertible into known cash amounts and subject to insignificant value-change risk, assessed under Ind AS 7. Restricted balances, margin money and investments outside the definition may require separate presentation or disclosures. Reconcile opening and closing cash to individual bank, petty-cash and relevant cash-equivalent accounts. In consolidated accounts, treat acquisition or disposal of subsidiaries appropriately rather than simply summing a bank-ledger export. Determine if bank overdrafts form part of cash management within the precise standard criteria.
Operating cash flows under the indirect method
For a non-financial business, start from an appropriate profit measure and strip out non-cash depreciation, impairment, unrealised items and gains or losses attributable to investing or financing transactions as required. Then adjust changes in operating receivables, inventories, payables and other working-capital accounts. An increase in trade receivables is usually a cash outflow relative to recognised revenue; an increase in payables is ordinarily a source of cash, subject to non-cash and financing exclusions. Adjust the movement for foreign-exchange effects, acquisitions, reclassifications and non-operating amounts. Income taxes paid are disclosed under the standard’s classification rules, with separately identifiable investing/financing taxes considered where appropriate.
Worked case: ₹13 lakh from operations
Suppose profit before tax is ₹15 lakh. Add ₹4 lakh depreciation, remove ₹1 lakh gain on plant disposal and add back ₹3 lakh finance cost to arrive at ₹21 lakh before working-capital changes. Receivables rose ₹4 lakh and inventory rose ₹2 lakh, while trade payables rose ₹3 lakh: net reduction ₹3 lakh, leaving ₹18 lakh cash generated from operations. After ₹5 lakh income tax paid, net cash from operating activities is ₹13 lakh. Every number assumes there were no hidden non-cash transactions or financing components in those working-capital movements. Finance cost is adjusted here to enable separate presentation of associated cash payments under the chosen accounting treatment.
Investing and financing examples: closing the bridge
Continuing the example, assume the company paid ₹8 lakh for equipment and received ₹2 lakh from a disposal; net investing cash flow is negative ₹6 lakh. It borrowed ₹10 lakh, repaid ₹5 lakh principal, paid ₹2 lakh dividend and paid ₹3 lakh interest classified as financing under the relevant non-financial-company accounting policy; net financing cash flow is zero. Total cash movement is therefore ₹13 lakh less ₹6 lakh plus zero, or an increase of ₹7 lakh. If opening cash and cash equivalents was ₹9 lakh, closing cash is ₹16 lakh, ignoring exchange translation and changes in cash-equivalent definition. Show why interest expense added back earlier cannot be ignored when the actual cash interest is paid.
Direct versus indirect method and disclosure choices
The direct method reports significant classes of gross operating receipts and payments, while the indirect method reconciles earnings to operating cash generation. Both seek faithful classification, but the direct method requires robust receipts and payments mapping. A cash-flow preparation module should not label all customer-bank receipts as revenue cash flows if they include loan advances, asset disposals or refunds. Likewise, statutory taxes, investment sales, principal repayments and dividends must follow the applicable classification. A bank statement alone cannot give an accurate statement because accrued revenue, non-cash acquisitions, unrealised FX movements and offset arrangements complicate period matching. Maintain a detailed mapping from ledger movements to reported classifications.
Non-cash transactions and foreign exchange
A machine purchased through a finance lease or a business combination settled by issuing shares can change assets and liabilities without moving cash at inception. Such non-cash investing or financing activities are excluded from the main cash flow totals and disclosed elsewhere as required. Foreign-currency cash holdings need translation at relevant rates; the exchange effect on cash and cash equivalents is presented separately from operating, investing and financing movements. Avoid plugging a residual amount called other operating changes whenever the bridge does not reconcile. Residuals often conceal incorrectly treated lease liabilities, tax refunds, cash-equivalent transfers or unrealised translation effects.
Control framework for monthly and annual cash bridges
Reconcile the P&L, balance sheet, asset register, borrowings schedule, equity movements and taxes paid before finalising the cash statement. Create a non-cash adjustment register linking each exceptional journal to the source voucher. Show prior-year comparatives on a consistent classification basis and separately analyse presentation changes. A robust review tests whether financing inflows can be matched to sanctioned facilities and bank credits, and whether investing cash additions agree with paid capital expenditure rather than only capitalised cost. Management should read the results alongside free cash flow and working-capital days rather than judging performance from EBITDA alone.
Practitioner checklist
- Reconcile cash and cash-equivalent opening and closing totals.
- Separate non-cash, operating, investing and financing movements.
- Build a detailed working-capital bridge net of reclassifications.
- Match loan, dividend and interest cash to bank records.
- Explain any FX translation and off-statement non-cash transaction.
Questions readers ask
Is depreciation added back to operating cash?
Yes, in an indirect reconciliation because it is generally a non-cash P&L expense.
Does higher profit always mean higher operating cash?
No. Working capital and non-cash earnings can cause major differences.
Where is equipment purchase presented?
Normally investing activities, based on the relevant Ind AS 7 requirements.
Must interest paid always be operating?
No. Classification depends on applicable requirements and entity characteristics, and must be consistent.
Why does the cash statement not match the bank balance?
The accounting definition of cash equivalents, restrictions, overdrafts or translation may explain differences.
Can changes in assets always be treated as cash flows?
No. Strip out non-cash movements and transactions from acquisitions, exchange effects and reclassifications.
Official sources for this update
- ICAI - Educational Material on Ind AS 7, Statement of Cash Flows
- ICAI - Ind AS Volume II (Ind AS 1, 7, 12, 16 and 19)
- Ministry of Corporate Affairs - Companies Act 2013, including Schedules II and III
Related reading on Finin2min
11. Frequently Asked Questions
Net profit is based on accrual accounting, which means it includes revenue recognized but not yet collected (debtors), and excludes cash payments for assets (capitalised as capex). Operating cash flow strips out these distortions and shows the actual cash the business generated.
Signs of earnings quality concerns: If a company consistently reports high profits but low operating cash flows, it could mean: (1) Revenue is being recognized aggressively while collections lag, (2) Expenses are being capitalized instead of expensed, (3) Inventory is building up without corresponding sales.
Example: Infrastructure companies like IL&FS reported profits for years while cash flows were negative — a warning sign missed by many analysts. Conversely, Indian IT companies like TCS and Infosys consistently show operating CF > net profit, indicating high earnings quality (low working capital, no inventory, fast collections).
For valuation, many analysts use EV/FCF (Enterprise Value to Free Cash Flow) rather than P/E, as it removes accounting distortions. Warren Buffett's "owner earnings" concept uses operating CF minus maintenance capex — directly computable from the cash flow statement.
This is a common practical question in India. Ind AS 7 requires cash flows to be reported on a gross basis as a general rule, but certain items (including agent collections) can be reported on a net basis.
GST collected from customers: GST collected is not income — it is a liability (collected on behalf of the government). Therefore, cash received from customers should be shown excluding GST in the direct method. If using the indirect method, starting from PBT automatically excludes GST since revenue is reported net of GST in P&L.
TDS deducted: When a customer deducts TDS before paying, the actual cash received is net of TDS. The TDS amount is credited to the company's tax account. In cash flows: the cash receipt is the actual amount received (net of TDS), and the TDS recoverable is treated as a reduction in taxes paid rather than as cash received.
Refund of excess TDS/GST: Tax refunds received are typically classified as operating activities (since income taxes paid are operating). GST refunds (common for exporters with accumulated ITC) are also typically operating.
Non-cash transactions are investing or financing activities that do not require cash flows and therefore must be excluded from the main cash flow statement. However, Ind AS 7 requires these to be disclosed elsewhere in the financial statements (usually in Notes) so that users understand the full financing and investing activities.
Common non-cash transactions in India:
- Conversion of debentures to equity: The debt is extinguished and equity is issued — no cash changes hands. Disclosed in Notes.
- Acquisition of assets under finance lease/Ind AS 116: Recognition of ROU assets and lease liabilities at commencement is non-cash. Only actual cash payments (lease rentals) appear in the statement.
- Asset acquired via share swap in M&A: Tata Motors acquiring Jaguar Land Rover partly via share consideration — the non-cash portion excluded from cash flow statement.
- Bonus shares issued: No cash involved — transfer from reserves to share capital. Non-cash financing transaction.
- Equity-settled ESOPs vesting: ESOP expense in P&L is non-cash (share-based payment) — added back in indirect method.
The disclosure ensures users can reconstruct the full picture of capital allocation even for non-cash items. Ind AS 7 para 43 specifically requires disclosure of significant non-cash investing and financing activities.
Related Ind AS Articles
Source and review trail
Use the current official instrument, portal or regulator publication before acting.
- Primary category
- Accounting, Audit & Ind AS
- Official starting point
- www.icai.org