Ind AS 116: Leases — ROU Asset, Lease Liability & Impact on EBITDA with Case Studies
Page content
Reviewed by CA Nikhil Gupta · Last reviewed 9 October 2026
Ind AS 116 — Leases, converged with IFRS 16 — eliminated the distinction between operating and finance leases for lessees. Under the new standard, almost all leases must be brought on-balance-sheet as a Right-of-Use (ROU) asset and a corresponding Lease Liability. This has dramatically reshaped the balance sheets and income statements of asset-light businesses — retailers, airlines, hotels, logistics companies — and inflated their EBITDA while increasing reported debt. Effective 1 April 2019, it is one of the most impactful Ind AS standards for Indian listed companies.
📜 In This Article
- Scope & key definitions
- Lessee accounting: ROU asset and Lease Liability
- Initial recognition and measurement
- Subsequent measurement — ROU asset and Lease Liability
- Variable lease payments — inclusion and exclusion
- Lease modifications
- Short-term & low-value lease exemptions
- Case Study — Indian Retailer (DMart/Reliance Retail type)
- Case Study — Aviation Company (IndiGo/Air India type)
- Case Study — Office lease (IT company)
- EBITDA impact and financial ratio distortion
- Lessor accounting — finance vs operating lease
- Sale and leaseback transactions
- Disclosures under Ind AS 116
- Transition approaches
- Common audit areas
| Structural block | What it covers |
|---|---|
| Objective and scope | Establishes principles for recognition, measurement, presentation and disclosure of leases — brought nearly all leases onto the lessee’s balance sheet, eliminating the previous operating/finance lease distinction for lessees. |
| Identifying a lease | A contract is (or contains) a lease if it conveys the right to control the use of an identified asset for a period of time in exchange for consideration — control requires both the right to obtain substantially all economic benefits from use and the right to direct the asset’s use. |
| Lessee accounting — recognition and initial measurement | A lessee recognises a right-of-use (ROU) asset and a lease liability at the commencement date — the liability at the present value of remaining lease payments, discounted using the rate implicit in the lease (or, if not readily determinable, the lessee’s incremental borrowing rate). |
| Lessee accounting — subsequent measurement | The ROU asset is generally depreciated on a straight-line basis (like PPE) and tested for impairment under Ind AS 36; the lease liability is subsequently measured like a financial liability, accreting interest and being reduced by payments made, remeasured for lease modifications and certain reassessments (e.g. changes in extension/termination option assessments). |
| Exemptions | Recognition exemptions are available (but not mandatory) for short-term leases (12 months or less, no purchase option) and leases of low-value underlying assets — these can continue to be expensed on a straight-line or other systematic basis. |
| Lessor accounting | Lessor accounting is largely unchanged from the previous leases standard — a lessor continues to classify each lease as either a finance lease (substantially transferring risks/rewards) or an operating lease, with different subsequent accounting for each. |
Standard Reference: Ind AS 116 issued by MCA vide Companies (Indian Accounting Standards) (Amendment) Rules, 2019. Converged with IFRS 16 (effective 1 January 2019 globally). Mandatory for all Ind AS companies for annual periods beginning on or after 1 April 2019. Supersedes Ind AS 17.
1. Scope and Key Definitions
Ind AS 116 applies to all leases, including subleases. Exclusions:
- Short-term leases: lease term of 12 months or less at commencement date
- Leases of low-value assets (IASB threshold: USD 5,000 underlying asset value when new; MCA has not prescribed a specific Indian rupee threshold — most entities use ₹3.5–5 lakh)
- Leases of intangible assets (optional exemption)
- Leases to explore/use minerals, oil, natural gas
- Service concession arrangements
Lease definition: A contract (or part of a contract) that conveys the right to control the use of an identified asset for a period of time in exchange for consideration. The key test: does the customer have the right to obtain substantially all the economic benefits from use AND the right to direct the how and for what purpose the asset is used?
2. Lessee Accounting — The New Balance Sheet Model
Under Ind AS 116, lessees recognise for virtually all leases:
- A Right-of-Use (ROU) asset representing the lessee's right to use the underlying asset
- A Lease Liability representing the obligation to make lease payments
🔴 Under Ind AS 17 (Old)
- Operating lease: off-balance-sheet; expense only
- Finance lease: on-balance-sheet asset + liability
- High leverage companies preferred operating leases to hide debt
- EBITDA reflected actual operating costs
🟢 Under Ind AS 116 (New)
- ALL leases (>12 months, >low value): on-balance-sheet
- ROU asset depreciated; Lease Liability carries interest
- Rent expense replaced by depreciation + interest
- EBITDA inflates (lease cost moves below EBITDA line)
3. Initial Recognition and Measurement
Lease Liability — Initial Measurement
At commencement date, the lease liability = present value of lease payments not yet made, discounted at the incremental borrowing rate (IBR) of the lessee (or the implicit rate in the lease if determinable).
Lease payments included in the liability:
- Fixed payments (including in-substance fixed payments)
- Variable lease payments that depend on an index or rate (at commencement date index value)
- Exercise price of a purchase option if reasonably certain to exercise
- Penalty payments for terminating if the lease term reflects the lessee exercising a termination option
- Amounts expected to be payable under residual value guarantees
Excluded from lease liability: Variable payments based on performance (revenue-linked rent, per-unit-sold rent), payments for non-lease components (service charges, insurance billed separately)
ROU Asset — Initial Measurement
ROU Asset = Lease Liability + Lease payments made at or before commencement + Initial direct costs + Restoration/decommissioning provision − Lease incentives received
4. Subsequent Measurement
Lease Liability
Each period: increase by interest (Lease Liability × IBR) and decrease by lease payments made.
ROU Asset
The ROU asset is depreciated on a straight-line basis over the shorter of: lease term or useful life of the underlying asset (if ownership is expected to transfer or purchase option is certain to be exercised, use useful life).
🏠 Case Study 1: Large Indian Retailer (DMart / Reliance Retail type)
Scenario: RetailCo has 500 stores, each with average lease of ₹8 lakh/month, average remaining lease term of 7 years. IBR: 8%.
Aggregate lease liability calculation:
| Parameter | Value |
|---|---|
| Monthly rent per store | ₹8,00,000 |
| Average remaining lease term | 84 months (7 years) |
| IBR | 8% per annum (0.667% per month) |
| PV factor (84 months @ 0.667%/month) | ~64.16 |
| Lease Liability per store | ₹8,00,000 × 64.16 = ₹5,13,28,000 |
| Total Lease Liability (500 stores) | ₹2,566 crore |
| ROU Asset recognised | ₹2,566 crore |
Financial statement impact (Year 1):
| Metric | Before Ind AS 116 | After Ind AS 116 | Change |
|---|---|---|---|
| Total Assets | ₹5,000 Cr | ₹7,566 Cr | +51% |
| Total Debt (Lease Liability) | ₹500 Cr | ₹3,066 Cr | +513% |
| Rent Expense | ₹480 Cr/yr | ₹0 | Eliminated |
| Depreciation (ROU) | ₹0 | ₹367 Cr/yr | +₹367 Cr |
| Finance Cost (Lease) | ₹0 | ₹205 Cr/yr | +₹205 Cr |
| EBITDA | ₹800 Cr | ₹1,280 Cr | +60% ↑ |
| EBIT (PAT not affected much) | ₹600 Cr | ₹913 Cr | +52% |
| Debt/Equity ratio | 0.5x | 3.0x | 6x increase |
✈ Case Study 2: Aviation Company (IndiGo/Air India type)
Scenario: AirCo has a fleet of 150 Airbus A320 aircraft, each leased for 12 years at USD 450,000/month (₹3.75 crore/month at ₹83/$). IBR: 6.5% per annum.
Per Aircraft PV calculation:
| Item | Value |
|---|---|
| Monthly lease payment | ₹3.75 Cr |
| Lease term | 144 months (12 years) |
| Monthly IBR | 0.542% |
| PV of lease payments per aircraft | ~₹370 Cr |
| Total fleet Lease Liability (150 aircraft) | ~₹55,500 Cr |
IndiGo's actual balance sheet post-Ind AS 116: Lease Liabilities jumped from near-zero to approximately ₹25,000–28,000 crore, making it technically one of the most leveraged airlines on paper — despite being profitable operationally. This is entirely explained by Ind AS 116 accounting, not actual borrowing.
Income statement impact per aircraft, Year 1:
| Cost | Pre-Ind AS 116 | Post-Ind AS 116 |
|---|---|---|
| Lease/Aircraft rental expense | ₹45 Cr/yr | ₹0 (reclassified) |
| Depreciation — ROU Asset | ₹0 | ₹31 Cr/yr (₹370Cr ÷ 12yr) |
| Finance cost — lease interest | ₹0 | ₹24 Cr/yr (Year 1) |
| EBITDA per aircraft impact | Base | +₹45 Cr (rent removed) |
| PBT per aircraft impact | Base | ~−₹10 Cr (front-loaded interest) |
5. Short-Term & Low-Value Exemptions
Two practical expedients allow lessees to avoid ROU/Liability recognition:
- Short-term lease: Lease term at commencement is 12 months or less (including renewal options reasonably certain to exercise). Lease payments expensed straight-line. Applied per class of underlying asset.
- Low-value asset lease: When the underlying asset is of low value (e.g., laptop, small office equipment, individual items of furniture). Applied asset-by-asset; no class election needed.
6. Lease Modifications
A lease modification is a change in scope or consideration that was not part of the original terms. Treatment depends on whether the modification effectively creates a new lease:
- Adds right to use additional assets at standalone price: New separate lease — account as a new lease
- All other modifications: Remeasure lease liability at revised lease payments, using a revised discount rate; corresponding adjustment to ROU asset
7. EBITDA Impact & Ratio Distortion — The Analyst's Problem
Ind AS 116 has created significant comparability issues that analysts and investors must adjust for:
| Ratio | Pre-Ind AS 116 Direction | Post-Ind AS 116 Direction | Why |
|---|---|---|---|
| EBITDA margin | Base | Inflated (rent removed from EBITDA) | Rent reclassified below EBITDA |
| EV/EBITDA | Base | Lower multiple (higher EBITDA, higher EV) | Both numerator and denominator change |
| Debt/Equity | Base | Significantly higher | Lease liability added as debt |
| Interest coverage | Base | May deteriorate (more finance cost) | Lease interest added to finance cost |
| Return on Assets | Base | Lower initially | ROU asset inflates total assets |
| PAT (Net profit) | Base | Slightly lower in early years | Front-loaded interest > straight-line rent |
💻 Case Study 3: IT Company Office Lease with Lease Incentive
Scenario: Tech Corp signs a 10-year office lease: ₹80 lakh/month starting Month 7 (first 6 months rent-free as lease incentive). Security deposit: ₹5 crore (refundable at end of lease).
Key Ind AS 116 adjustments:
- Rent-free period does NOT mean zero payments — the lease liability calculation must still include all 120 months of the lease but zero payments for months 1-6
- Lease payments = ₹0 (months 1-6) + ₹80 lakh (months 7-120) = 114 payments of ₹80 lakh
- Refundable security deposit: measured at fair value (at IBR) and recognised as a financial asset under Ind AS 109; the difference between deposit paid and FV is prepayment
| Item | Amount |
|---|---|
| Total undiscounted payments | 114 × ₹80L = ₹91.2 Cr |
| PV of lease payments (IBR 9%, 120 months) | ~₹62.4 Cr |
| ROU Asset = PV of liability | ₹62.4 Cr |
| Annual Depreciation (₹62.4 Cr ÷ 10 yr) | ₹6.24 Cr |
| Year 1 Finance cost (months 1-6 interest accrues on liability) | ~₹2.8 Cr |
| Year 1 Depreciation | ₹6.24 Cr |
| Total P&L charge Year 1 | ₹9.04 Cr (vs ₹0 rent in months 1-6) |
8. Lessor Accounting
Lessor accounting under Ind AS 116 is substantially unchanged from Ind AS 17:
- Finance lease (lessor): Recognise a receivable equal to the net investment in the lease; derecognise the underlying asset; recognise interest income over the lease term
- Operating lease (lessor): Continue to recognise underlying asset; recognise lease income on straight-line basis (or other systematic basis representing the pattern of benefit decline)
A lease is a finance lease if it transfers substantially all the risks and rewards of ownership — key indicators include: lease term covers major part of asset's life, PV of lease payments is substantially all of asset's fair value, transfer of ownership, bargain purchase option.
9. Sale and Leaseback Transactions
If an entity sells an asset and leases it back from the buyer:
- If the transfer is a sale (using Ind AS 115 criteria): recognise the sale proceeds; recognise ROU asset proportionate to rights retained; recognise gain/loss only for rights transferred
- If the transfer is NOT a sale (e.g., the leaseback is for the entire remaining useful life): do not derecognise asset; recognise a financial liability for proceeds received (effectively a secured borrowing)
Sale-and-leaseback is common in India for real estate (office buildings, factories), aircraft, and IT equipment. Post-Ind AS 116, the accounting for these arrangements is significantly more complex.
10. Key Disclosures — Ind AS 116
| Disclosure | Required Information |
|---|---|
| Maturity analysis | Undiscounted lease liability payments by year (1yr, 2-5yr, 5yr+) |
| Lease amounts in P&L | Depreciation of ROU, interest on lease liability, short-term/low-value expense, variable lease expense |
| Balance sheet | Carrying amount of ROU assets (by class); opening and closing lease liabilities |
| Cash flow | Principal repayments (financing activities); interest paid (financing or operating); short-term/low-value/variable payments (operating) |
| Significant judgements | Lease term determination (renewal options), IBR determination, variable payment estimation |
✅ Key Takeaways — Ind AS 116
- All leases (>12 months, >low value) now on-balance-sheet as ROU Asset + Lease Liability
- Retail, aviation, hospitality, logistics companies most impacted — massive increase in reported debt
- EBITDA inflates significantly (rent expense moves below EBITDA line)
- Analysts must calculate "Adjusted EBITDA" excluding lease depreciation for pre/post comparisons
- Lease term must include renewal periods if reasonably certain to exercise — key judgement area
- Lessor accounting largely unchanged; only lessee accounting radically changed
- Sale-and-leaseback: complex treatment; gain limited to rights transferred
- IBR determination is a key estimate — must reflect lessee's borrowing cost in the specific economic environment
❓ Frequently Asked Questions
Under Ind AS 116, operating lease rent expense is replaced by (1) depreciation of ROU asset and (2) interest on lease liability. Since depreciation and interest sit below the EBITDA line, EBITDA improves mechanically — even though the underlying economics are identical. For example, if a retailer previously had ₹100 Cr rent expense (which reduced EBITDA), under Ind AS 116 the same rent is split into ₹70 Cr depreciation and ₹35 Cr interest — both excluded from EBITDA. EBITDA inflates by ₹100 Cr. Analysts use 'EBITDA-L' (EBITDA after Leases) or 'Adjusted EBITDA' to restore comparability. The EBITDA multiple is not comparable across pre- and post-Ind AS 116 periods without this adjustment.
The lease liability is discounted at the rate implicit in the lease (if readily determinable) — i.e., the rate that makes the PV of lease payments equal to the fair value of the underlying asset. If the implicit rate cannot be readily determined (which is very common for operating property leases), the lessee uses its Incremental Borrowing Rate (IBR) — the rate at which the lessee would borrow a similar amount, in a similar currency, for a similar term, with similar collateral in the same economic environment. In India, the IBR is typically derived from the lessee's existing borrowing rates, government bond yields adjusted for credit spread, or other observable rates. The IBR is re-assessed when there is a lease modification or change in lease term.
No. Variable lease payments based on sales, revenue, usage, or performance are NOT included in the lease liability at commencement. Only variable payments that depend on an index or rate (e.g., CPI-linked escalations, base lending rate-linked rents) are included — using the index/rate at commencement date. Revenue-linked rents ('turnover rent') are expensed in the period in which they arise, as they don't create a predictable future obligation. This is significant for retail lessees: if a portion of rent is fixed and a portion is linked to store revenue, only the fixed portion enters the lease liability.
Updated analysis for Tax Year 2026-27: Ind AS 116 Lease Accounting: Liability, ROU Asset and Three-Year Example
Added and reviewed on 9 October 2026. This section adds worked examples and current-year controls to the guide above; where the two differ, follow the statute and the latest notification.
Identify a lease before building the schedule
A contract contains a lease when it conveys the right to control the use of an identified asset for a period in exchange for consideration. Determine whether a supplier has a substantive substitution right, who obtains the economic benefits and who directs the asset’s use. A dedicated floor in a building, leased data-centre equipment or a vehicle fleet arrangement can be different from a mere service promise. Lease accounting begins with analysis of the contract, associated schedules and practical ability to direct use. A label saying licence, service agreement or monthly facility charge does not by itself decide whether Ind AS 116 applies. Keep the signed contract and modification history tied to every lease ID.
Determine term, enforceability and payments
The non-cancellable period is adjusted for renewal or termination options when exercise or non-exercise is reasonably certain, considering real economic incentives. Construction-specific fittings, penalties, relocation costs and strategic locations can influence the decision. Payments may include fixed amounts, in-substance fixed amounts, amounts based on an index or rate, specified purchase/termination amounts and certain residual-value guarantees. Pure variable usage charges generally follow a different recognition approach unless in substance fixed. Separate non-lease components where allocation is required or an elected practical expedient applies. Document the basis for the incremental borrowing rate where an implicit rate cannot readily be determined; a corporate headline borrowing rate may not fit the lease term and security.
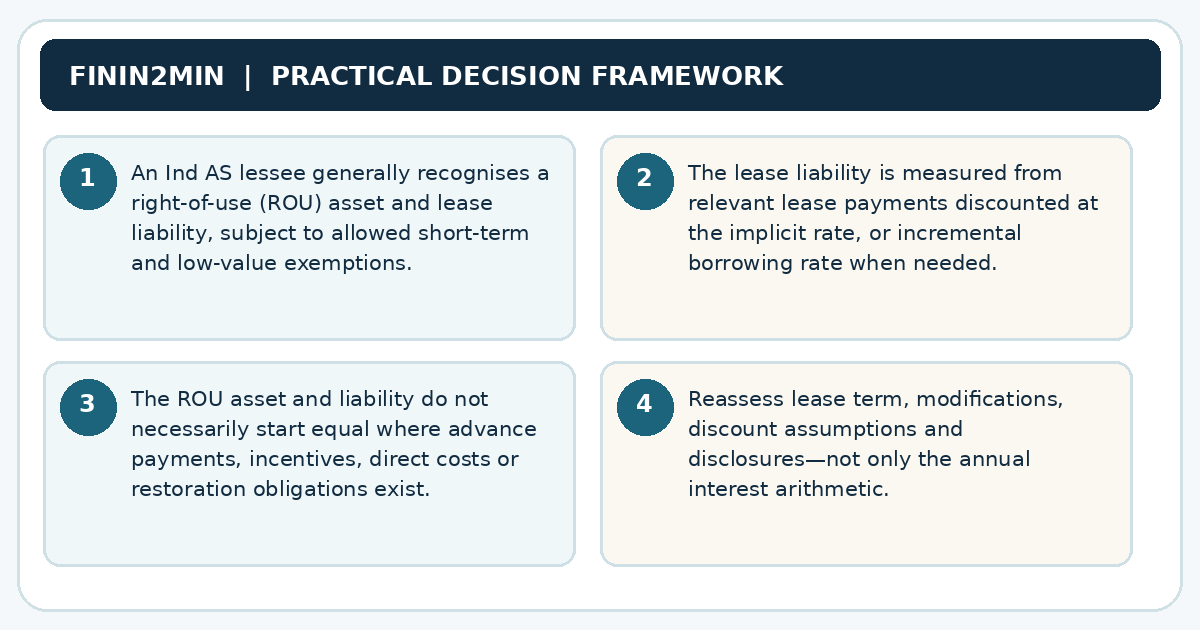
Initial measurement: why the two numbers may differ
At commencement the liability ordinarily equals the present value of remaining relevant lease payments. The ROU asset begins with that liability and adjusts for payments made at or before commencement, less incentives, plus initial direct costs and relevant restoration costs. A refundable security deposit should be separately assessed as a financial asset, potentially at a discounted fair value under Ind AS 109, rather than automatically added to the lease liability. For short-term leases and leases of low-value underlying assets, a lessee may elect permitted exemptions and expense relevant payments under the chosen policy. The designation of low value refers to the underlying asset characteristics, not simply a small monthly instalment.
Worked example: three end-of-year rentals
Suppose an office lease has three annual payments of ₹12 lakh at each year end, and a 10% annual discount rate. With no upfront payments, incentives, initial direct costs or restoration liability, opening lease liability is ₹12 lakh × [1/1.10 + 1/1.10² + 1/1.10³], or approximately ₹29.84 lakh. Year-one finance cost is about ₹2.98 lakh. After a ₹12 lakh lease payment, liability closes near ₹20.82 lakh; year two begins with interest on that outstanding balance. If the ROU asset is depreciated straight line over a three-year lease term with no residual value and no ownership transfer, illustrative annual depreciation is ₹9.95 lakh. Different assumptions, payment timing or taxes change these outcomes.
Journal entries and finance KPI consequences
On commencement debit ROU asset and credit lease liability for the initial amounts, reflecting any separately recognised adjustments. Later recognise finance costs on the liability, reduce principal by cash paid and depreciate the ROU asset. Lease payments in cash flows are classified consistently under the relevant cash-flow standard, taking account of principal and interest components. Compared with an expense-only operating lease depiction, EBITDA usually rises for lessee arrangements brought on balance sheet; depreciation and finance cost replace much of the old rental expense. However, total cash paid does not change. Covenant calculations, return-on-assets, operating cash flows and debt-like obligations must be assessed under the actual lending definition, not merely a published ratio.
Remeasurement, modification and variable rents
An extension option becoming reasonably certain may change the lease term and require remeasurement with an appropriate revised discount rate. A change in payments because of an index may require remeasurement under the standard’s particular rules, not always a brand-new discount rate. A modification increasing scope or consideration may constitute a separate lease if the criteria are met. Landlord rent concessions, early exit, reassignment of space and impairment of the underlying ROU asset have different accounting consequences. Do not treat each monthly rent revision as a simple adjustment to the rent ledger. Preserve the effective modification date, signed addendum, recalculated liability bridge and corresponding ROU asset entry.
Designing a robust lease schedule
A reliable lease register stores contract commencement date, monthly or annual frequency, payment timing, escalations, index mechanism, currency, discount rate, term options, component allocation, tax treatment, asset class and management judgments. The computation schedule should show each payment date, gross cash flow, present-value factor, finance cost, principal repayment and closing liability, with a zero or appropriately accounted remaining balance at maturity. Reconcile schedule totals to the GL by lease class and location. Run sanity checks for inappropriate negative principal, mismatched currencies, missing modification events and periods of zero-rent. The approved disclosure should include maturity and cash-flow information required by the standard, alongside the accounting policy and significant judgments.
Practitioner checklist
- Assess identified-asset and right-to-control criteria.
- Document lease term options and discount-rate evidence.
- Reconcile opening ROU and liability including adjustments.
- Check each schedule period and modification bridge.
- Review balance-sheet, P&L and cash-flow disclosures.
Questions readers ask
Can a lease liability equal all future undiscounted rent?
Normally no. Relevant lease payments are discounted at the applicable rate.
What if rent is paid at the start of each year?
It changes the initial PV and accounting for amounts paid before commencement.
Do all leases need an ROU asset?
Review permitted short-term and low-value exemptions and relevant elections.
What happens to EBITDA?
Capitalised lease expense patterns often change EBITDA even when the actual rent cash flow does not.
Which discount rate should be used?
Use rate implicit in the lease when readily determinable; otherwise evaluate the incremental borrowing rate.
Is a landlord deposit part of the lease liability?
Evaluate deposits under their own financial-instrument accounting, not as automatic fixed-rent payments.
Official sources for this update
- ICAI - Educational Material on Ind AS 116, Leases
- ICAI - Compendium of Indian Accounting Standards (2025-2026)
Related reading on Finin2min
- Ind AS 116 Lease Accounting: Calculating the Right-of-Use Asset and Lease Liability
- Three-way Match TDS Books Challan: AY 2026-27 Rules & Example
- Tally Erp Accounting Software Books: AY 2026-27 Rules & Example
- Digital Books Electronic Accounting: AY 2026-27 Rules & Example
- Companies Act, 2013 study guide hub
- Ind As 12 Income Taxes Deferred Tax Guide
- Ind As 7 Cash Flow Statements Guide
Source and review trail
Use the current official instrument, portal or regulator publication before acting.
- Primary category
- Accounting, Audit & Ind AS
- Official starting point
- www.icai.org