Ind AS 12: Income Taxes — Deferred Tax, DTA, DTL & Permanent Differences
Page content
Reviewed by CA Nikhil Gupta · Last reviewed 9 October 2026
Ind AS 12 — Income Taxes (converged with IAS 12) governs the accounting for current and deferred income taxes. The standard requires entities to recognise deferred tax for all temporary differences between accounting carrying amounts and tax bases, subject to specific exceptions. Deferred tax is one of the most pervasive and frequently misunderstood areas of financial reporting — affecting every entity that pays income tax. This guide covers the complete framework with journal entries and case studies.
📜 In This Article
- Current tax vs deferred tax
- Temporary differences — taxable and deductible
- Tax base of assets and liabilities
- Deferred Tax Liability (DTL) recognition
- Deferred Tax Asset (DTA) — recognition and recoverability test
- Unused tax losses and credits as DTA
- Special cases: revaluation, business combinations, OCI items
- Deferred tax rate — enacted vs substantially enacted
- Case Study — Depreciation difference (Accelerated tax depreciation)
- Case Study — Provision disallowed for tax (Warranty provision)
- Case Study — Unused tax losses (Start-up company)
- Deferred tax and MAT (Minimum Alternate Tax)
- Presentation and offsetting of deferred tax
- Disclosures — tax reconciliation and effective rate
| Structural block | What it covers |
|---|---|
| Objective and scope | Prescribes accounting for the current and future tax consequences of transactions already recognised in the financial statements — the mechanism by which deferred tax assets and liabilities arise. |
| Current tax | Tax payable/recoverable for the current period, measured using tax rates enacted or substantively enacted by the balance sheet date, based on the entity’s taxable profit. |
| Temporary differences | Differences between an asset/liability’s carrying amount and its tax base — taxable temporary differences give rise to deferred tax liabilities; deductible temporary differences and carried-forward losses give rise to deferred tax assets. |
| Recognition of deferred tax assets | Recognised only to the extent it is probable that future taxable profit will be available against which the deductible temporary difference/unused loss can be utilised — reassessed at each balance sheet date. |
| Measurement | Deferred tax is measured at the tax rates expected to apply when the asset is realised or liability settled, based on rates enacted/substantively enacted by the balance sheet date; not discounted to present value. |
| Presentation and disclosure | Offsetting rules for current and deferred tax assets/liabilities, the split between tax recognised in profit or loss versus OCI/equity, and a reconciliation between tax expense and accounting profit at the applicable statutory rate. |
Standard Reference: Ind AS 12, converged with IAS 12. Effective from Ind AS adoption date. Does not cover accounting for government grants (Ind AS 20) or investment tax credits. In India, interacts significantly with MAT (Section 115JB/115BAA) under the Income Tax Act.
1. Current Tax vs Deferred Tax
| Type | Definition | Balance Sheet | P&L |
|---|---|---|---|
| Current Tax | Tax payable/recoverable for current and prior periods, based on taxable profit and enacted tax rates | Current tax liability/asset | Current tax expense |
| Deferred Tax | Future tax consequences of temporary differences between accounting and tax carrying amounts | DTA (non-current asset) or DTL (non-current liability) | Deferred tax expense/income |
2. The Fundamental Concept: Temporary Differences
A temporary difference is the difference between the carrying amount of an asset/liability in the balance sheet and its tax base (the amount attributed to it for tax purposes).
- Taxable Temporary Difference (TTD): Will result in taxable amounts in future periods (when the asset is recovered or liability settled). → Creates Deferred Tax Liability (DTL)
- Deductible Temporary Difference (DTD): Will result in deductible amounts in future periods. → Creates Deferred Tax Asset (DTA)
Tax Base of an Asset: Amount deductible for tax when economic benefits are recovered. Example: a machine with book value ₹60 lakh and tax WDV of ₹40 lakh → tax base = ₹40 lakh → TTD = ₹20 lakh → DTL = ₹20L × 25.168% = ₹5.03 lakh.
Tax Base of a Liability: Carrying amount less amounts deductible for tax in future periods. Example: warranty provision of ₹10 lakh (not yet deductible for tax) → tax base = ₹0 → DTD = ₹10 lakh → DTA = ₹10L × 25.168% = ₹2.52 lakh.
3. Deferred Tax Liability (DTL) — Recognition
Recognise a DTL for all taxable temporary differences, except:
- Goodwill where amortisation is not deductible for tax
- Initial recognition exemption: asset/liability arising from a transaction that (a) is not a business combination AND (b) at the time of the transaction, affects neither accounting profit nor taxable profit
- Investments in subsidiaries/associates/JVs where the entity can control the timing of reversal and it is probable it will not reverse in the foreseeable future
4. Deferred Tax Asset (DTA) — Recognition
Recognise a DTA for deductible temporary differences, unused tax losses, and unused tax credits — only to the extent that it is probable that taxable profit will be available against which the deductible temporary differences can be utilised.
📊 Case Study 1: Accelerated Tax Depreciation (Most Common)
Scenario: ManufCo buys a machine for ₹1,00,00,000. Accounting: straight-line, 10-year life → ₹10L/year depreciation. Tax: Written Down Value method at 15% WDV → Year 1: ₹15L. Tax rate: 25.168% (including surcharge + cess).
| Year | Book WDV (₹L) | Tax WDV (₹L) | Taxable Temp Diff (₹L) | DTL (₹L) | DTL Movement |
|---|---|---|---|---|---|
| Year 1 | 90 | 85 | 5 | 1.26 | Create ₹1.26L DTL |
| Year 2 | 80 | 72.25 | 7.75 | 1.95 | Increase DTL by ₹0.69L |
| Year 5 | 50 | 44.37 | 5.63 | 1.42 | DTL reducing (book dep > tax dep) |
| Year 10 | 0 | 19.69 | -19.69 | (4.96) | DTA now; full reversal |
💊 Case Study 2: Warranty Provision (Deductible Temp Diff)
Scenario and tax assumption: ElecCo recognises a ₹50 lakh warranty liability. Deductibility when provided depends on the facts: the Rotork Controls tests require a present obligation from past sales, a probable outflow and a reliable estimate. If the full provision is deductible now, its tax base is ₹50 lakh and this item creates no temporary difference or DTA. Alternative: assume the provision is validly disallowed now but will become deductible when claims are settled. Only on that assumption is the liability tax base ₹0 and the deductible temporary difference ₹50 lakh. At the explicitly assumed 25.168% rate, the potential DTA is ₹12.584 lakh, displayed as ₹12.58 lakh, and recognition still requires probable taxable profits. An expense that will never be deductible does not create this DTA.
📈 Case Study 3: Unused Tax Losses — Start-up DTA
Scenario: EdStart Ltd (5-year-old edtech company) has cumulative business losses of ₹200 crore and unused carry-forward losses of ₹80 crore (that can be carried forward 8 years under income tax). Management projects profitability from FY2027 onwards with ₹150 crore taxable income over next 5 years.
DTA on carry-forward losses = ₹80 Cr × 25.168% = ₹20.13 Cr
Recognition test: Is it probable that sufficient taxable income will be available? Management's projections show ₹150 Cr taxable income over 5 years — more than enough to utilise ₹80 Cr loss carryforward before expiry. If projections are supported by contracts, business plans, and market growth data: recognise ₹20.13 Cr DTA.
If there is uncertainty about profitability (e.g., company is pre-revenue, highly speculative projections): do not recognise DTA. Many VC-backed start-ups with large losses do not recognise DTA — this creates a "hidden" tax asset that will be realised when the company turns profitable.
5. Deferred Tax and MAT
India has two tax regimes that interact with Ind AS 12:
- Regular tax (Section 115BAA for domestic companies: 22% + surcharge + cess = 25.168%): Normal deferred tax applies
- MAT (Minimum Alternate Tax — Section 115JB: 15% + surcharge + cess on book profits): MAT credit (excess of MAT over normal tax) creates a DTA — recognisable if it is probable that normal tax will be paid in future years. MAT credit carries forward for 15 years.
Since many profitable listed companies opted for the new 22% regime under Section 115BAA (which eliminated MAT for those opting in), MAT-DTA treatment has reduced complexity for many entities. However, companies still under old regime must maintain MAT credit DTA separately.
6. Key Disclosures — Tax Reconciliation
Ind AS 12 requires a reconciliation between:
- Tax expense at applicable rate (statutory rate × accounting profit before tax)
- Actual tax expense reported
Items causing the difference (tax rate reconciliation): permanent differences (expenses disallowed permanently), differential rates, tax-exempt income, uncertain tax positions, effect of deferred tax rate changes, impact of unrecognised DTA on losses.
✅ Key Takeaways — Ind AS 12
- Deferred tax arises from temporary differences between accounting carrying amount and tax base
- DTL: recognised for all taxable temporary differences (few exceptions)
- DTA: recognised only if probably recoverable from future taxable profits
- Unused tax losses: DTA recognised only if sufficient future taxable income is probable
- Rate: use enacted (or substantially enacted) tax rate expected when temporary difference reverses
- India: Section 115BAA companies use 25.168%; MAT credit DTA applies for companies under old regime
- Deferred tax on OCI items (e.g., remeasurement of defined benefit obligation, FVTOCI changes): recognised in OCI, not P&L
- Mandatory tax rate reconciliation disclosure: links statutory rate to effective tax rate
❓ Frequently Asked Questions
A temporary difference creates deferred tax — it originates when accounting treatment and tax treatment differ in timing, but will ultimately reverse. E.g., accelerated tax depreciation leads to DTL that reverses when book depreciation eventually exceeds tax depreciation. A permanent difference, in contrast, never reverses — it's an amount that is either permanently taxable or permanently non-deductible. Examples: expenses disallowed under Section 37 (personal expenses, unapproved payments), exempt dividends under Section 10(34), deductions under Section 80-IC. Permanent differences affect the effective tax rate but do not create deferred tax assets or liabilities.
Yes, but with strict conditions. Even a currently loss-making company can recognise DTA on carry-forward losses if it is probable that sufficient future taxable profit will be available — this could be supported by: signed long-term contracts providing revenue certainty, demonstrated turnaround with improving trend, tax planning opportunities (e.g., a planned property sale that will generate taxable gains), or reversal of existing taxable temporary differences (existing DTL that will create taxable income). The standard does not require profitability in the current year — it requires a probability assessment of future taxable income. However, 'convincing evidence' is required when the entity has a history of recent losses.
The deferred tax rate should be the enacted (or substantively enacted) tax rate expected to apply when the temporary difference reverses. For Indian domestic companies: if operating under Section 115BAA (22% base rate), use 25.168% (22% + 10% surcharge on tax + 4% cess). If under old regime (30%), use 34.944% (30% + 12% surcharge for large companies + 4% cess). Note: the rate applicable depends on the company's expected tax regime at the time the temporary difference will reverse — if a company plans to opt for 115BAA in the near future, it may use the 115BAA rate for future reversals. Rate changes must be reflected in deferred tax in the period when the new rate is enacted.
Updated analysis for Tax Year 2026-27: Deferred Tax Assets and Liabilities: Temporary Differences and Recognition
Added and reviewed on 9 October 2026. This section adds worked examples and current-year controls to the guide above; where the two differ, follow the statute and the latest notification.
Begin with tax base, not accounting profit differences
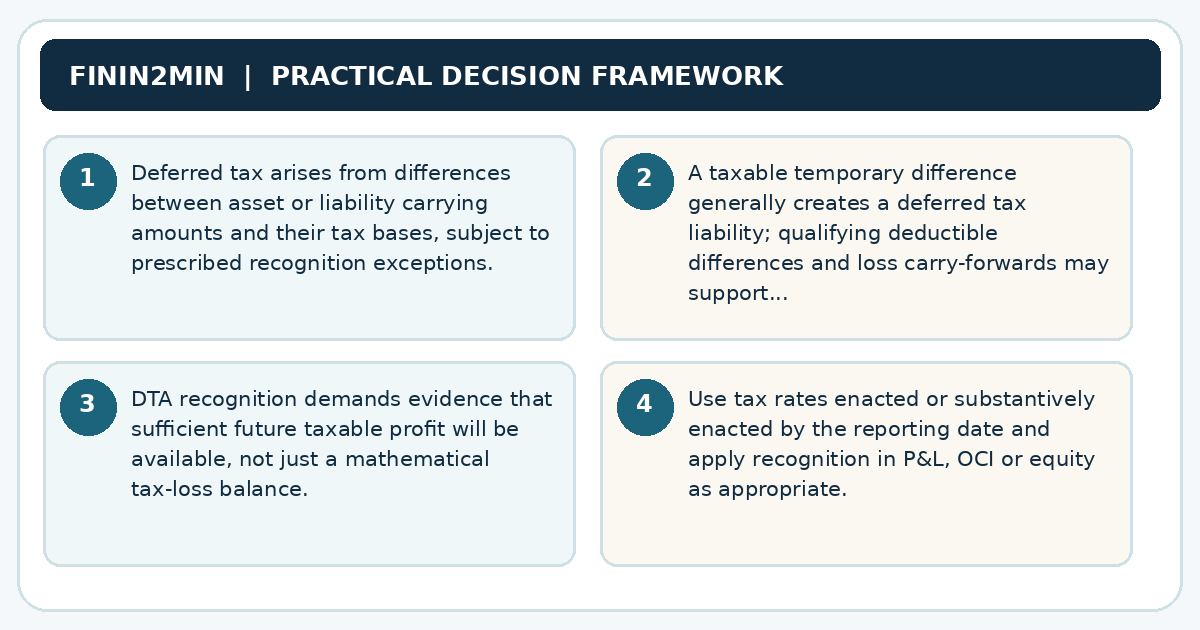
Ind AS 12 uses the balance-sheet liability approach. For each asset and liability, compare financial-statement carrying amount with the amount attributable under tax law, termed tax base. A difference may be taxable or deductible when an asset is recovered or liability settled. This differs from the old shortcut of multiplying annual book versus tax depreciation by a rate without tracking opening balances, reversals and exceptions. Create a register for PPE, leases, provisions, receivables, employee benefits, fair-value changes, tax losses and other material items. Determine whether an apparent permanent difference, such as a non-deductible penalty, truly gives rise to any future tax consequence; often it does not.
Illustration: depreciation changes the tax liability
A machine is carried in the books at ₹40 lakh but its tax-written-down value is ₹28 lakh. Assume the tax base is therefore ₹28 lakh and the relevant enacted future income-tax rate is an illustrative 25%. The taxable temporary difference is ₹12 lakh, creating a ₹3 lakh deferred tax liability, subject to the standard’s recognition conditions. Later, if book depreciation exceeds tax depreciation and the carrying and tax bases converge, the DTL reverses. Do not treat the ₹3 lakh as a tax currently due: it represents future consequences embedded in current carrying values. Surcharge, cess, regime rates and timing must be correctly incorporated for an actual entity.
Deductible differences and loss carry-forwards are not automatic assets
A ₹10 lakh deductible temporary difference could suggest an arithmetical ₹2.5 lakh deferred tax asset at 25%, but Ind AS 12 requires assessment of probable future taxable profits against which deduction can be used. Strong losses, expiring tax benefits, unstable business models and limited reversal sources reduce support for recognition. For unused tax losses and credits, the burden of evidence is particularly important when there is a history of recent losses. Separate tax-law eligibility from accounting recognition: a loss may technically carry forward while recovery is not sufficiently probable for a balance-sheet DTA. Use forecasts reconciled to board-approved plans and examine the reliability of past estimates.
Initial recognition exceptions, leases and combinations
The standard contains exceptions to deferred-tax recognition, including particular initial-recognition circumstances and goodwill-related situations. However, amendments concerning transactions that give rise to equal taxable and deductible temporary differences, such as some leases and decommissioning obligations, affect how the initial-recognition exemption is applied. Do not assume every new ROU asset and lease liability creates zero deferred-tax entries. A business combination can create deferred-tax consequences through fair-value allocations, altering goodwill or bargain-purchase outcomes. The correct approach depends on exact transaction facts and the version of the applicable Ind AS rules. Preserve the opening transaction-date schedule rather than deriving everything from year-end balances.
Tax rates and where deferred tax is recognised
Measure deferred taxes at rates expected to apply when temporary differences reverse based on rates enacted or substantively enacted by reporting date. For an entity eligible for a concessional regime, evaluate whether and when the election affects expected recovery and related tax rates. Deferred tax follows the underlying transaction: where a movement belongs in OCI or directly in equity, the associated tax effect may follow rather than flowing through profit or loss. Reconciliations should explain current tax expense, deferred tax expense, effective-tax-rate movements and changes in recognised versus unrecognised assets. Avoid using the statutory headline rate indiscriminately across tax-exempt activities and entities.
Reversal schedule, recoverability and judgement
Maintain a multi-year roll-forward by temporary difference and legal entity: opening carrying and tax bases, new differences, reversals, tax-law adjustments, applicable rates, recognised DTA/DTL and closing balance. Link foreseeable reversals to expected taxable profit of the same taxation authority and taxable entity, applying offset conditions carefully. Where a forecast depends on winning a major contract, disclose the sensitivity and revisit at each reporting date. A recognition judgment should be retrievable months later: model inputs, management review and evidence supporting profit timing must be retained. An Excel tool can illustrate arithmetic; it should never suppress the need to assess tax positions and legal eligibility.
Consolidation, presentation and common failure points
A consolidated group may have multiple tax entities, foreign rates and intercompany eliminations. A DTA in one company cannot automatically offset a DTL in another: the legally enforceable right and tax-authority conditions govern presentation. Deferred taxes are not discounted under Ind AS 12; they are measured under the standard’s rates and recovery assumptions. Beware using the wrong enacted year, failing to recognise deferred tax on fair-value adjustments, re-recognising previously written-off DTA without new convincing evidence and treating deferred taxes as cash liabilities. Review accounting policy disclosures, expiry periods of unrecognised benefits and material judgments with audit and tax specialists.
Practitioner checklist
- Compute carrying amount and tax base per item.
- Distinguish taxable, deductible and permanent differences.
- Test DTA recovery with reliable profit forecasts.
- Select applicable enacted reversal-period tax rates.
- Reconcile P&L, OCI, equity and balance-sheet movements.
Questions readers ask
Is deferred tax the same as advance tax?
No. Deferred tax concerns future tax consequences of present carrying values; advance tax is a current tax payment.
Does every book-tax difference create deferred tax?
No. Identify temporary differences and the specific recognition exceptions.
Can a loss-making startup recognise DTA?
Only to the extent Ind AS 12 recognition and evidence thresholds are satisfied.
Is deferred tax discounted?
No, Ind AS 12 does not use present-value discounting for deferred tax balances.
Can group DTA and DTL always be netted?
No. Assess the specific legal and accounting offset criteria.
Which tax rate should apply?
Use the enacted or substantively enacted rate expected for the reversal, including applicable rate components.
Official sources for this update
- ICAI - Educational Material on Ind AS 12, Income Taxes, March 2024
- ICAI - Ind AS Volume II (Ind AS 1, 7, 12, 16 and 19)
- ICAI - Compendium of Indian Accounting Standards (2025-2026)
Related reading on Finin2min
- Ind AS 38: Intangible Assets — Recognition & Impairment
- Ind AS 37: Provisions, Contingent Liabilities and Contingent Assets — Detailed Guide
- FLA Return for Indian Companies: Foreign Liabilities and Assets Reporting
- Deferred Tax Assets: When Future Tax Benefits Depend on Future Profits
- Companies Act, 2013 study guide hub
- Ind As 116 Leases Complete Guide
- Ind As 19 Employee Benefits Gratuity Guide
Source and review trail
Use the current official instrument, portal or regulator publication before acting.
- Primary category
- Accounting, Audit & Ind AS
- Official starting point
- www.icai.org