Partnership Firm Taxation in India: Tax Rates, Partner Remuneration & Interest Limits
Reviewed by CA Nikhil Gupta · Last reviewed 9 October 2026
Unlike individuals, a partnership firm (or LLP) doesn't get the benefit of tax slabs or basic exemption limits - profits are taxed at a flat 30% from the very first rupee. But the firm can reduce its taxable profit by paying remuneration and interest to working partners, within limits prescribed under Section 40(b). Get these limits wrong, and the excess gets added back and taxed again.
How Are Partnership Firms Taxed?
A partnership firm (registered or unregistered, governed by the Indian Partnership Act, 1932) and a Limited Liability Partnership (LLP, governed by the LLP Act, 2008) are both taxed as separate entities under the Income Tax Act, distinct from their partners. The key features of firm/LLP taxation are:
- Flat tax rate of 30% on total income - there are no slab rates and no basic exemption limit, unlike individual taxpayers.
- Surcharge: Applicable if total income exceeds the prescribed threshold (typically ₹1 crore), at the rate specified for firms.
- Health & Education Cess: 4% on the tax plus surcharge.
- No new vs old regime choice - the concept of choosing between tax regimes (as available to individuals/HUFs) does not apply to firms/LLPs; the flat 30% rate applies uniformly.
The Big Tax Planning Lever: Remuneration & Interest to Partners
While the firm itself is taxed at 30% flat, payments made by the firm to its working partners - in the form of salary, bonus, commission, or remuneration, and interest on capital - are deductible from the firm's taxable profit, subject to limits under Section 40(b). These amounts are then taxed in the hands of the individual partners as their personal income (under "Profits and Gains of Business or Profession" for remuneration, and "Income from Other Sources" or business income for interest, depending on the partner's status).
Section 40(b) Limits on Partner Remuneration
Remuneration paid to working partners only (not to non-working/sleeping partners) is deductible by the firm only if it is (a) authorized by the partnership deed, and (b) within the following limits computed on "book profit":
| Book Profit Slab | Maximum Deductible Remuneration |
|---|---|
| On the first ₹6,00,000 of book profit (or in case of a loss) | ₹3,00,000 or 90% of book profit, whichever is more |
| On the balance of book profit (above ₹6,00,000) | 60% of the balance book profit |
"Book profit" here means the net profit as per the firm's profit & loss account, adjusted as per the computation prescribed under Section 40(b) (broadly, net profit before deducting partner remuneration itself, with certain other adjustments).
Section 40(b) Limit on Interest to Partners
Interest paid by the firm to partners on their capital contributions is deductible only if:
- It is authorized by the partnership deed, and
- The rate does not exceed 12% per annum simple interest.
Any interest paid in excess of 12% per annum is disallowed in the firm's hands (added back to taxable profit) - even if the partnership deed permits a higher rate.
What Happens If Remuneration/Interest Exceeds the Limits?
Partner's Share of Profit After Remuneration/Interest
After deducting allowable remuneration and interest, the firm's remaining profit is taxed at 30% in the firm's hands. The partners' share of this post-tax profit (i.e., their share in the firm's profits as per the partnership deed, after the firm has already paid tax on it) is exempt in the hands of the partners under Section 10(2A), since it has already suffered tax at the firm level. This avoids double taxation of the same profit.
| Item | Taxed In Whose Hands? |
|---|---|
| Remuneration/salary/commission to working partners (within Section 40(b) limits) | Partner's individual income (business income), at slab rates |
| Interest on capital to partners (up to 12% p.a.) | Partner's individual income, at slab rates |
| Firm's remaining profit after the above deductions | Firm, at flat 30% + surcharge + cess |
| Partner's share of post-tax profit (per profit-sharing ratio) | Exempt in partner's hands under Section 10(2A) - already taxed at firm level |
LLPs vs Traditional Partnership Firms - Any Tax Difference?
For income tax purposes, LLPs are taxed almost identically to partnership firms - flat 30% rate, same Section 40(b) limits on partner remuneration and interest, and the same exemption for partners' share of profit under Section 10(2A). The main differences between LLPs and traditional firms relate to limited liability protection and compliance requirements under the LLP Act/Companies Act framework, not the core income tax computation.
2026 current-law quick reference
What changes the answer?
| What to check | What to do | Common mistake to avoid |
|---|---|---|
| Core classification | From AY 2025–26, deductible working-partner remuneration is capped at the higher of ₹3 lakh or 90% of book profit on the first ₹6 lakh (or loss), plus 60% of the balance; the article’s older ₹3 lakh/₹1.5 lakh slab is stale. | Do not decide from the label used on an invoice, agreement or bank narration alone. |
| Edge case | The deed must authorise remuneration/interest, remuneration is for working partners, and partner interest deduction remains capped at 12% p.a. | Recompute when the fact pattern crosses this boundary. |
| Evidence | Reconcile the documents below to the tax/regulatory return before filing. | A correct legal rule with an unreconciled evidence trail can still fail in assessment or audit. |
| Effective date | Apply the law/form/rate for the actual transaction, tax year or proceeding date. | Do not mix FY 2025–26/AY 2026–27 legacy references with post-1-April-2026 forms. |
Worked practical example
Book profit is ₹10 lakh and the deed authorises remuneration. The statutory ceiling is computed on first ₹6 lakh under the current limit, then 60% on the balance.
Evidence checklist
- partnership deed
- partner role evidence
- book-profit computation
- remuneration ledger
- interest/capital accounts
Primary-source checks: Income Tax Department — Firm · Income Tax Department — Business or Profession
How to use this: This current-law summary reflects the latest position. Where it conflicts with an older rate, threshold, form or section reference elsewhere on the page, rely on the current, dated primary source above.
Updated analysis for Tax Year 2026-27: Partner remuneration under section 40(b): maximum deduction
Added and reviewed on 9 October 2026. This section adds worked examples and current-year controls to the guide above; where the two differ, follow the statute and the latest notification.
The common mismatch between partner drawings and tax deduction
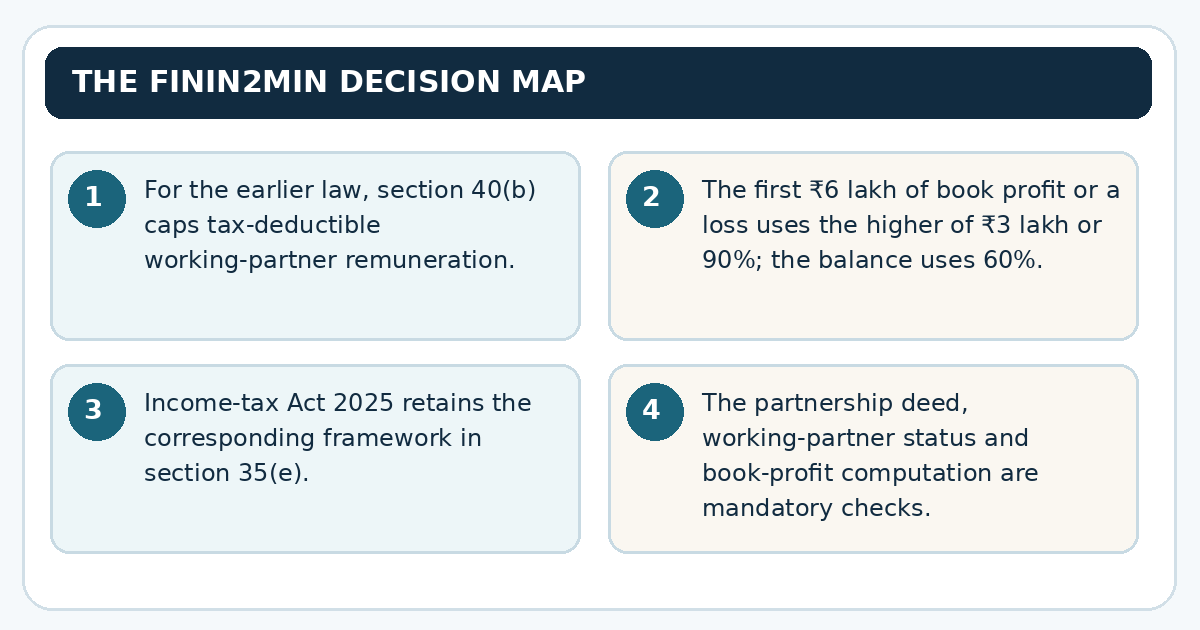
A partnership or LLP can transfer money to partners as capital drawings, reimbursement, interest or remuneration. These are not the same in law or accounting. Section 40(b) of the repealed 1961 Act restricts deductible remuneration to working partners and requires authority in the partnership deed; its counterpart under the 2025 Act is section 35(e). Simply crediting a partner current account cannot turn a nondeductible payout into an allowable expense. Finance should identify the economic nature of each credit and trace it to the deed, financial statement and tax computation.
Who is a working partner?
A working partner is an individual actively engaged in conducting the affairs of the firm’s business or profession. A passive investor who happens to be a partner does not satisfy that definition. The deed should specify authority and the method of remuneration. Partner interest requires separate review, including the 12% simple annual ceiling under the statute and the conditions in the deed. The definition does not mean every salaried employee of the partnership is a partner; it requires partnership status and active involvement. Keep evidence of responsibilities, partner resolutions and remuneration authorisation.
Correct post-Finance Act 2024 slab calculation
For the old-law periods to which the higher limits apply, total deductible working-partner remuneration cannot exceed the higher of ₹3 lakh or 90% of the first ₹6 lakh of book profit, plus 60% of the balance book profit. If book profit is a loss, the ceiling on the initial limb is ₹3 lakh. A frequently repeated old example uses ₹3 lakh as the first profit slab and ₹1.5 lakh minimum; that is no longer the correct FY 2025–26 framework. Always compute the aggregate cap for all working partners together before allocating payments across individual partners.
Worked example: ₹20-lakh book profit
Consider a firm whose tax-defined book profit before partner remuneration is ₹20 lakh. Ninety per cent of the first ₹6 lakh is ₹5.40 lakh, greater than the ₹3-lakh floor. Sixty per cent of the remaining ₹14 lakh is ₹8.40 lakh. The ceiling is therefore ₹13.80 lakh in total for all qualifying working partners, subject to the deed and other conditions. If the firm paid ₹15 lakh, the excess ₹1.20 lakh is not deductible solely by reason of the remuneration cap. If the deed authorised only ₹12 lakh, the allowed amount would not automatically increase to ₹13.80 lakh; the deed is an independent ceiling.
Book profit is not the P&L line called profit
The statute defines book profit using net profit as shown in the relevant profit and loss account computed under the business-income provisions, increased by aggregate partner remuneration when that remuneration was deducted. Therefore take care when the trial balance includes disallowed expenditure, depreciation adjustments or remuneration posted through current accounts rather than the P&L. A worksheet starting from earnings before partner remuneration may be a useful operational approximation but must be reconciled to the tax-defined book profit. Sign the profit bridge before applying the slab formula; small mistakes in the base are magnified by the 60% marginal cap.
Deed timing and interest conditions
The remuneration and interest should be authorised in accordance with the terms of the partnership deed for the period concerned. A later deed cannot automatically validate earlier amounts unless the statute and facts permit that position. Interest paid to partners above 12% simple per annum fails the ceiling to the extent of the excess, subject to other conditions. In an LLP, check the LLP agreement and its amendments with equivalent attention. Maintain dated executed agreements, supplementary deeds, bank records, ledger details and partner tax disclosures. Preserve the firm’s computation alongside partner-wise Form 16A or withholding records where applicable.
TDS after the separate section 194T change
Partner payment withholding is separate from deductibility. Withholding applies under the applicable partner-payment TDS provision to qualifying remuneration, salary, commission, bonus or interest and has its own thresholds and timing. The post-2026 new Act uses the corresponding section 393(3), Table serial 7 reference for partner payments. A firm cannot argue that remuneration is below the section 40(b) cap and therefore ignore TDS. Equally, TDS compliance does not cure a missing deed or excess remuneration. Reconcile partner expense, current-account credits, tax deducted, challan remittance and the partner’s taxable income independently.
Partner-level records and allocations
After establishing the maximum allowable aggregate remuneration, the firm should reconcile the actual amounts authorised and credited to each working partner. If two partners split remuneration 70:30, the allocation must follow the executed deed and any valid contemporaneous amendment. It must not be reverse engineered at return-filing time to exploit personal tax brackets. The tax computation of the firm, the related TDS statement and the partner’s books should all tell a consistent story. Distinguish remuneration taxed in the partner’s hands from distribution of already-taxed partnership profit; the labels and tax consequences differ. Preserve contemporaneous board or partner minutes evidencing active involvement.
Practitioner checklist
- Verify executing and effective dates of the partnership deed.
- Confirm which partners actively work in the business.
- Build the tax-defined book-profit bridge before applying limits.
- Reconcile aggregate remuneration cap to partner-wise credit.
- Test partner interest and withholding separately.
Official sources and statutory trail
- Income-tax Department: section 40(b), FY 2025-26
- Income-tax Act, 2025, consolidated with Finance Act 2026
Questions readers ask
Can a sleeping partner receive deductible remuneration?
The special remuneration deduction applies to working partners, not passive partners.
What is the slab threshold for FY 2025–26?
The first ₹6 lakh of book profit, using the higher of ₹3 lakh or 90%, followed by 60% on the balance.
Is the ₹13.8-lakh example a guaranteed deduction?
No; deed authority and all other legal tests still restrict it.
What is the interest ceiling?
The statute limits deductible partner interest to 12% simple annual interest, subject to deed conditions.
Is the calculation partner by partner?
The statutory remuneration ceiling is for aggregate remuneration to all qualifying working partners.
What is the new Act equivalent?
Section 35(e) of the Income-tax Act 2025.
Official sources for this update
- Income-tax Department: section 40(b), FY 2025-26
- Income-tax Act, 2025, consolidated with Finance Act 2026
Related reading on Finin2min
Frequently Asked Questions
Source and review trail
Use the current official instrument, portal or regulator publication before acting.
- Primary category
- Income Tax
- Official starting point
- www.indiacode.gov.in
Primary sources & related provisions
Statutory provisions referenced in this guide: