Chapter II-AA - Stock Exchange, Depository and Securities Transactions
Reviewed by CA Nikhil Gupta and Kajri Singh · Last reviewed 30 August 2026
Apply the centralised securities stamp-duty collection mechanism to exchange, off-market, issue, transfer and depository events.
Dedicated Finin2min Summary - Chapter in 2 Minutes
- Section 9A: Instruments chargeable with duty for transactions in stock exchanges and depositories - convert the statutory rule into a classification, value, payer, evidence and State-source control.
- Section 9B: Instruments chargeable with duty for transactions otherwise than through stock exchanges and depositories - convert the statutory rule into a classification, value, payer, evidence and State-source control.
- Apply the centralised securities stamp-duty collection mechanism to exchange, off-market, issue, transfer and depository events.
- Do not quote a rate without the current State/UT Act, Schedule, amendments, surcharge/cess, market-value rule and authorised payment method.
Current statutory text / controlled source map
Section-by-section provision map
| Provision | Subject | Status | Finin2min clause-by-clause decode | Implementation | Evidence/control |
|---|---|---|---|---|---|
| Section 9A | Instruments chargeable with duty for transactions in stock exchanges and depositories | CENTRAL SECURITIES REGIME | Apply the exact exemption, remission or securities collection rule only when every statutory condition is met. | Verify instrument, collecting agent, consideration, domicile State, effective date and Gazette conditions. | Exchange/depository reports, allotment/transfer records, Gazette and remittance evidence. |
| Section 9B | Instruments chargeable with duty for transactions otherwise than through stock exchanges and depositories | CENTRAL SECURITIES REGIME | Apply the exact exemption, remission or securities collection rule only when every statutory condition is met. | Verify instrument, collecting agent, consideration, domicile State, effective date and Gazette conditions. | Exchange/depository reports, allotment/transfer records, Gazette and remittance evidence. |
Finin2min Q&A
What is the first step?
Classify the legal instrument, State/UT and operative rights before applying Chapter II-AA - Stock Exchange, Depository and Securities Transactions.
Can an online rate calculator replace legal classification?
No. Duty depends on the instrument substance, State schedule, market value, amendments, exemptions and related documents.
Is insufficient stamping always fatal?
The consequences and cure depend on the forum, State amendments and statutory impounding/payment process. The original instrument and exact current law must be reviewed.
What should the evidence file contain?
Official legal sources, final instrument, valuation, linked-document matrix, adjudication, e-stamp/franking proof, execution/cancellation evidence, registration record and cure/refund chronology.
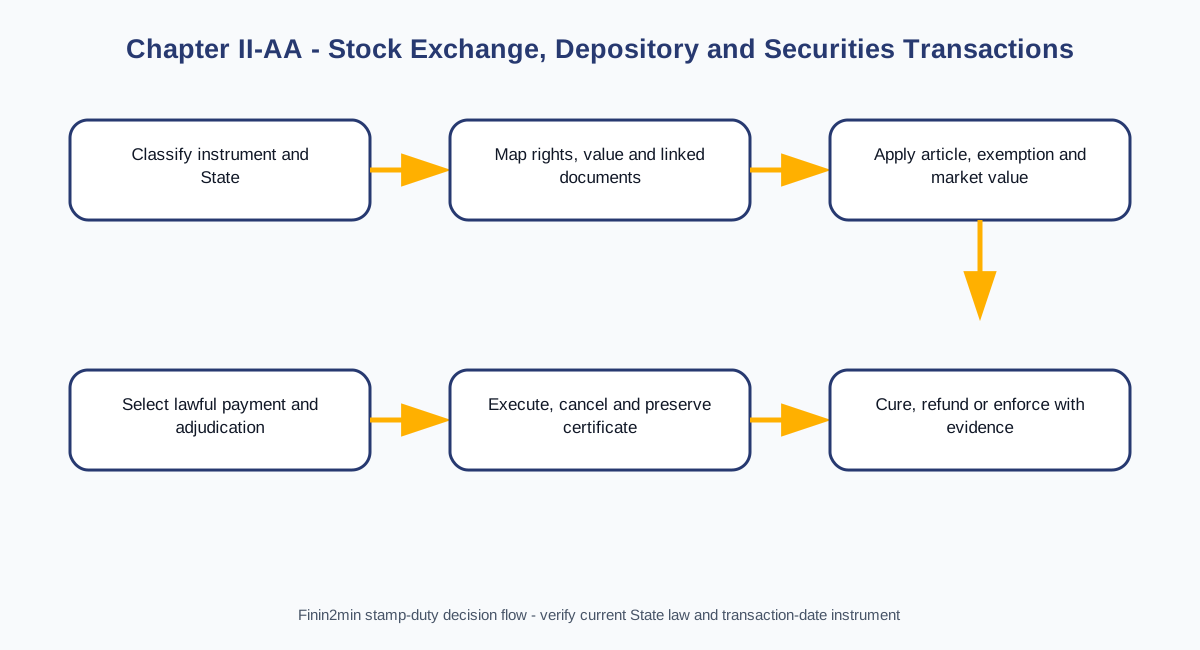
Chapter-specific decision flowchart