57th GST Council Meeting 2026: What the Recommendations Change
The 57th GST Council (8 October 2026) recommended system-led refunds, narrower prosecution and penalties, wider ITC refunds and automated registration. These are recommendations until notified.
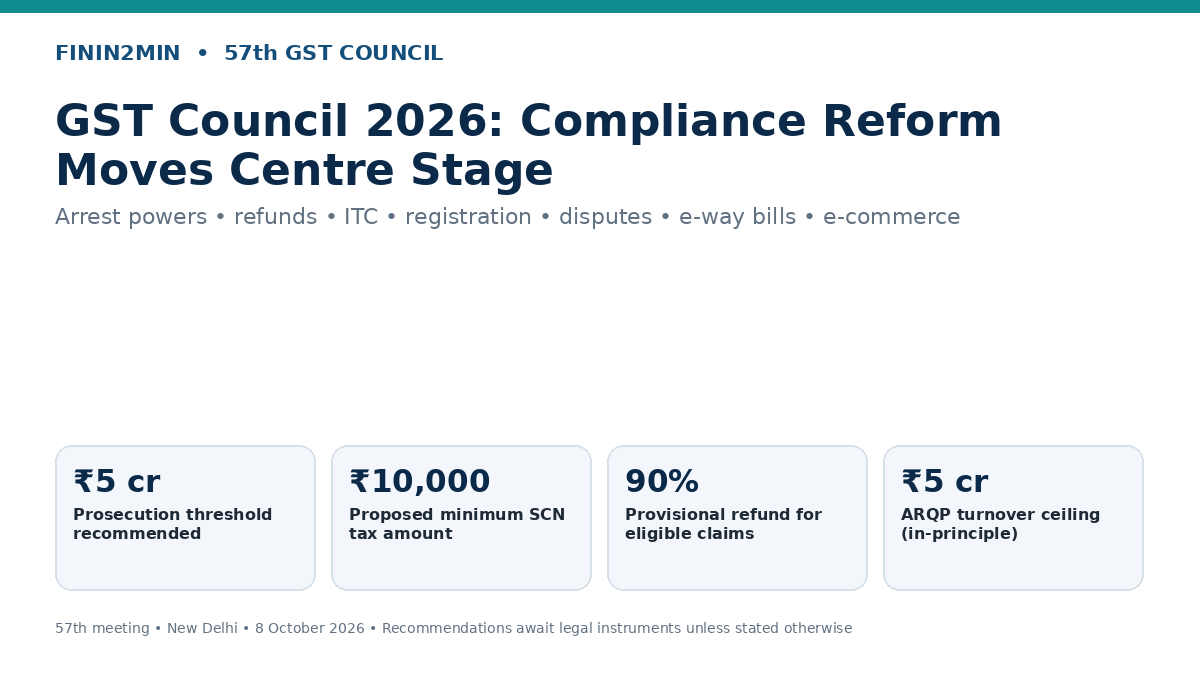
What changed
The 57th GST Council met on 8 October 2026 and recommended changes to refunds, ITC, registration, returns, prosecution and dispute rules.
Why it matters
The package shifts GST from rate rationalisation to administration; none of it is law until the amendments and notifications are issued.
Who is affected
GST-registered businesses, exporters, e-commerce sellers, tax and finance teams.
Action required
Do not change tax treatment yet. Track the CBIC circulars, notifications and GSTN advisories that implement each recommendation. Educational, not tax advice.
The 57th GST Council (8 October 2026) recommended system-led refunds, narrower prosecution and penalties, wider ITC refunds and automated registration. These are recommendations until notified.
- Recommended: withdraw GST arrest powers (omit section 69 CGST); prosecution threshold proposed to rise from Rs 1 crore to Rs 5 crore.
- Refunds: automatic sanction of excess cash-ledger claims, a 10-day acknowledgement window and 90% provisional refund for eligible zero-rated and inverted-duty claims.
- Disputes: Rs 10,000 minimum tax for show-cause notices, section 125 penalty cap cut from Rs 25,000 to Rs 10,000, Rs 40 crore pre-deposit cap in penalty-only appeals.
- Every item is a Council recommendation; it takes effect only through circulars, notifications and law amendments.
View official source →
FinNews is educational and professional reference material, not financial, tax or legal advice. Confirm the current official position from the primary source before acting on any figure, rate, provision or deadline mentioned here.