GST job-work rules allow movement of inputs/capital goods to a job worker without immediate supply treatment when statutory conditions, time limits and records are satisfied. The principal remains responsible for tracking goods and the eventual return/supply route.
Finin2min takeaway
- Classify before computing.
- Use the law/regulation in force for the actual transaction or process date.
- Separate legal, tax, accounting and cash-flow conclusions.
- Reconcile every material conclusion to evidence and the filed output.
1. Overview — what exactly are we analysing?
GST job-work rules allow movement of inputs/capital goods to a job worker without immediate supply treatment when statutory conditions, time limits and records are satisfied. The principal remains responsible for tracking goods and the eventual return/supply route.
This version focuses on mechanics, computation, evidence and worked examples. For Job Work: Return Reporting, Reconciliation and Worked Example, the objective is not to produce a one-line rate or checklist answer. The objective is to make the position reproducible: another reviewer should be able to identify the legal event, apply the current rule, rebuild the calculation and trace the result into the relevant return, form, register, financial statement or board paper.
What makes this topic difficult?
For Job Work: Return Reporting, Reconciliation and Worked Example, the difficult part is linking supply mapping to place/time/value and then proving the result through job-work agreement. A commercially similar transaction can produce a different outcome when the profile-specific facts change. The first failure mode to guard against is using a generic label instead of the legally relevant Job Work classification, so this guide starts with classification and evidence rather than a headline percentage.
2. Current framework — 1 September 2026
Current-position note for Job Work: Return Reporting, Reconciliation and Worked Example. GST analysis should be transaction-specific: identify the supply and the capacity of each party; determine supplier/recipient registrations, place, time and value of supply; apply the relevant charging, reverse-charge, TCS or exemption provision; then reconcile invoices, ledgers and returns. Special notifications and CBIC circulars are applied only where they relate to the topic being analysed; a rate or return label is never used as a substitute for classification.
Maintain challan-based movement and job-worker records for inputs/capital goods sent without payment of tax under the job-work procedure. This point is the first technical checkpoint because a wrong classification at this stage contaminates every later calculation. For Job Work: Return Reporting, Reconciliation and Worked Example, that means the computation file should show the classification step separately from the amount calculation.
Monitor statutory return/supply timelines by item and dispatch date; unresolved aged items can create deemed-supply exposure. In practice, finance teams often discover this issue only during return preparation or diligence; the better control is to resolve it when the transaction is designed. If the fact changes, the team should rerun the conclusion rather than preserve the old answer for convenience.
Distinguish job-work service charges from the principal’s movement of its own goods and apply the correct GST rate to the service. The supporting memo should state the factual assumption that makes the rule relevant and identify the document that proves that assumption. The practical consequence is that the same source fact can produce a different legal, tax, accounting or valuation result when the governing classification or measurement basis changes.
Where goods are supplied directly from a job worker’s premises, confirm the principal has satisfied the declaration/registration conditions applicable to that location. A reviewer should be able to reproduce the conclusion from the source records without relying on a management explanation or a spreadsheet note. This is also where audit defence is won: consistent contracts, registers, bank evidence and filed forms are stronger than a later explanatory note.
Reconcile ITC, challans, e-way bills, job-work statements and inventory quantities so physical goods cannot disappear from the tax trail. Where a contract, ledger, model or business label uses broad terminology, the analysis should translate it into the topic-specific legal, tax, accounting or valuation concept before applying a rate, formula or filing rule. The article therefore treats this as a decision rule, not as a generic caution.
For Job Work: Return Reporting, Reconciliation and Worked Example, where an older circular, precedent, section number or accounting policy is relevant to an earlier period, keep it in the chronology but label it as historical. The current-period analysis should not silently mix two regimes.
3. Detailed mechanics
Computation and evidence focus
This version focuses on mechanics, computation, evidence and worked examples. For Job Work: Return Reporting, Reconciliation and Worked Example, start with the legal event and transaction date, then build a source-to-output bridge. The computation should show opening position, event-specific movement, tax/accounting/regulatory classification, amount recognised, closing position and the exact return/form/register where the outcome is reported.
For Job Work: Return Reporting, Reconciliation and Worked Example, a reviewer should be able to select any material number and trace it backwards to the governing rule and source document. Where the answer is conditional, show both the base case and the fact that would flip the result. This is more useful than a single “applicable/not applicable” conclusion because it tells the finance team what to monitor before filing.
How the mechanics should be documented
For Job Work: Return Reporting, Reconciliation and Worked Example, create a transaction sheet with six columns: legal event, date, party/status, source document, rule relied on and amount/result. This prevents the common problem where the amount is correct but the legal reason is missing, or the legal memo is correct but the underlying amount is pulled from the wrong ledger. Add a seventh column for the person responsible for the next action.
For Job Work: Return Reporting, Reconciliation and Worked Example, create a reconciliation bridge that begins with the source system or legal register and ends with the statutory output. Differences should be explained, not manually forced to zero. In this article, the bridge may need to distinguish contract consideration, taxable value, exemption value, input-tax-credit amount and return-reported value. The working should state the purpose, date and source of each value so a legitimate difference is not mistaken for an error — and an actual mismatch is not hidden as a “valuation difference”.
Practitioner deep dive — five topic-specific checkpoints
Technical checkpoint 1
Maintain challan-based movement and job-worker records for inputs/capital goods sent without payment of tax under the job-work procedure. For Job Work: Return Reporting, Reconciliation and Worked Example, this checkpoint should be resolved before the team moves to "define the exact Job Work event and valuation/reporting date". The working paper should identify the exact fact being tested, the date on which that fact is measured, and the source record used to support it. A useful evidence anchor here is job-work agreement. If that record points in a different direction from the spreadsheet or commercial summary, the legal classification should be reconsidered before any number is carried into a return, model or statutory form.
Computation consequence. The failure mode to test is using a generic label instead of the legally relevant Job Work classification. Do not solve that risk by inserting a balancing figure. Instead, rebuild the bridge from source fact → applicable rule → amount/character → reporting destination. For Job Work: Return Reporting, Reconciliation and Worked Example, the calculation file should preserve both the original source amount and every adjustment, allocation, valuation or classification step applied to it. This lets a reviewer distinguish a genuine legal adjustment from an unexplained spreadsheet difference.
Technical checkpoint 2
Monitor statutory return/supply timelines by item and dispatch date; unresolved aged items can create deemed-supply exposure. For Job Work: Return Reporting, Reconciliation and Worked Example, this checkpoint should be resolved before the team moves to "collect the governing contract, statement and statutory evidence for Job Work". The working paper should identify the exact fact being tested, the date on which that fact is measured, and the source record used to support it. A useful evidence anchor here is delivery challans. If that record points in a different direction from the spreadsheet or commercial summary, the legal classification should be reconsidered before any number is carried into a return, model or statutory form.
Computation consequence. The failure mode to test is using stale law, circulars, scheme terms or dates for Job Work. Do not solve that risk by inserting a balancing figure. Instead, rebuild the bridge from source fact → applicable rule → amount/character → reporting destination. For Job Work: Return Reporting, Reconciliation and Worked Example, the calculation file should preserve both the original source amount and every adjustment, allocation, valuation or classification step applied to it. This lets a reviewer distinguish a genuine legal adjustment from an unexplained spreadsheet difference.
Technical checkpoint 3
Distinguish job-work service charges from the principal’s movement of its own goods and apply the correct GST rate to the service. For Job Work: Return Reporting, Reconciliation and Worked Example, this checkpoint should be resolved before the team moves to "classify the transaction before computing any amount". The working paper should identify the exact fact being tested, the date on which that fact is measured, and the source record used to support it. A useful evidence anchor here is e-way bills. If that record points in a different direction from the spreadsheet or commercial summary, the legal classification should be reconsidered before any number is carried into a return, model or statutory form.
Computation consequence. The failure mode to test is mixing commercial value with statutory, tax, accounting or regulatory value. Do not solve that risk by inserting a balancing figure. Instead, rebuild the bridge from source fact → applicable rule → amount/character → reporting destination. For Job Work: Return Reporting, Reconciliation and Worked Example, the calculation file should preserve both the original source amount and every adjustment, allocation, valuation or classification step applied to it. This lets a reviewer distinguish a genuine legal adjustment from an unexplained spreadsheet difference.
Technical checkpoint 4
Where goods are supplied directly from a job worker’s premises, confirm the principal has satisfied the declaration/registration conditions applicable to that location. For Job Work: Return Reporting, Reconciliation and Worked Example, this checkpoint should be resolved before the team moves to "build the calculation / reconciliation and a second-review check". The working paper should identify the exact fact being tested, the date on which that fact is measured, and the source record used to support it. A useful evidence anchor here is job-worker inventory ledger. If that record points in a different direction from the spreadsheet or commercial summary, the legal classification should be reconsidered before any number is carried into a return, model or statutory form.
Computation consequence. The failure mode to test is losing lot-level, invoice-level, claim-level or facility-level reconciliation for Job Work. Do not solve that risk by inserting a balancing figure. Instead, rebuild the bridge from source fact → applicable rule → amount/character → reporting destination. For Job Work: Return Reporting, Reconciliation and Worked Example, the calculation file should preserve both the original source amount and every adjustment, allocation, valuation or classification step applied to it. This lets a reviewer distinguish a genuine legal adjustment from an unexplained spreadsheet difference.
Technical checkpoint 5
Reconcile ITC, challans, e-way bills, job-work statements and inventory quantities so physical goods cannot disappear from the tax trail. For Job Work: Return Reporting, Reconciliation and Worked Example, this checkpoint should be resolved before the team moves to "map the conclusion to the correct return, register, filing or model output". The working paper should identify the exact fact being tested, the date on which that fact is measured, and the source record used to support it. A useful evidence anchor here is ITC-04/other prescribed reporting. If that record points in a different direction from the spreadsheet or commercial summary, the legal classification should be reconsidered before any number is carried into a return, model or statutory form.
Computation consequence. The failure mode to test is filing or modelling a number that cannot be traced back to source evidence. Do not solve that risk by inserting a balancing figure. Instead, rebuild the bridge from source fact → applicable rule → amount/character → reporting destination. For Job Work: Return Reporting, Reconciliation and Worked Example, the calculation file should preserve both the original source amount and every adjustment, allocation, valuation or classification step applied to it. This lets a reviewer distinguish a genuine legal adjustment from an unexplained spreadsheet difference.
4. Decision workflow
For Job Work: Return Reporting, Reconciliation and Worked Example, each workflow step should have a named evidence owner. Finance may own the ledger, legal may own contract/approval status, tax may own classification/return treatment and secretarial/compliance teams may own statutory registers and filings. The hand-off points should be recorded because an ownerless spreadsheet is not a control.
5. Worked example
Illustrative worked example
Facts. A manufacturer sends 5,000 components to a job worker and receives only 4,700 finished components plus scrap movements.
Analysis. The control should reconcile yield, scrap, returns and any direct supply from the job-worker location; the 300-unit difference cannot be left as a generic “process loss” without evidence.
Finin2min control. This Job Work: Return Reporting, Reconciliation and Worked Example example is deliberately simplified. In a live case, replace every illustrative assumption with the actual dates, amounts, classifications, source documents, approvals and filings relevant to this topic before relying on the result.
The Job Work: Return Reporting, Reconciliation and Worked Example worked example should be accompanied by a sensitivity note. Identify the profile-specific assumption most likely to change the result and show how the conclusion changes if it moves. The sensitivity should use the actual driver in this article — not a generic market variable — so management can monitor the fact that truly changes the legal, tax or model outcome.
6. Scenario analysis
| Scenario | What changes | Reviewer action |
|---|---|---|
| Base case | Core facts align with the intended legal route | Compute and report using the primary rule, with a clear source bridge. |
| Classification changes | One decisive fact changes — instrument, party, project use, resident status or process stage | Re-run the rule before changing only the numeric output. |
| Timing changes | All facts are same but transaction/allotment/default/completion date changes | Re-test the applicable law, rate, deadline and limitation/holding-period consequences. |
| Data mismatch | Commercial report differs from statutory register/return/bank record | Pause filing and reconcile the underlying records first. |
For Job Work: Return Reporting, Reconciliation and Worked Example, scenario analysis is a control for conditional law and model sensitivity rather than forecasting theatre. The scenario table should identify the fact that must be watched, the evidence that proves a change, and the action that follows when the fact crosses from the base case into an exception.
7. Documentation and audit trail
Core evidence file
- job-work agreement
- delivery challans
- e-way bills
- job-worker inventory ledger
- ITC-04/other prescribed reporting
- GSTR/ITC reconciliation
Evidence standards
- Use final signed/executed documents, not only drafts.
- Preserve the version of valuations and models actually approved.
- Keep bank/portal acknowledgements and not just screenshots.
- Reconcile dates across agreement, ledger, register and filing.
- Record reviewer name/date and unresolved assumptions.
- Archive the current primary-source rule relied on.
For high-value or litigated Job Work: Return Reporting, Reconciliation and Worked Example matters, add a chronology and an issues index. The chronology should be factual and date-based; the issues index should state the rule, management position, contrary evidence and remediation owner. This makes future assessment, diligence or dispute work materially faster.
Evidence-to-conclusion matrix for Job Work: Return Reporting, Reconciliation and Worked Example
Use this Job Work: Return Reporting, Reconciliation and Worked Example matrix as a file-index template. It links each source record to a process step and a known failure mode, so evidence is collected for a reason rather than archived as an undifferentiated document dump.
| Evidence | Decision step | Reviewer test | Red flag |
|---|---|---|---|
| job-work agreement | define the exact Job Work event and valuation/reporting date | Reconcile job-work agreement to the working used for define the exact Job Work event and valuation/reporting date; investigate dates, quantities, values and legal status before sign-off. | using a generic label instead of the legally relevant Job Work classification |
| delivery challans | collect the governing contract, statement and statutory evidence for Job Work | Reconcile delivery challans to the working used for collect the governing contract, statement and statutory evidence for Job Work; investigate dates, quantities, values and legal status before sign-off. | using stale law, circulars, scheme terms or dates for Job Work |
| e-way bills | classify the transaction before computing any amount | Reconcile e-way bills to the working used for classify the transaction before computing any amount; investigate dates, quantities, values and legal status before sign-off. | mixing commercial value with statutory, tax, accounting or regulatory value |
| job-worker inventory ledger | build the calculation / reconciliation and a second-review check | Reconcile job-worker inventory ledger to the working used for build the calculation / reconciliation and a second-review check; investigate dates, quantities, values and legal status before sign-off. | losing lot-level, invoice-level, claim-level or facility-level reconciliation for Job Work |
| ITC-04/other prescribed reporting | map the conclusion to the correct return, register, filing or model output | Reconcile ITC-04/other prescribed reporting to the working used for map the conclusion to the correct return, register, filing or model output; investigate dates, quantities, values and legal status before sign-off. | filing or modelling a number that cannot be traced back to source evidence |
| GSTR/ITC reconciliation | archive evidence, assumptions, approvals and post-event monitoring | Reconcile GSTR/ITC reconciliation to the working used for archive evidence, assumptions, approvals and post-event monitoring; investigate dates, quantities, values and legal status before sign-off. | ignoring a later amendment, contractual condition or event that changes the Job Work conclusion |
8. Risk controls and common mistakes
- using a generic label instead of the legally relevant Job Work classification
- using stale law, circulars, scheme terms or dates for Job Work
- mixing commercial value with statutory, tax, accounting or regulatory value
- losing lot-level, invoice-level, claim-level or facility-level reconciliation for Job Work
- filing or modelling a number that cannot be traced back to source evidence
- ignoring a later amendment, contractual condition or event that changes the Job Work conclusion
Most Job Work: Return Reporting, Reconciliation and Worked Example errors are not simple arithmetic errors. They arise when the right arithmetic is applied to the wrong legal bucket, a stale rule is used, a decisive date is missed, or commercial-system data is allowed to overwrite the statutory evidence trail. Controls should therefore target the specific risks listed above rather than merely recalculate the final total.
9. Professional review checklist
- Has supply mapping been resolved using the current framework for the actual transaction/process date?
- Can the conclusion be traced to job-work agreement and delivery challans?
- Has the team separately documented place/time/value and rate or exemption rather than assuming one answers the other?
- Are the dates needed for define the exact Job Work event and valuation/reporting date and collect the governing contract, statement and statutory evidence for Job Work supported by source records?
- Has the specific red flag “using a generic label instead of the legally relevant Job Work classification” been tested and closed?
- Do the working papers explain any difference among contract consideration, taxable value, exemption value, input-tax-credit amount and return-reported value?
- Are the worked-example assumptions clearly separated from the actual Job Work: Return Reporting, Reconciliation and Worked Example fact pattern?
- Has a second reviewer checked the technical conclusion, arithmetic and evidence trail for Job Work: Return Reporting, Reconciliation and Worked Example?
For Job Work: Return Reporting, Reconciliation and Worked Example, a finance expert should review the economics and reconciliation; a tax/legal/secretarial professional should review the governing framework and filing; and the transaction owner should confirm that the factual assumptions used in the memo are actually true. The review is complete only when these perspectives agree on the same dated fact set and unresolved exceptions are explicitly assigned.
Updated analysis: ITC-04 filing frequency, challan tracking and job-work reconciliation
Added and reviewed on 11 October 2026. This section adds the ITC-04 filing frequency, the challan-level movement register and the reconciliation steps to the job-work guide above. Where the two differ, follow the CGST Act, the CGST Rules and the latest notification.
Who files and why the principal is responsible
The reporting obligation relates to the principal sending inputs or capital goods to a job worker and receiving them back or arranging permitted onward supply. The principal is not relieved of inventory control merely because the goods sit at a third-party workshop. The ITC-04 statement is designed to capture movement information from prescribed challans. Start by deciding whether the arrangement is job work on goods belonging to the principal rather than a purchase of completed goods from a vendor. That ownership distinction affects challans, inward credit, documentation and return data.
Turnover determines the period
The amended Rule 45 reporting structure uses aggregate turnover of the immediately preceding financial year. Where it exceeds ₹5 crore, the specified period is ordinarily six months beginning 1 April and 1 October. For other principals, the period is the financial year. The usual due point is the 25th day of the month succeeding the specified period, subject to extensions notified by the competent authority. A calendar should record whether the taxpayer is on a half-yearly or annual cycle and any valid notification changing the due date.
The challan is the data backbone
Every outward transfer to a job worker should be linked to the delivery challan particulars required under the GST framework. Capture challan number, date, HSN, quantity, value where relevant, job-worker GSTIN/address, receipt confirmation, and whether the goods were returned or sent to another worker. A purchase-order reference alone may not reveal the correct goods-movement sequence. When the movement occurs directly from a supplier to a job worker, retain a trail connecting the vendor invoice, delivery documents, principal’s books and worker acknowledgement.
Reconcile opening, sent, returned and pending goods
Maintain a stock movement register with beginning goods at worker, transfers made during the period, movement to another job worker, goods received back, and permitted outward supplies. The closing quantity should reconcile to the job-worker balance supported by confirmations. If a batch is split into consumed, scrapped and returned material, record those dispositions separately. Do not net off unrelated goods or collapse an old pending batch into an adjustment line simply to make ITC-04 totals equal the financial ledger. The statutory time limits for return or supply also require a dated tracking column.
Watch the underlying one-year and three-year rules
The CGST Act’s job-work structure ordinarily gives different time limits for inputs and capital goods to be brought back or supplied from the job worker, with exceptions for specified tools and equipment. The consequences of not returning or supplying within the permitted period can include deemed supply treatment and tax exposure. Filing ITC-04 is not itself proof that these underlying conditions were met. Keep a transaction-level ageing report showing the original dispatch date, relevant goods category and physical position; investigate approaching deadlines before they turn into assessments.
What to do with scrap, direct supply and multiple workers
A piece of metal sent for machining may return as a finished component with scrap generated at the worker’s premises. Depending on the worker’s registration and the statutory rules, scrap supply can follow distinct invoicing arrangements. Also identify whether goods are supplied directly from a worker’s premises and whether the principal has the required declarations or additional-place treatment where necessary. A multi-worker process should contain chain-of-custody evidence at each movement, rather than only the initial dispatch and eventual return.
ITC-04 and the rest of the GST returns
The principal’s input tax credit is assessed under the substantive GST credit conditions. ITC-04 records movement information; it does not by itself grant, reverse or validate an input credit. GSTR-1 records outward supplies, GSTR-3B carries liability and credit positions, and other evidence may be necessary for deemed supplies or disposals. Map every ITC-04 line to supporting inventory events and recognise any separate invoice or tax treatment in the right return. A return reconciled only by value can still conceal missing quantities.
Review return amendments and defensibility
Before filing, compare the statement extract against job-worker acknowledgements, e-way bills where applicable, material issue slips and opening balances. Identify negative quantities, repeated challan numbers, records with no job-worker master, and movements beyond statutory time limits. If a later adjustment is necessary, preserve the reason, supporting goods documentation and portal trail; do not silently overwrite past period registers. An audit-ready file answers where the goods physically were and why each movement was correctly reported, not merely which button the filer clicked.
Worked Indian example
An Indian manufacturer with previous-year aggregate turnover of ₹8.4 crore sends 1,000 castings to job worker A in June, receives 700 processed castings in September, and has 300 awaiting finishing at the half-year end. Its April–September ITC-04 reporting and supporting movement register should retain the outstanding 300 with the original dispatch chronology. If turnover had instead been ₹3.2 crore, the annual specified-period rule would generally apply. Any unreturned goods still require monitoring under the independent statutory job-work return deadlines.
Practitioner action checklist
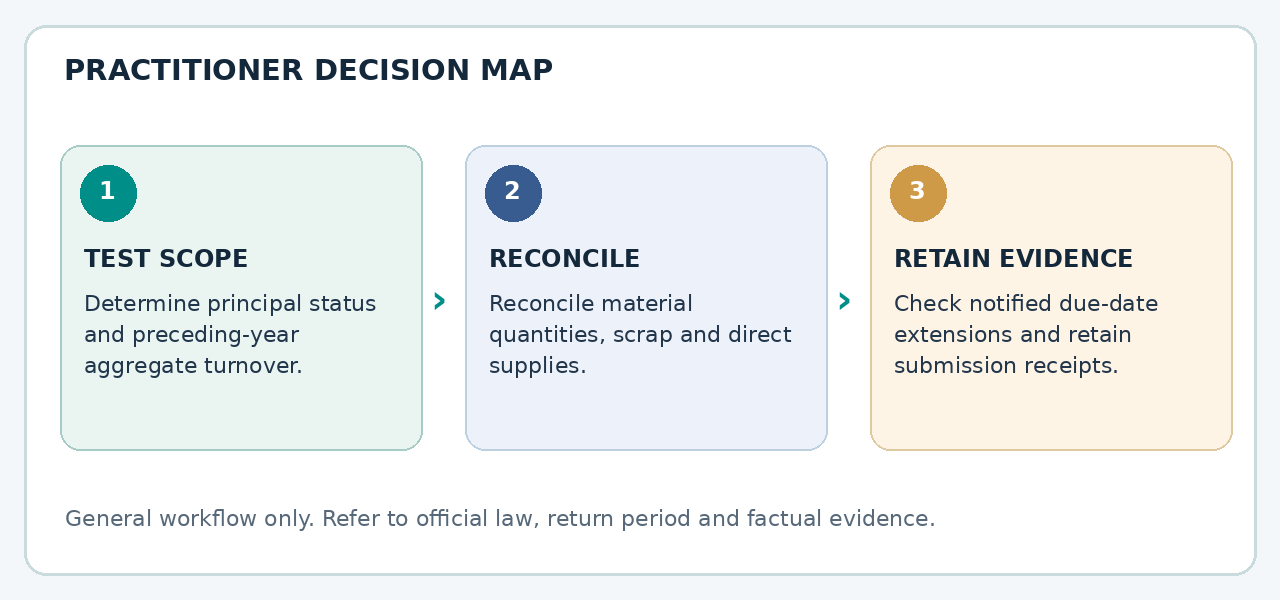
- Determine principal status and preceding-year aggregate turnover.
- Create challan-level movement and job-worker registers.
- Reconcile material quantities, scrap and direct supplies.
- Monitor substantive return/supply time limits independently of ITC-04.
- Check notified due-date extensions and retain submission receipts.
Questions readers ask
Is ITC-04 always quarterly?
No. The amended framework generally prescribes half-yearly or annual reporting based on preceding-year turnover.
Does turnover of exactly ₹5 crore mean half-yearly?
The cited threshold tests whether turnover exceeds ₹5 crore; check the operative wording.
Is an ITC-04 filing proof of ITC entitlement?
No. Tax-credit eligibility is a separate legal assessment.
Can goods go from one job worker to another?
The job-work law provides controlled movement routes; each transfer must be documented.
Are the due dates absolute?
Check any valid commissioner-issued extension.
What if goods remain with a job worker too long?
Deemed-supply and related consequences may arise under the substantive rules.
Official sources for this update
- CBIC: Central Goods and Services Tax Act, 2017 (PDF updated to 30 September 2020; section 143 on job work; check later amendments)
- CBIC: GST Rules index (CGST Rules, including rule 45 on the job-work statement)
- GST Council: 45th meeting agenda (review of the Form ITC-04 filing requirement)
- GST portal
Related reading on Finin2min
- FORM GST ITC-04: Details of goods/capital goods sent to and received from job workers - Filing and response guide
- ITC-04: GST filing handbook
- Job Work GST: Challans, Time Limits and Return Evidence
- GST Delivery Challan Format: Job Work, Returns and Goods
- E-Way Bill for Job Work Movements
- GST on Scrap Generated from Job Work
10. Frequently asked questions
What is the first question to ask?
Start with supply mapping for Job Work: Return Reporting, Reconciliation and Worked Example. A commercial label is not enough; identify the parties, the profile-specific legal/economic event, the decisive date and the governing regime before calculating or filing anything.
Which law should be cited for a 2026 transaction?
For Job Work: Return Reporting, Reconciliation and Worked Example, GST analysis should be transaction-specific: identify the supply and the capacity of each party; determine supplier/recipient registrations, place, time and value of supply; apply the relevant charging, reverse-charge, TCS or exemption provision; then reconcile invoices, ledgers and returns. Special notifications and CBIC circulars are applied only where they relate to the topic being analysed; a rate or return label is never used as a substitute for classification.
Can I rely only on a broker, ERP, portal or consultant report?
No. For Job Work: Return Reporting, Reconciliation and Worked Example, secondary reports are useful working evidence, but the final position should reconcile to the profile-specific source file — including job-work agreement, delivery challans — and to the current primary-source rule.
What if two values are different?
For Job Work: Return Reporting, Reconciliation and Worked Example, do not force them to match. First identify whether they answer different questions. In this pillar, the relevant bridge may involve contract consideration, taxable value, exemption value, input-tax-credit amount and return-reported value. Label each value by purpose, valuation date and source, then document why the difference is legitimate or what correction is required.
What is the biggest practical error?
using a generic label instead of the legally relevant Job Work classification. The remedy is to resolve the classification and evidence before filing or closing.
How should I prepare for scrutiny or diligence?
For Job Work: Return Reporting, Reconciliation and Worked Example, maintain a dated technical memo and a file index that includes job-work agreement, delivery challans, e-way bills. Preserve the calculation version, reviewer sign-off and the reconciliation from those source records to the statutory filing, model, board paper or financial statement that uses the conclusion.
Should the example be copied into my return or model?
No. The Job Work: Return Reporting, Reconciliation and Worked Example example demonstrates mechanics only. Replace each assumption with the actual dates, status, amounts and documents in your case, and re-check the current rule before using the result in a return, model, filing or decision memo.
When should the analysis be refreshed?
Refresh the Job Work: Return Reporting, Reconciliation and Worked Example analysis whenever a fact affecting supply mapping, place/time/value or rate or exemption changes, or when the applicable law/regulation, approval status, transaction date or source evidence is updated.
11. Primary sources and validation basis
This article is anchored to primary/regulator material. Always check later amendments, notifications, circulars and transaction-specific facts before acting.
Disclaimer: This Job Work: Return Reporting, Reconciliation and Worked Example guide is for general educational information and does not constitute legal, tax, accounting, investment or financial advice. Transaction-specific positions may differ based on facts, dates, jurisdiction, documentation and later amendments. Obtain professional advice before acting.