Home Loans
Floating Home-Loan Reset in 2026: EMI, Tenure and the Real Interest Bill
By CA Nikhil Gupta · Reviewed by CA Nikhil Gupta · Published 8 June 2026 · about 6 minute read
📄 Download the PDF edition (free sign-in)
Finin2min 2-minute summary
When a floating mortgage rate changes, a familiar EMI can hide a dramatically different repayment term. The borrower needs to compare the revised EMI, maturity date and total remaining interest on the same outstanding principal. RBI requires prescribed choices and communication for covered EMI-based floating-rate personal loans, but a change in the repo rate does not mean that every account will reset instantly.
Why the loan balance matters more than the headline rate
The true starting point is the unpaid principal on the date the lender reprices the account. An original sanction for ₹60 lakh is not the amount on which interest is now charged if years of principal repayments have already been credited. Retrieve the amortisation schedule and find the loan balance, benchmark, contractual spread, next reset date and remaining instalments. Recalculate from that point forward, rather than comparing two fresh loans with different opening balances.
An EMI loan uses a reducing principal balance, but the economics can still be painful when the remaining tenure is long. In early years, much of the instalment pays interest; later it increasingly pays principal. A reset at the wrong time may therefore add years to a loan when the monthly instalment is held unchanged.
RBI borrower options and what the letter should disclose
RBI’s August 2023 framework covers EMI-based floating-rate personal loans, including housing loans within scope. The lender should communicate the impact of rate resets and offer defined choices: a higher instalment, tenor extension, or a combination. Switching to fixed interest is to be offered according to the lender’s board-approved policy; the frequency and any applicable charges must be disclosed. Full and part-prepayment are further alternatives subject to the applicable rules.
The right to an option is not a promise of an attractive fixed rate or an unlimited extension. Lenders must prevent negative amortisation, where the instalment is insufficient even to cover interest and the principal grows. A borrower who only receives a generic SMS stating the new interest rate should ask for the actual revised repayment schedule.
Why the repo-rate headline and your loan can disagree
A floating mortgage can reference an external benchmark such as the repo rate or another contractually permitted benchmark. The interest charged may include a spread, and the reset interval is a contract term. A central-bank announcement, a benchmark’s publication date and the effective date on an individual account can therefore be three different days. For legacy linked loans, the mechanism may also differ from a newly originated external-benchmark mortgage.
Read the sanction letter to distinguish benchmark changes from a lender’s discretionary spread adjustment. Ask the bank for the basis of any spread revision in writing. Without that distinction, borrowers often assume that a monetary-policy cut has been denied when the account is actually between reset dates, or overlook a contractual factor unrelated to the headline policy rate.
EMI increase versus tenure increase
Holding the number of remaining months constant requires a larger monthly instalment after a rate increase. Keeping EMI unchanged instead defers principal repayment and can add substantial interest; keeping both constant would generally require some other adjustment. It is possible to negotiate a mixed option, for example an affordable EMI increment combined with a moderate tenor extension. The best option is not always the one with the highest theoretical interest saving.
A self-employed household with volatile receipts may rationally prefer a smaller EMI and maintain an emergency reserve. A salaried borrower with robust monthly surplus may prefer a larger EMI that keeps the maturity close to the original date. Compare at least three schedules, including a stress test of another one-percentage-point rise.
Prepayment is useful only when the principal adjustment is confirmed
A lump-sum payment can be credited as an advance instalment unless the borrower and bank clearly process it as part-prepayment to principal. Obtain an acknowledgement, then verify that the principal outstanding falls and the repayment schedule is recalculated. Decide whether the bank should keep EMI approximately unchanged and shorten the tenure, or keep the maturity date and lower EMI. Tenure reduction ordinarily saves more future interest, but it also uses monthly cash that may be needed for essential costs.
Prioritise very expensive card debt and an emergency buffer before using all savings to prepay a mortgage. Tax deductions, where available, only offset a fraction of actual interest and should not be used to justify an otherwise poor borrowing decision.
The three-part repayment stress test
A prudent reset decision is made on more than the next monthly debit. First, test cash-flow resilience: could the family meet the proposed higher EMI after a temporary income interruption, school-fee spike or medical expense? Second, test the lifetime bill: how much further interest is paid if the lender maintains today's EMI and lengthens maturity rather than resetting instalments? Third, test exit flexibility: does occasional part-payment save enough interest while preserving a liquid emergency reserve? For an externally benchmarked loan, the scheduled reset date and contractual spread must be documented before relying on any figure.
A simple worksheet should carry four dates: latest statement date, benchmark observation date, next contractual reset and revised expected maturity. The outstanding principal at the first date becomes the starting balance; all scenarios then use precisely that opening amount. Create a base scenario and a further 50-basis-point increase scenario without suggesting the latter is a forecast. Where the EMI becomes unaffordable, ask the lender for the available term extension or rate-option mechanisms rather than allowing an unintended arrear to accumulate.
A home-loan borrower should also compare proposed refinancing by effective costs rather than nominal interest alone. Add the processing charge, legal or valuation fees, release of original security documents, any differential floating spread and the expected period before the saving exceeds transfer expenses. A marginal headline saving can disappear if the household plans to sell the property shortly. A shorter tenor is valuable only where monthly affordability is genuine.
Documents and complaint route
Maintain the original sanction letter, benchmark/spread clause, rate-change messages, monthly balance statement, revised amortisation tables and every prepayment receipt. Put your calculation and requested choice in one written letter. Ask the lender to confirm the implementation date and any conversion fee for a fixed-rate option.
For a covered bank or other regulated entity, first use its formal grievance channel. If an eligible service complaint is rejected or unresolved after the applicable waiting period, the RBI complaint mechanism may be available. A dispute over loan pricing is different from a complaint that the bank did not apply a rate or borrower instruction according to the agreed terms.
Worked India-specific illustration
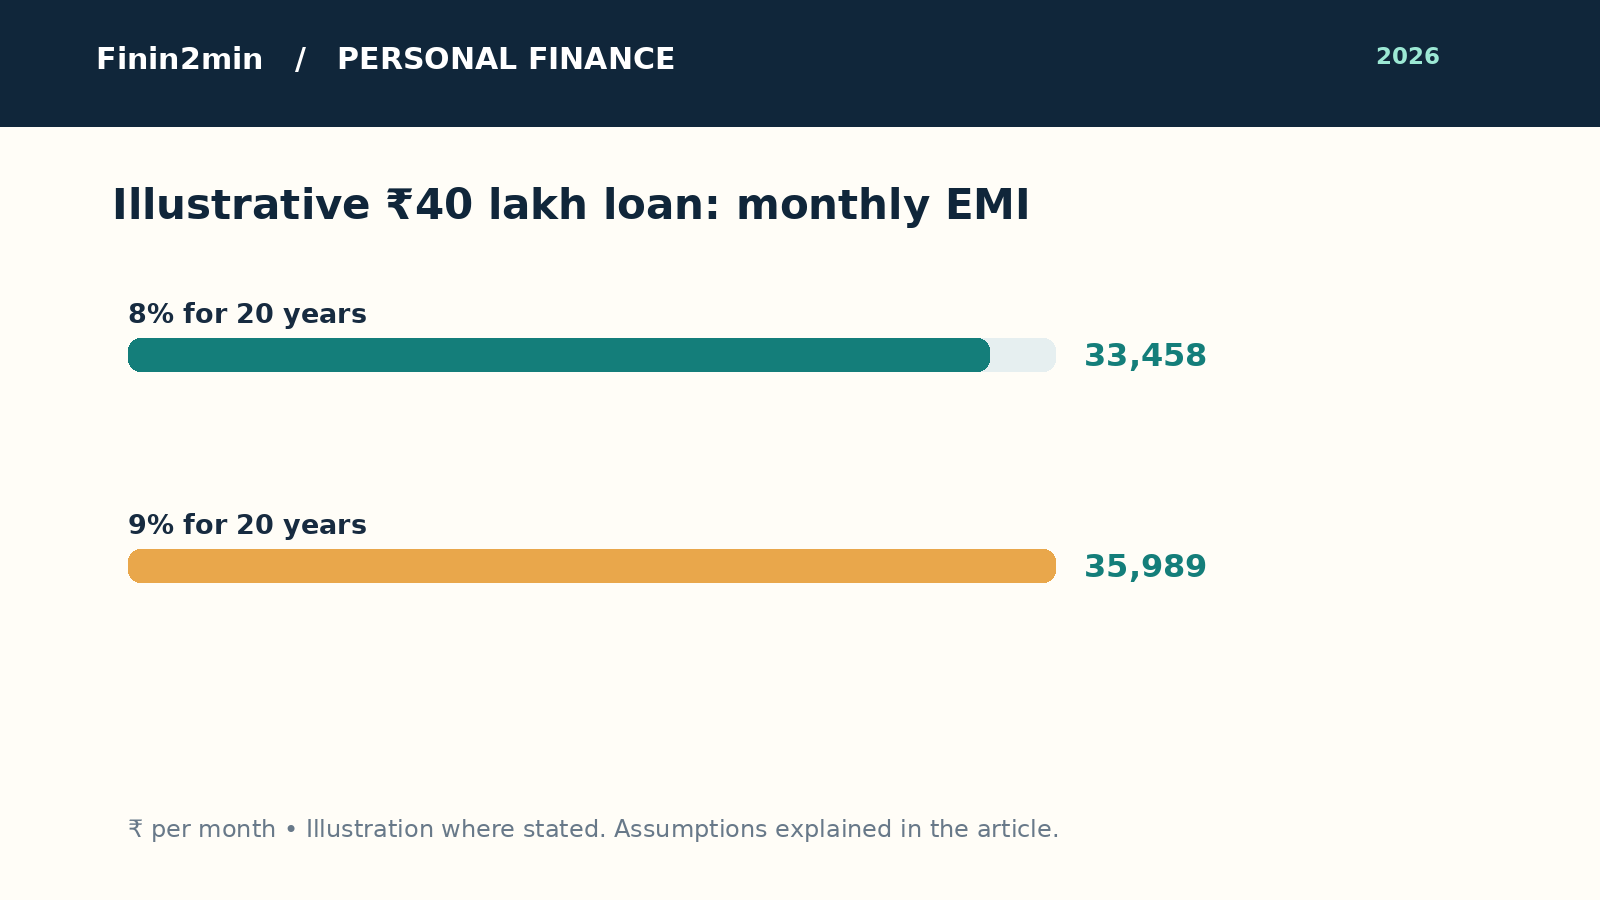
Illustration: ₹40 lakh outstanding, 20 years remaining. At 8% the EMI is approximately ₹33,458; at 9% with the same 20-year term it is about ₹35,989. That ₹2,531 monthly difference compounds across 240 instalments, even before considering a reset on the actual remaining balance. These figures are modelled on monthly reducing balance and exclude charges.
Practical action checklist
- Obtain the exact principal and residual term at the reset date.
- Get the benchmark, spread and next reset date in writing.
- Model three repayment options using the same principal and rate.
- Protect a household emergency fund before prepaying.
- Submit your chosen EMI/tenure instruction and preserve the reply.
- Check the revised schedule after the first affected instalment.
Questions readers ask
Does the repo rate cut reduce my EMI on the same day?
Not necessarily. The contractual benchmark and reset interval determine when a new rate reaches your account.
Can my bank only extend the loan term?
Covered lenders must follow the RBI option and communication framework; ask for all applicable choices.
Is switching to fixed always free?
No. The option and applicable charges depend on the disclosed lender policy and contract.
Which usually saves more after a prepayment?
Keeping EMI and shortening tenure usually saves more interest than stretching the balance across the original term.
Can a lender allow negative amortisation?
The RBI framework directs lenders to prevent a tenor extension that causes negative amortisation.
Official sources
- RBI: Reset of Floating Interest Rate on EMI Based Personal Loans (2023-08-18)
- RBI: Frequently asked questions on floating-rate EMI resets (2025-10-01)
For general financial and legal education only, not individual investment, insurance, credit or legal advice. Examples assume stated rates and terms and are not guaranteed results. Confirm current regulations, provider documents and individual circumstances before acting.