Compliance Calendar and Document-Retention Master
Reviewed by CA Nikhil Gupta and Kajri Singh · Last reviewed 30 August 2026
Event-based and recurring controls, owners, evidence, retention and escalation.
Finin2min Summary — Chapter in 2 Minutes
- Event-based and recurring controls, owners, evidence, retention and escalation.
- Treat the master as a controlled legal register with source and review dates.
- Separate central law, State law, portal practice and contractual allocation.
- Assign owners, escalation and evidence retention.
- Revalidate against Gazette/MCA/India Code before live deployment.
Section-by-section provision map
| Provision | Subject | Legal effect / rule | Implementation | Evidence |
|---|---|---|---|---|
| Trigger | Transaction, event, default or periodic due date | Identify exact law and facts | Create owner and legal gate | Intake record |
| Authority | Partner/designated partner/Registrar/Tribunal/other authority | Test competence and conflicts | Record approval/signature | Resolution/consent/order |
| Instrument | Agreement/form/notice/order/payment evidence | Use current version and State law | Execute, stamp, register and file as applicable | Original and acknowledgement |
| Performance | Milestones/delivery/payment/filing | Track evidence and exceptions | Maker-checker and escalation | Completion dossier |
| Dispute | Breach/remedy/forum/limitation | Preserve and mitigate | Issue notice and forum memo | Legal hold and matter file |
Finin2min clause-by-clause decode
Trigger
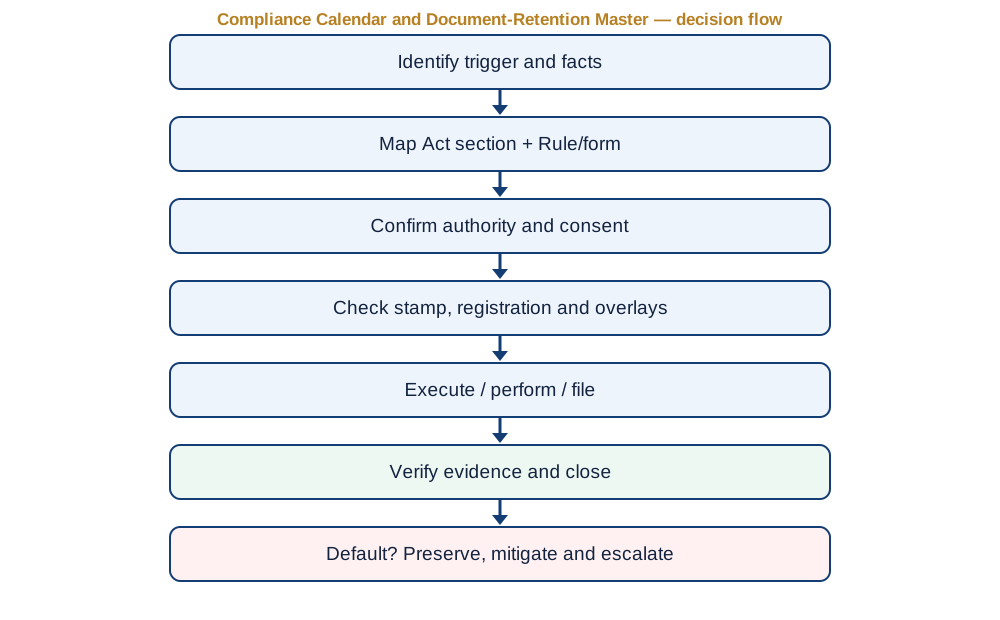
Identify the precise transaction/event and applicable central, State, tax and contractual rules.
Authority
Verify who may decide, execute, certify, file and receive notices.
Execution
Use the current instrument, stamp/registration treatment, delivery method and effective date.
Closure
Verify portal/public records, money/asset movement, stakeholder notices and retained evidence.
Finin2min implementation explanation
Convert the master into an assigned workflow with named owners, source dates, legal gates, evidence standards and maintenance frequency.
Practical examples and calculations
Example A: Practical control
A team proceeds from commercial approval without checking the agreement, prescribed form or State stamp. The correct sequence is legal classification, authority, instrument, filing, evidence and post-closing verification.
Calculation/control: Exposure and timing must be computed from the actual statutory trigger, days of delay, prescribed caps, consideration/contribution, tax base and State duty schedule; retain the calculation sheet and source date.
Practical transaction application
Use the master as a mandatory intake and closing checklist, not as background reading.
Stamp duty and registration alerts
Perform State-specific instrument classification before execution, filing or registration.
Evidence and document-retention checklist
- Current statutory source and amendment log
- Stamped LLP agreement and every amendment
- Partner/designated-partner consent and KYC
- Authority/reserved-matters matrix
- Signed forms and attachments
- SRN, challan and acknowledgement
- Books, bank and tax/GST reconciliation
- Contracts, invoices, delivery and acceptance
- Notices and proof of service
- Valuation/title/security documents
- Legal opinions, orders and appeal records
- Exception, correction and mitigation log
Preserve source instruments, legal research, signed approvals, filings, financial records, notices, delivery proof and final orders.
Performance, delivery and payment controls
Set measurable owners, milestones, maker-checker controls and exception escalation.
Breach, loss, mitigation and remedy framework
Contain loss, preserve evidence, correct public records, assess remedies/penalties and document mitigation.
Limitation and forum controls
Create a matter-specific limitation and forum note at the first notice of dispute or default.
Arbitration and mediation interface
Separate contractual ADR from non-derogable statutory jurisdiction and public-law remedies.
Company, partnership, GST and tax overlays
Apply corporate, partnership, contract, stamp, registration, tax, GST, FEMA, IBC, employment, DPDP and sector-law overlays.
Event and recurring calendar
| Provision | Subject | Legal effect / rule | Implementation | Evidence |
|---|---|---|---|---|
| Incorporation | Name, FiLLiP, agreement/Form 3, tax/bank/GST/licences | Pre-incorporation to post-certificate deadlines | Founder/DP + professional | Permanent core file |
| Partner/designated partner change | Consent/KYC, deed, Form 4 and Form 3 alignment | From effective date/prescribed period | DP/legal/finance | Permanent governance file |
| Registered office/name | Approval, evidence, notice/form, public updates | Before/after effective change | DP/legal/admin | Permanent identity file |
| Monthly/quarterly | Books, bank, partner capital, GST/TDS, contracts, related parties | Close calendar | Finance | Prescribed minimum + litigation hold |
| Annual | Form 8, Form 11, audit applicability, ITR/tax audit, KYC and agreement health check | Statutory/calendar dates | DP/finance/professional | Permanent filings + books period |
| Default/dispute | Legal hold, notice, forum/limitation, insurance and mitigation | Immediate | Legal/DP | Until final closure + retention policy |
| Closure/conversion | Eligibility, creditors, taxes, assets, filings, notices and post-close archive | Project plan | DP/legal/finance | Permanent closure/conversion binder |
Finin2min Q&A
What is the first control before acting?
Identify the exact current Act section, amended Rule/form, LLP agreement clause, authority and State-law instrument requirement.
Can additional fee cure the entire default?
No. It may permit delayed filing, but substantive contravention, false statement, civil penalty, criminal exposure or transaction defects require separate analysis.
Does MCA acceptance prove legal validity?
No. Acceptance is important evidence, but it does not automatically cure authority, stamping, registration, tax, fraud or inaccurate disclosure.
Can the LLP agreement override the Act?
It can structure inter se rights where the Act permits, but cannot override mandatory statutory duties, public filings or regulatory powers.
What should be retained?
Keep signed source documents, approvals, filings and receipts, accounting/tax trail, notices, delivery evidence and the legal source/version relied on.
Can every dispute be arbitrated?
No. Contractual partner/LLP disputes may be arbitrable, while Registrar, adjudication, criminal, Special Court and Tribunal powers remain statutory.
Chapter-specific decision flowchart
Source and review trail
Use the current official instrument, portal or regulator publication before acting. This panel separates the category authority from page-specific references.
- Official starting point
- www.indiacode.gov.in