Finin2min Weekly Brief — September 18, 2026
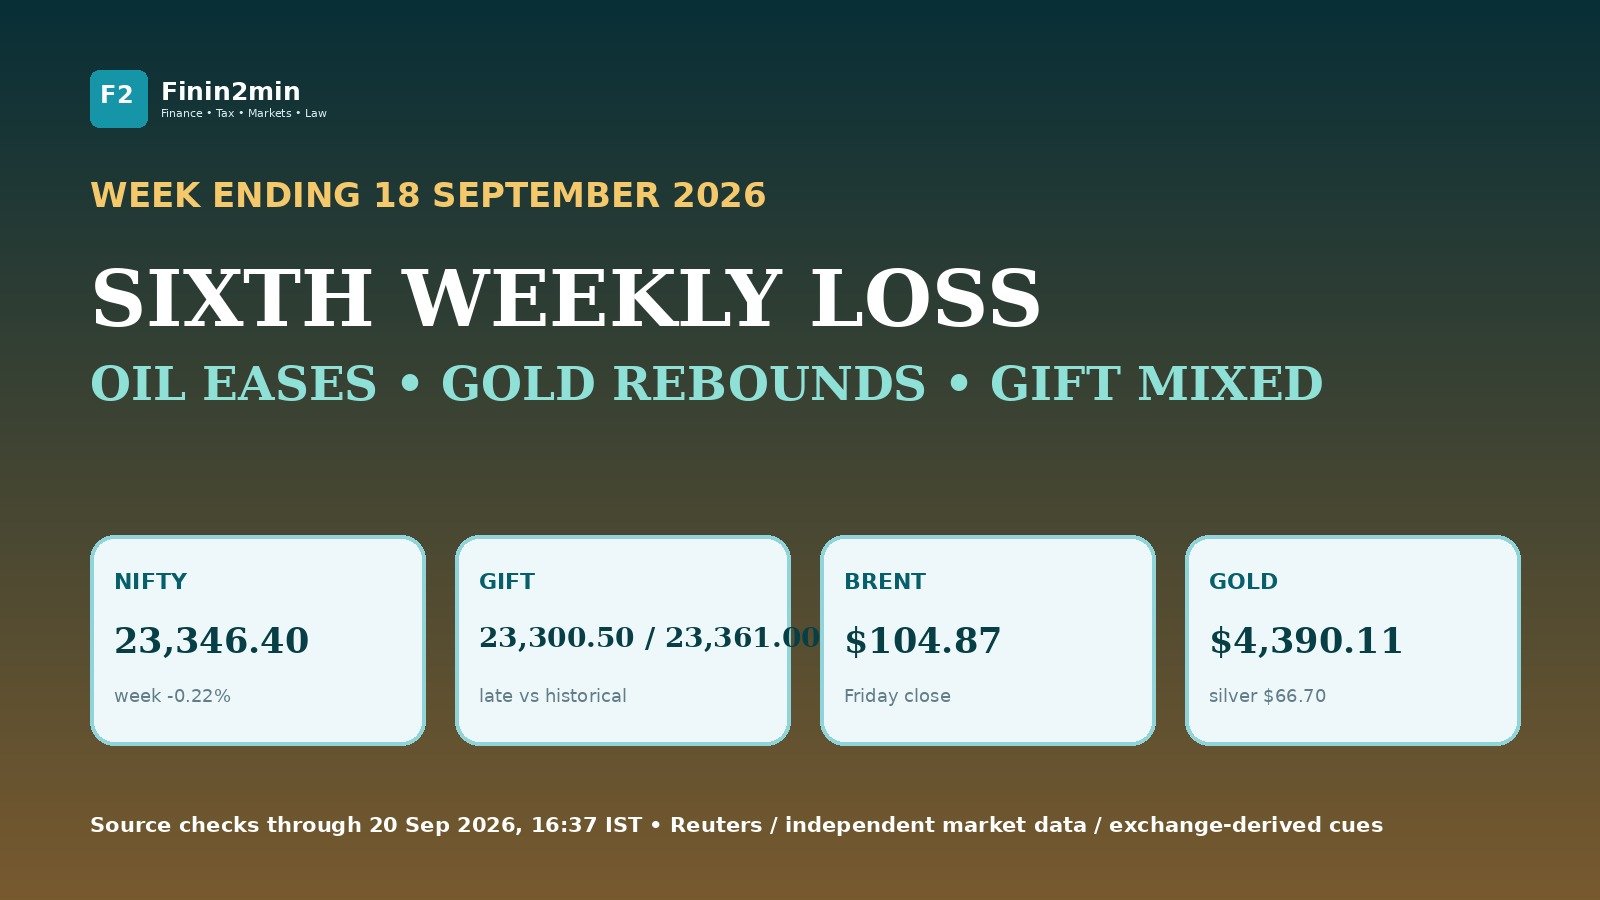
India's sixth weekly loss met late-week oil relief, a gold rebound and a mixed GIFT Nifty cue.
NIFTY 23,346.40 week -0.22% |
GIFT CUE 23,300-23,361 public feeds differ |
BRENT / WTI $104.87 / $100.30 Friday close |
GOLD / SILVER $4,390.11 silver $66.70 |
USD/INR 95.8750 96 defended |
1. Weekly thesis: India fell for a sixth week
Reuters reported Indian equities posted their sixth consecutive weekly decline, the longest since 2020. The Nifty closed at 23,346.40, up +0.33% on Friday but down -0.22% for the week; Sensex closed at 74,294.96, down -0.03% Friday and -0.65% weekly. The week was defined by oil above $100, tighter global rates, FII caution and IPO liquidity absorption. Reuters - India weekly market close
2. Breadth: Friday bounce, weekly weakness
The Friday rise was described as bargain buying after recent selling, not a broad conviction reset. For the week, 10 of 16 key sectors key sectors declined, and small- and mid-cap indices slightly down. Insurance stocks outperformed, while Tata group volatility and IPO liquidity weighed on parts of the market. Reuters - weekly sectors and drivers
3. GIFT Nifty: use a range, not false precision
Latest accessible public GIFT Nifty feeds were not identical. GiftCityNifty showed 23,300.50, down -0.26%, at Sep 19, 02:30 IST. Investing.com's 18 September historical row showed 23,361.00, open 23,333.00, high 23,396.00, low 23,287.00, change +0.12%. Downstox showed a live snapshot of 23,324.50. Finin2min therefore uses a 23,300-23,361 directional cue range for Monday, not a single-point open forecast. GiftCityNifty late-session cue Investing.com GIFT historical row Downstox market snapshot
4. Crude: Friday relief, weekend risk still open
Reuters reported oil prices fell Friday after China urged Iran to help limit Houthi attacks on Saudi oil infrastructure. Brent closed at $104.87/bbl and WTI at $100.30/bbl. The relief came because disruption fears eased, but Reuters weekend reports on Saudi/Gulf market pressure and a Moscow refinery hit by drones keep energy geopolitics active. Reuters - oil Friday close Reuters - Saudi/Gulf weekend risk Reuters - Moscow refinery strike
5. Gold and silver: first weekly gain in four weeks
Gold moved to a one-week high and headed for its first weekly gain in four weeks as easing oil prices reduced inflation worries. Reuters reported spot gold at $4,390.11/oz, up +1.2%, while U.S. gold futures rose +0.6% to $4,424.90. Silver rose +2.3% to $66.70, with platinum and palladium also higher. Reuters - gold and precious metals
6. Rupee: 96/$ remains the RBI line in sand
Reuters reported the rupee declined -0.3% over the week and closed Friday at 95.8750/$. Traders said the RBI appeared to defend the 96/$ threshold, while NSE IPO-linked inflows helped create breathing room after oil retreated. Reuters - rupee weekly close
7. RBI liquidity and funding conditions
RBI liquidity operations were an important weekly theme. Reuters reported an auction-based OMO sale of ₹500 billion, the first such auction-based open-market sale in nine years, while surplus liquidity was around ₹7.4 trillion. For banks and rate-sensitive sectors, this means liquidity is still being disciplined even as equities look for relief. Reuters - RBI OMO and liquidity
8. NSE IPO and primary-market liquidity
The NSE IPO became the week's main domestic liquidity event. Reuters reported the $2.3 billion issue was fully subscribed on day two, with listing expected around the following week. A large OFS can absorb attention and liquidity during a fragile macro week, even when it supports rupee sentiment through inflows. Reuters - NSE IPO
9. Digital payments and direct taxes
Payment economics stayed active after Reuters reported pushback to merchant fees on UPI transactions above the threshold, while fiscal data offered a positive macro offset: India's net direct tax collections rose +13% to ₹12.1 trillion between April 1 and September 17, and gross direct tax collections rose over +15% to ₹14.3 trillion. Reuters - UPI fee pushback Reuters - direct tax collections
10. Global policy and weekend watch
China kept benchmark lending rates unchanged at 3.00% / 3.50%, reflecting limited easing room after the Fed hike. Weekend global watch includes U.S.-China talks on AI, trade and critical minerals, Canada-India trade optimism, Saudi/Gulf volatility and Russia-related energy infrastructure strikes. Reuters - China LPR Reuters - U.S.-China talks Reuters - Canada-India trade
11. Monday decision map
For Monday, the Finin2min screen is: GIFT Nifty range 23,300-23,361; Brent above $100; USD/INR near 96/$; NSE IPO listing/subscription follow-through; FII versus DII flow balance; and weekend geopolitics around Saudi and Russian energy infrastructure. Domestic flows can cushion volatility, but oil and rates still decide the risk regime.
FinNews is educational and professional reference material, not financial, tax or legal advice. Confirm the current official position from the primary source before acting on any figure, rate, provision or deadline mentioned here.