Finin2min Daily Brief | 29 September 2026
Oil retreats, yields stay high: Nifty slips, rupee steadies and compliance deadlines move into focus
Data cut: 30 September 2026, 00:10 IST
Oil retreats, yields stay high: Nifty slips, rupee steadies and compliance deadlines move into focus
India closed another risk-heavy session lower as elevated crude and global yields kept pressure on risk assets. Later in the global day, oil eased, gold rebounded from a seven-week low and GIFT Nifty held near 22,800. For finance teams, the most actionable updates are the CBDT audit-date extension, RBI liquidity signals, bank-strike deferment and fresh SEBI compliance/enforcement items.
2-Minute Summary
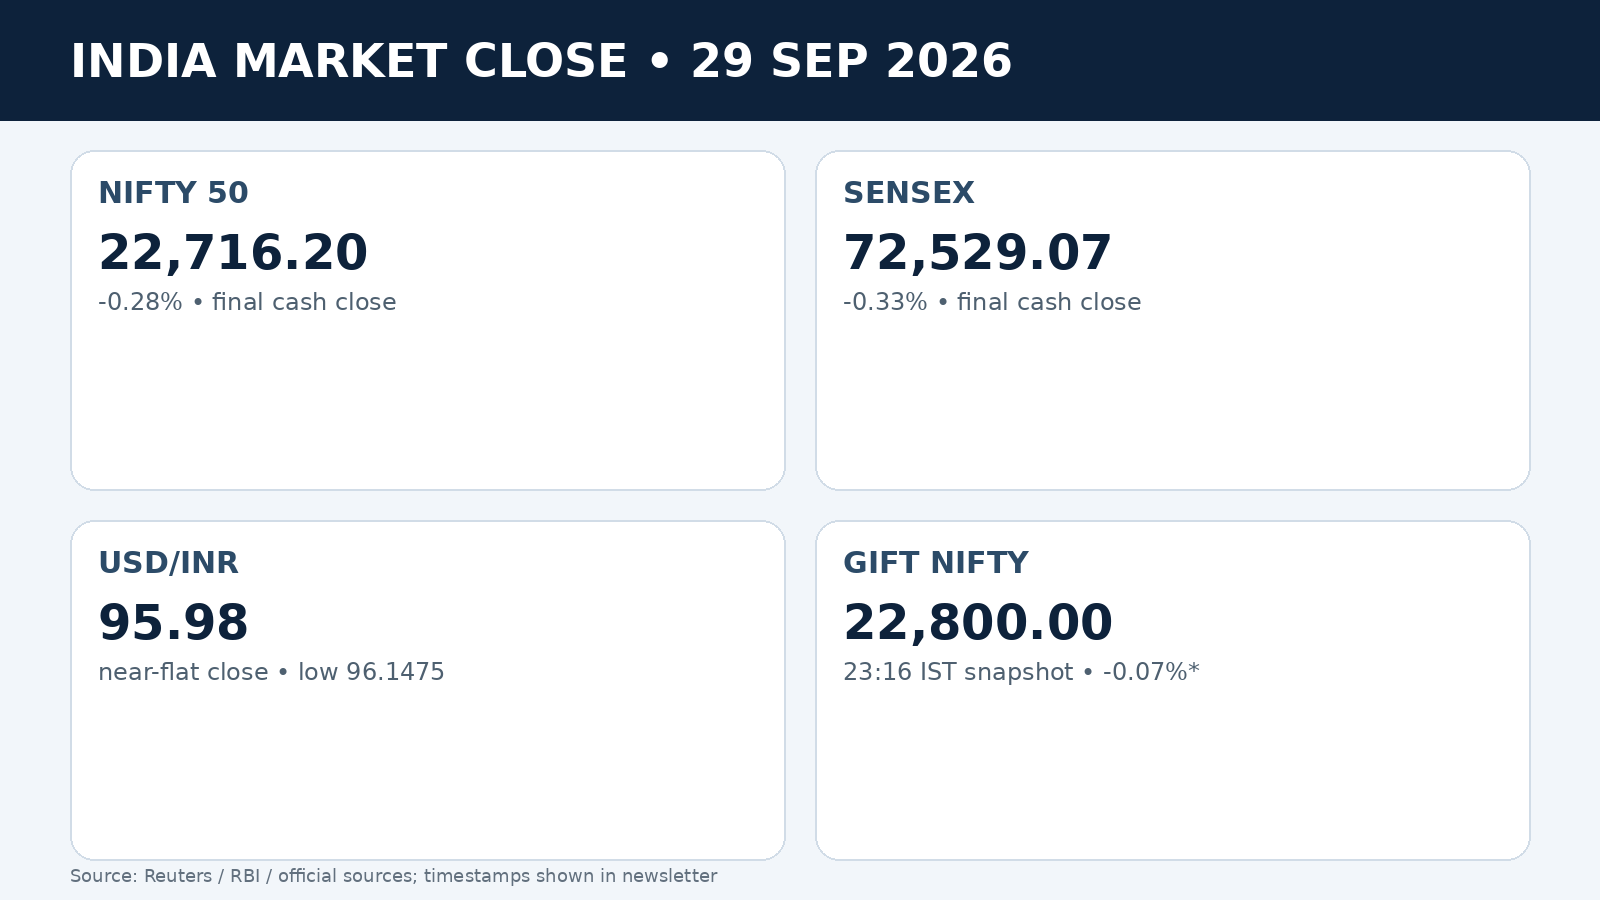
- Nifty 50 ended at 22,716.20 (-0.28%) and Sensex at 72,529.07 (-0.33%); 13 of 16 tracked sectors fell, while mid- and small-cap indices also weakened.
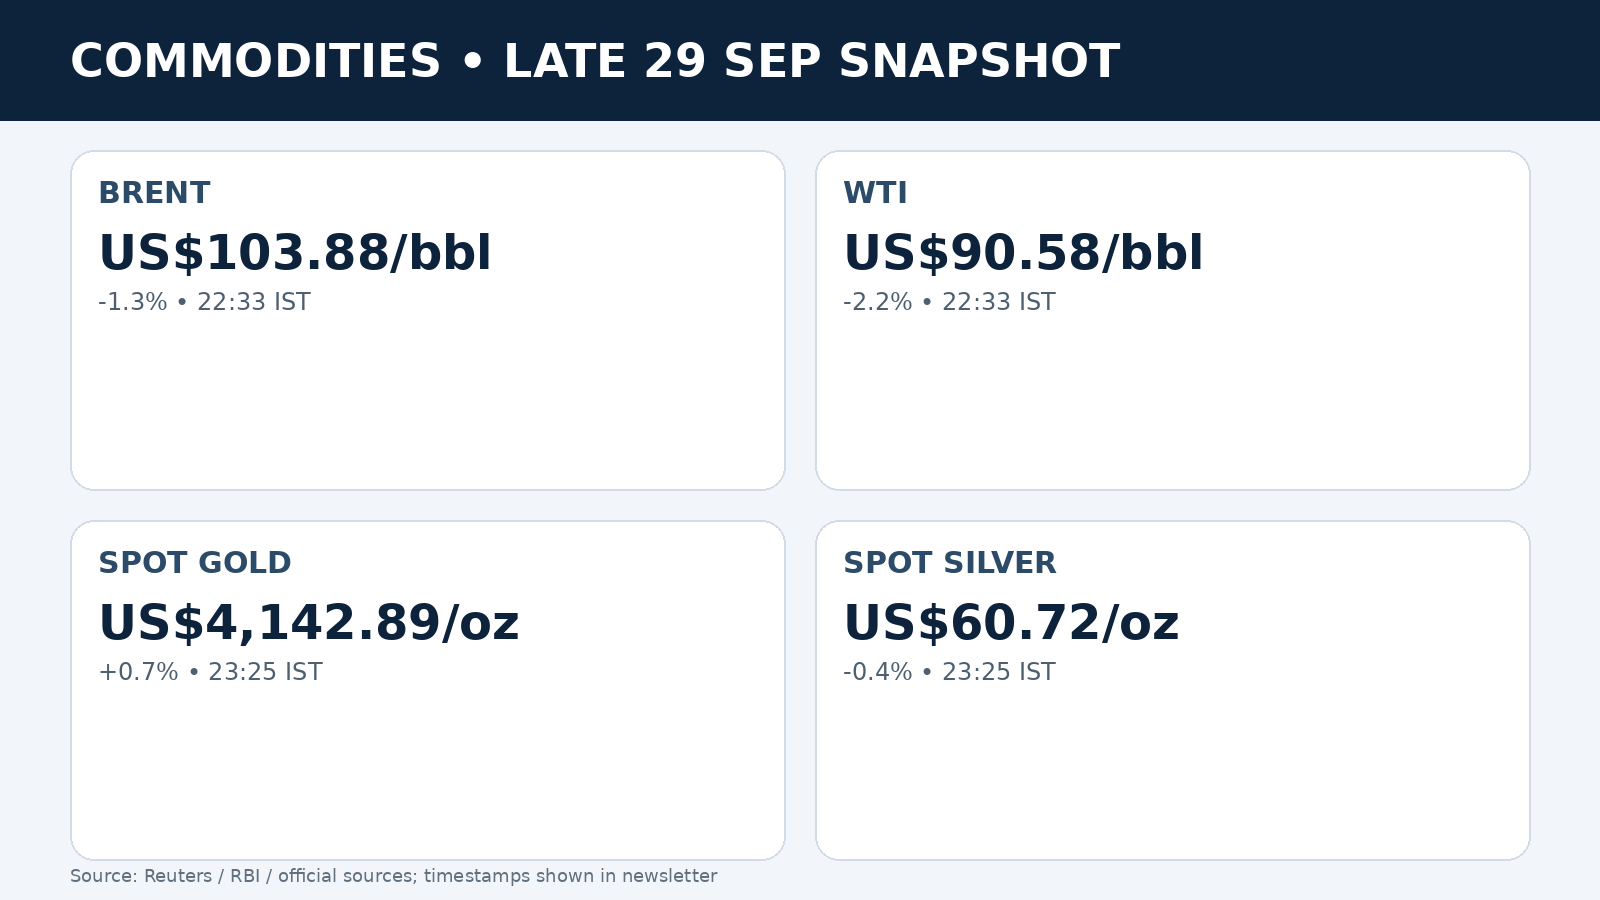
- Brent eased to US$103.88/bbl and WTI to US$90.58/bbl in a late-evening India-time snapshot as regional crude flows showed recovery, but oil remains a major India inflation, FX and margin risk.
- Spot gold recovered to US$4,142.89/oz (+0.7%) after the prior session’s sharp fall; silver was US$60.72/oz (-0.4%).
- GIFT Nifty was 22,800.00 at 23:16 IST, down about 0.07% on the day in the referenced feed. Futures basis means this should not be read as a guaranteed Nifty opening gap.
- The rupee closed near 95.98/$ after an intraday low of 96.1475; likely state-run bank dollar sales helped limit weakness, according to Reuters.
- August IIP grew 8.0% YoY: manufacturing +9.0%, electricity & gas +12.3%. The real economy print remains much stronger than the recent market tape.
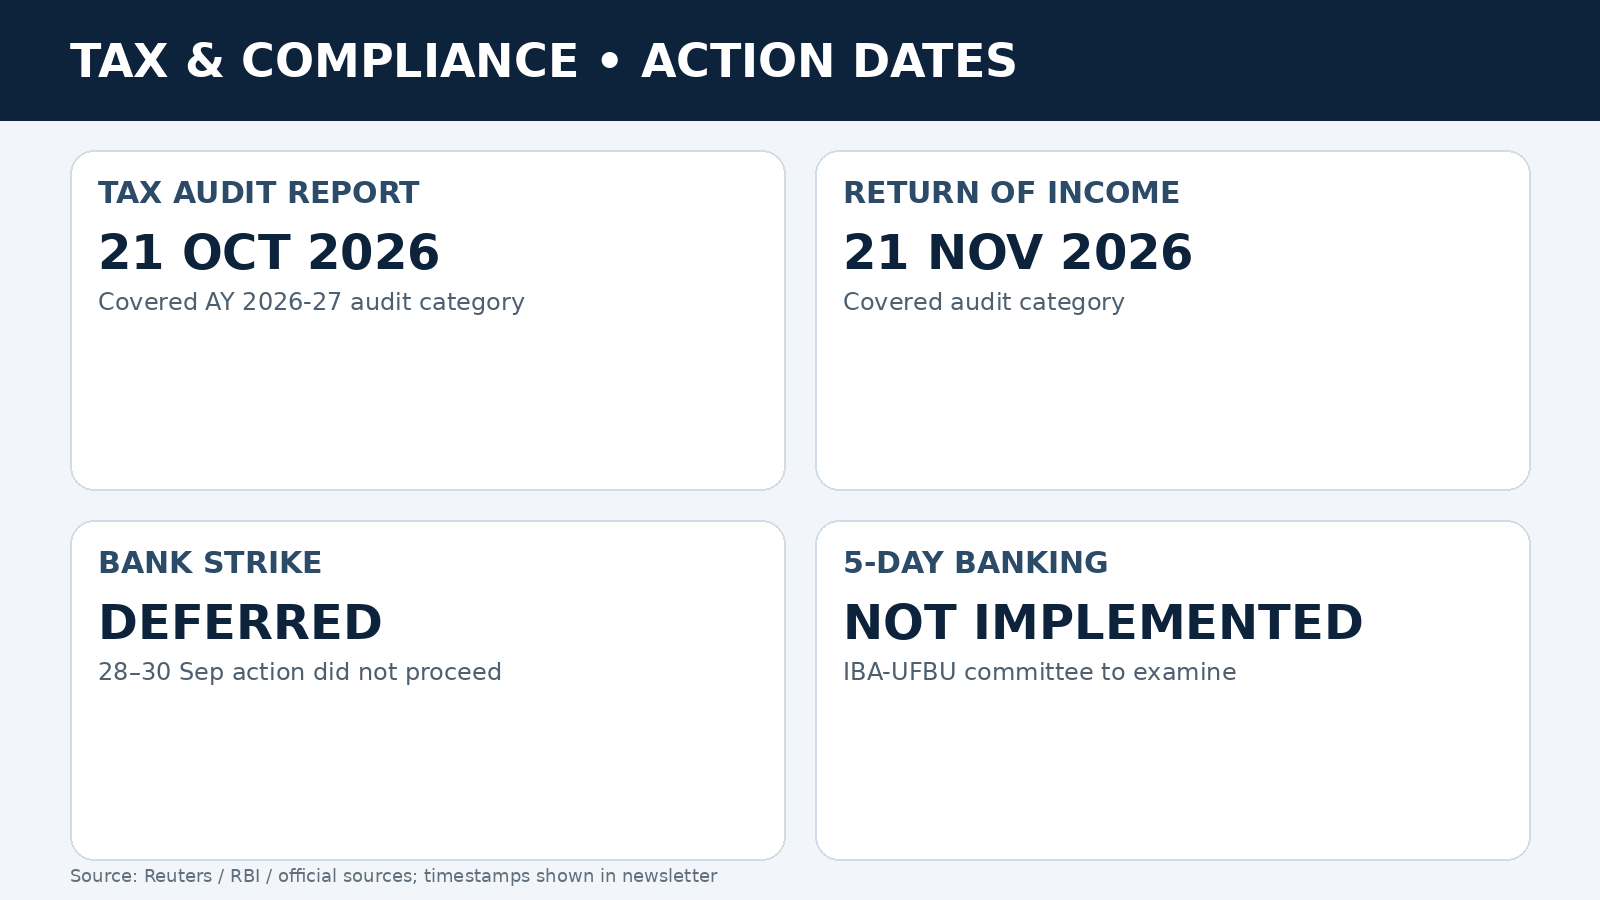
- CBDT announced that, for the covered audit category, the audit-report specified date moves to 21 October 2026 and the related return-of-income due date to 21 November 2026. PIB said the formal order/notification is being issued separately.
- The proposed 28–30 September nationwide bank strike was deferred. Five-day banking has not been implemented; a high-level IBA-UFBU committee is to examine the issue.
Market Dashboard
| Indicator | Level | Move | Timestamp / status |
|---|---|---|---|
| Nifty 50 | 22,716.20 | -0.28% | 29 Sep close |
| Sensex | 72,529.07 | -0.33% | 29 Sep close |
| USD/INR | 95.98 | nearly flat | 29 Sep close |
| GIFT Nifty | 22,800.00 | -0.07%* | 29 Sep 23:16 IST snapshot |
| Brent | US$103.88/bbl | -1.3% | 29 Sep 22:33 IST snapshot |
| WTI | US$90.58/bbl | -2.2% | 29 Sep 22:33 IST snapshot |
| Spot gold | US$4,142.89/oz | +0.7% | 29 Sep 23:25 IST snapshot |
| Spot silver | US$60.72/oz | -0.4% | 29 Sep 23:25 IST snapshot |
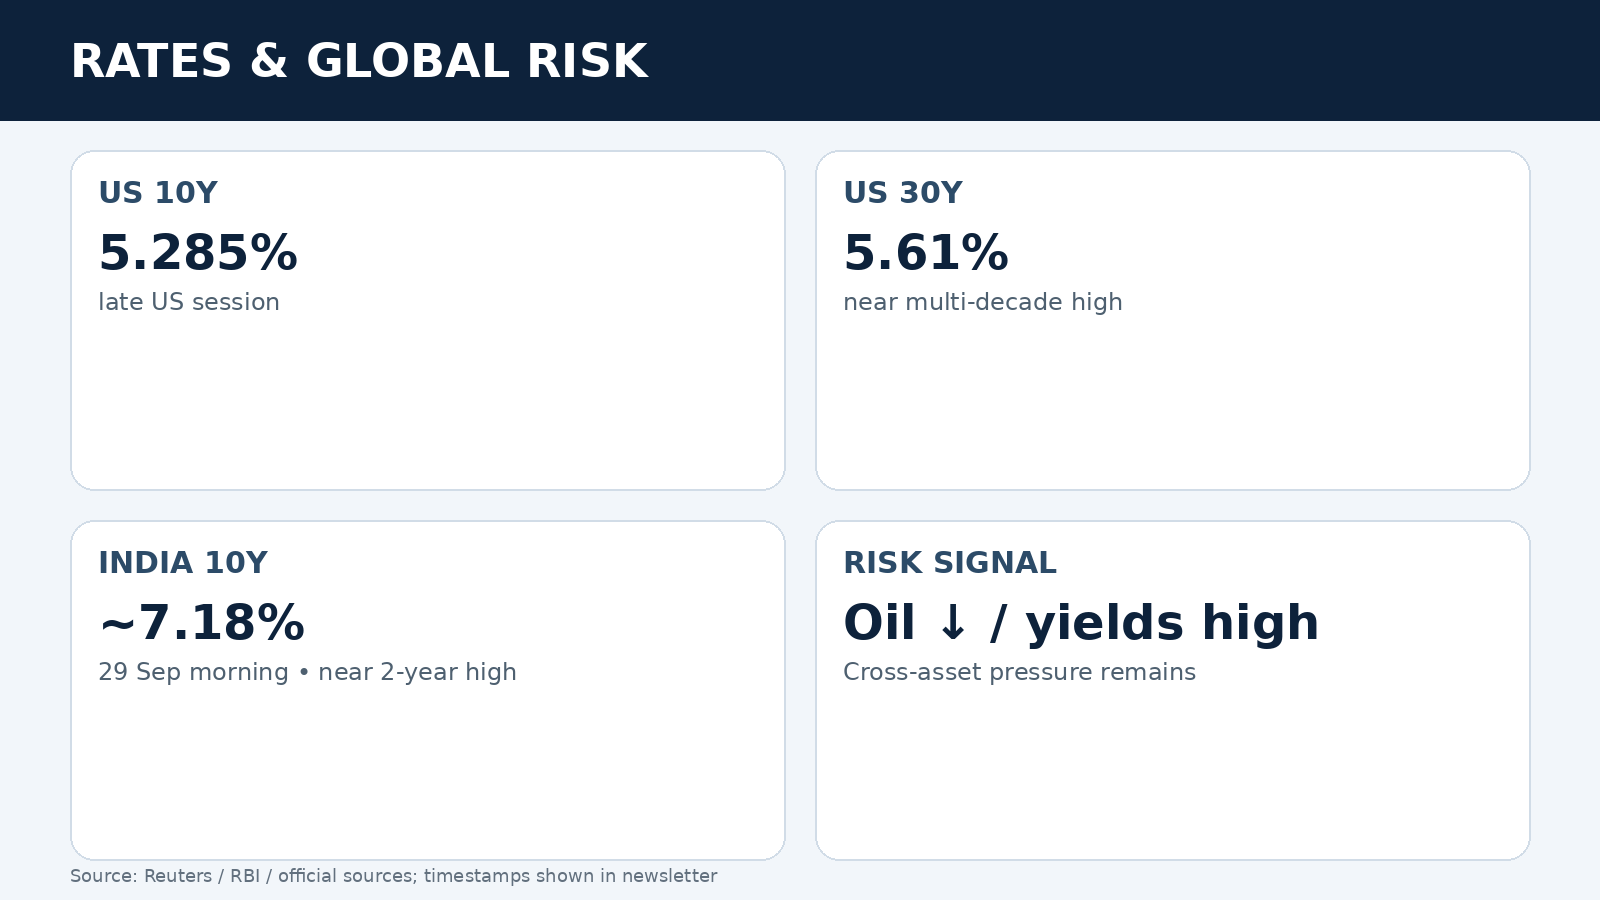
| US 10Y | 5.285% | higher | late US session |
| India 10Y | 7.1797% | slightly lower early | 29 Sep morning |
* GIFT Nifty is a timestamped futures snapshot and is not a guaranteed next-day cash opening signal.
India market close
What happened
Indian benchmarks extended their losing run, but recovered from steeper intraday pressure. Nifty 50 closed at 22,716.20, down 64.05 points or 0.28%, while Sensex ended at 72,529.07, down 242.65 points or 0.33%. The Nifty briefly dropped sharply around the monthly derivatives-expiry closing process before normalising.
Breadth and sectors
Thirteen of 16 major sectors tracked by Reuters finished lower. Information technology fell about 1.5%, banks about 0.4%, while the small-cap and mid-cap benchmarks lost roughly 0.8% and 1.0%, respectively.
Why it matters
India’s near-term sensitivity is unusually cross-asset: crude affects the import bill and inflation, high US yields pressure global risk appetite and the rupee, and persistent foreign selling increases dependence on domestic institutional flows.
Flows, rupee and bonds
Institutional flows
At the package cutoff, the latest clearly verifiable provisional cash-flow print remained 28 September: FIIs -₹5,353.22 crore and DIIs +₹5,189.02 crore. The date is shown explicitly to avoid mixing a prior-day flow with the 29 September market close.
Rupee
USD/INR closed near 95.98 after touching 96.1475 intraday. India imports close to 90% of its crude requirement, so oil remains a direct pressure point. Reuters reported that state-run bank dollar sales, likely on behalf of the RBI, helped cap the fall.
Rates
The India 10-year benchmark was around 7.18% in early trade, close to a two-year high. In the US session, the 10-year Treasury yield was around 5.285% and the 30-year around 5.61%, keeping global duration and valuation pressure elevated.
Crude oil: lower late in the day, still the key India macro risk
Latest
At 1:03 p.m. ET (22:33 IST), Brent was US$103.88/bbl (-1.3%) and WTI US$90.58/bbl (-2.2%).
Driver
Prices fell as investors focused on signs of recovering Middle East exports. Saudi loadings at Yanbu resumed and the East-West pipeline restarted; regional crude exports were reported at their strongest pace since the conflict began.
India transmission
A sustained move lower in crude would ease pressure on the current account, rupee, inflation expectations, fuel-sensitive sectors and corporate margins. A renewed supply shock would reverse that relief quickly.
Reader action
For companies with energy-heavy cost structures or dollar payables, use scenario bands rather than a single oil assumption; treasury teams should align oil, USD/INR and hedge-cost sensitivities.
Gold, silver and the dollar
Gold
Spot gold was US$4,142.89/oz at 1:55 p.m. ET (23:25 IST), up 0.7%. US gold futures settled at US$4,179.70, up 0.3%. The rebound followed a near-4% fall in the previous session.
Silver
Spot silver was US$60.72/oz, down 0.4% in the same Reuters update.
What to watch
The dominant variables remain the dollar, US yields, energy-driven inflation expectations and geopolitical risk. Gold can rise on risk demand but still face pressure when real/nominal yields and the dollar jump sharply.
GIFT Nifty and overnight cue
Latest verified snapshot
GIFT Nifty was 22,800.00 at 23:16:22 IST on 29 September in the referenced global market-data feed, with the daily historical change shown at about -0.07%. Day range in that feed was 22,798–22,845.
Interpretation
This is an offshore futures signal, not a guaranteed next-day Nifty opening level. Contract basis, overnight news, currency moves and the morning pre-open can all change the relationship with the prior cash close.
Data discipline
The package therefore reports the timestamp and futures level directly and does not convert it into a “gap-up/gap-down prediction”.
Global markets: yields remain the constraint
US session
In a late-session Reuters snapshot, Dow was about -0.61%, S&P 500 -0.29% and Nasdaq -0.13%. Technology-linked gains limited the downside, but most S&P sectors were lower.
Rates
US 10-year yields were around 5.285% and 30-year yields around 5.61%, near multi-decade highs. Higher sovereign yields raise discount rates across equities, credit and emerging-market assets.
Europe / world
STOXX 600 was down about 0.15% and the MSCI world gauge about 0.40% in the same global-market report. Australia’s central bank raised rates to a 15-year high, reinforcing the broader higher-for-longer rates narrative.
India economy and RBI
IIP
India’s Index of Industrial Production grew 8.0% year-on-year in August 2026. Manufacturing grew 9.0% and electricity & gas supply 12.3%. This offers a stronger operating-economy backdrop even as financial markets reprice global risks.
Liquidity
Reuters reported that RBI FX operations and liquidity tools had drained roughly US$20 billion equivalent from surplus rupee liquidity. Core liquidity was reported down from ₹14.2 trillion on 4 September to about ₹11.5 trillion.
RBI update
RBI released the report of the Advisory Committee on Ways and Means Advances to State Governments on 29 September. The committee reviewed state-wise WMA limits and related financial accommodation; RBI said the recommendations will be examined.
Tax, legal and compliance desk
Direct tax — high priority
CBDT announced an extension for persons in the covered audit category for AY 2026-27: the audit-report specified date is 21 October 2026 and the related return-of-income due date is 21 November 2026. The PIB release states that a formal order/notification is being issued separately.
Banking operations
The proposed 28–30 September nationwide bank strike was deferred after IBA-UFBU discussions. Branch operations therefore continued. The five-day banking demand is under a high-level committee; no implementation date has been announced.
SEBI
SEBI issued a Master Circular for Debenture Trustees dated 28 September. Compliance teams should map their existing trustee/issuer controls to the latest consolidated text. On 29 September, SEBI also listed a corrigendum to its 28 September final order in the matter of Adani Group Companies for alleged minimum-public-shareholding violation; users relying on the order should read the final order together with the corrigendum.
Status discipline
No proposal, consultation, committee discussion or corrigendum is treated here as a new law or final implementation unless the primary source says so.
30 September watchlist
Markets
Oil direction after the late-session pullback; US Treasury yields; dollar index; GIFT Nifty into its later session; Asian open; USD/INR response; foreign-flow print when available.
Macro
Any follow-through from energy prices into inflation expectations and India bond yields; quarter-end liquidity and treasury behaviour.
Compliance
CBDT formal order/notification following the due-date announcement; any fresh regulator circulars around quarter-end; further communication from IBA/UFBU on five-day banking.
Compliance Calendar
| Date | Obligation / event | Who should care | Status |
|---|---|---|---|
| 21 Oct 2026 | Tax-audit report for covered AY 2026-27 audit category | Taxpayers, tax teams, auditors | CBDT extension announced; formal order/notification stated to follow |
| 21 Nov 2026 | Return of income for same covered audit category | Taxpayers, finance teams | CBDT extension announced |
| 30 Sep onward | Quarter-end regulatory and liquidity watch | CFO, treasury, compliance | Watch |
Disclaimer: General information and education only; not investment, trading, tax, legal or accounting advice. Market prices can change rapidly. Verify applicable law and primary-source text before action.
FinNews is educational and professional reference material, not financial, tax or legal advice. Confirm the current official position from the primary source before acting on any figure, rate, provision or deadline mentioned here.