Finin2min Daily Brief | 24 September 2026
Oil shock deepens: Nifty drops 1.6% as Brent finishes near $106; GIFT Nifty steadies
Oil shock deepens: Nifty drops 1.6% as Brent finishes near $106; GIFT Nifty steadies
India had its weakest session in roughly ten weeks on Thursday. The Nifty 50 closed at 23,063.10 (-1.64%) and the Sensex at 73,580.54 (-1.67%). Reuters reported losses across all 16 major sectors, with banks, financial services and broader mid-cap shares among the main drags. The pressure combined an external shock — sharply higher crude and global bond yields — with domestic concern around a proposed insurance-commission overhaul.
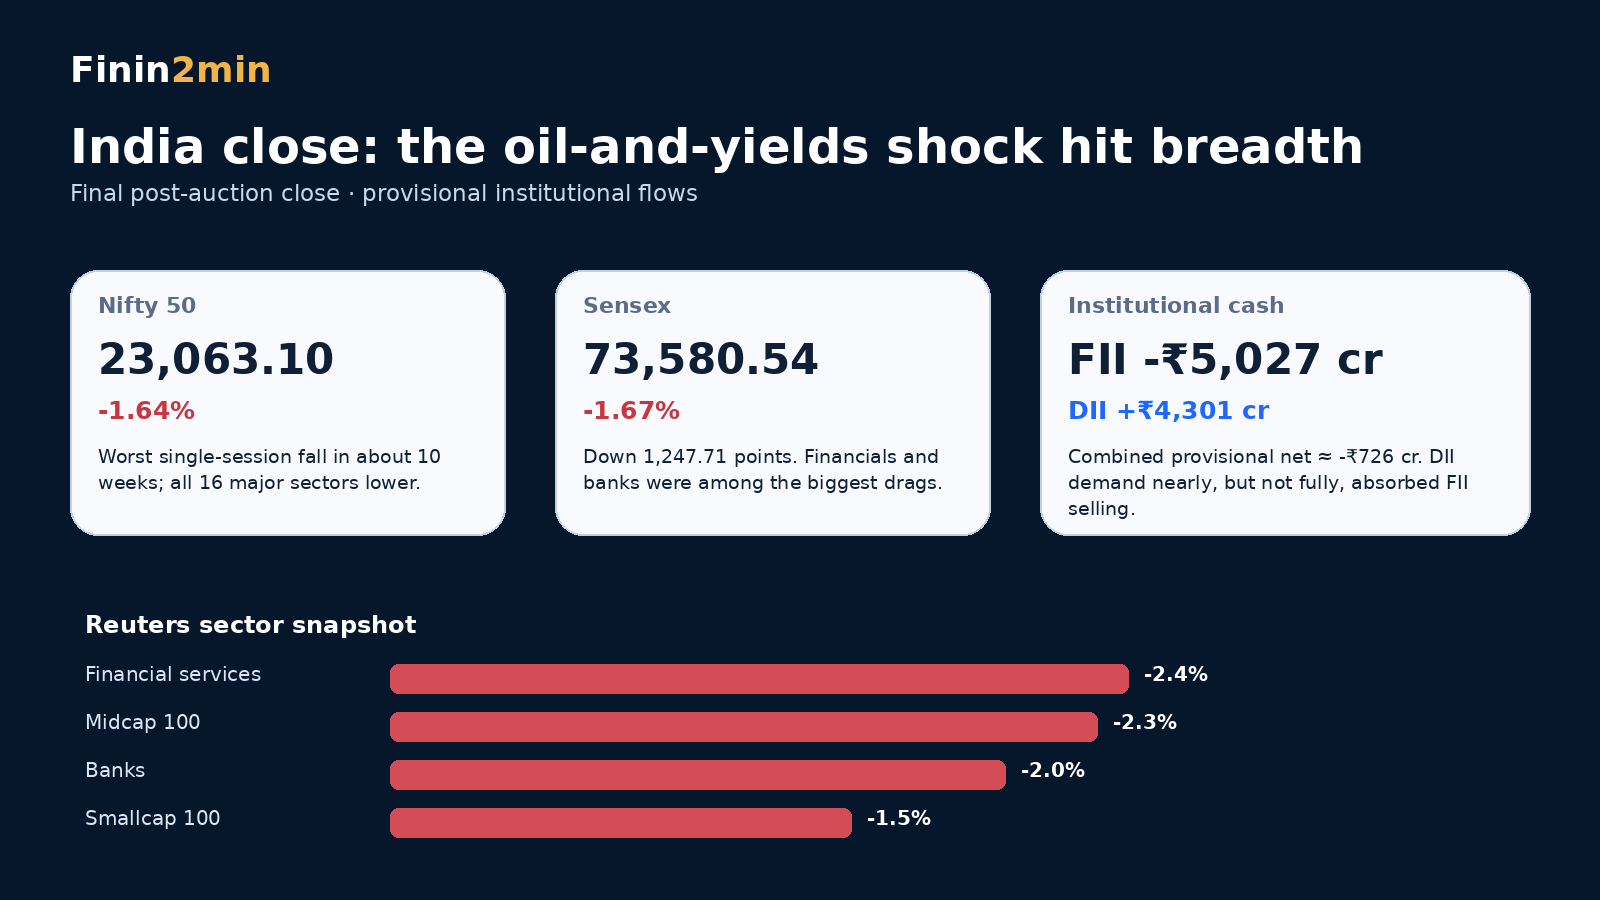
India close: broad risk-off, with financials at the centre
Reuters described 24 September as the worst day for Indian shares in ten weeks. All 16 major sectors finished lower; banks fell about 2%, financial services about 2.4%, Midcap 100 about 2.3% and Smallcap 100 about 1.5%. The final post-auction index closes matter because they remove any ambiguity from pre-auction snapshots.
A domestic catalyst came from a proposed insurance-commission overhaul. The proposal is not a final regulation; the final commercial effect depends on the eventual text. Markets nevertheless repriced insurers, brokers and bank-distribution exposures sharply. National Stock Exchange shares were a counterpoint, rising about 1.8% on their debut according to Reuters.
Institutional flows: DII buying almost absorbed the FII sell-off
Provisional combined cash-market data show FII/FPI purchases of ₹13,111.22 crore and sales of ₹18,138.58 crore, for net selling of ₹5,027.36 crore. DIIs bought ₹18,196.90 crore and sold ₹13,895.72 crore, producing net buying of ₹4,301.18 crore. Combined provisional institutional flow was therefore approximately ₹-726.18 crore. These figures can be revised after custodial confirmation and should not be confused with derivatives positioning.
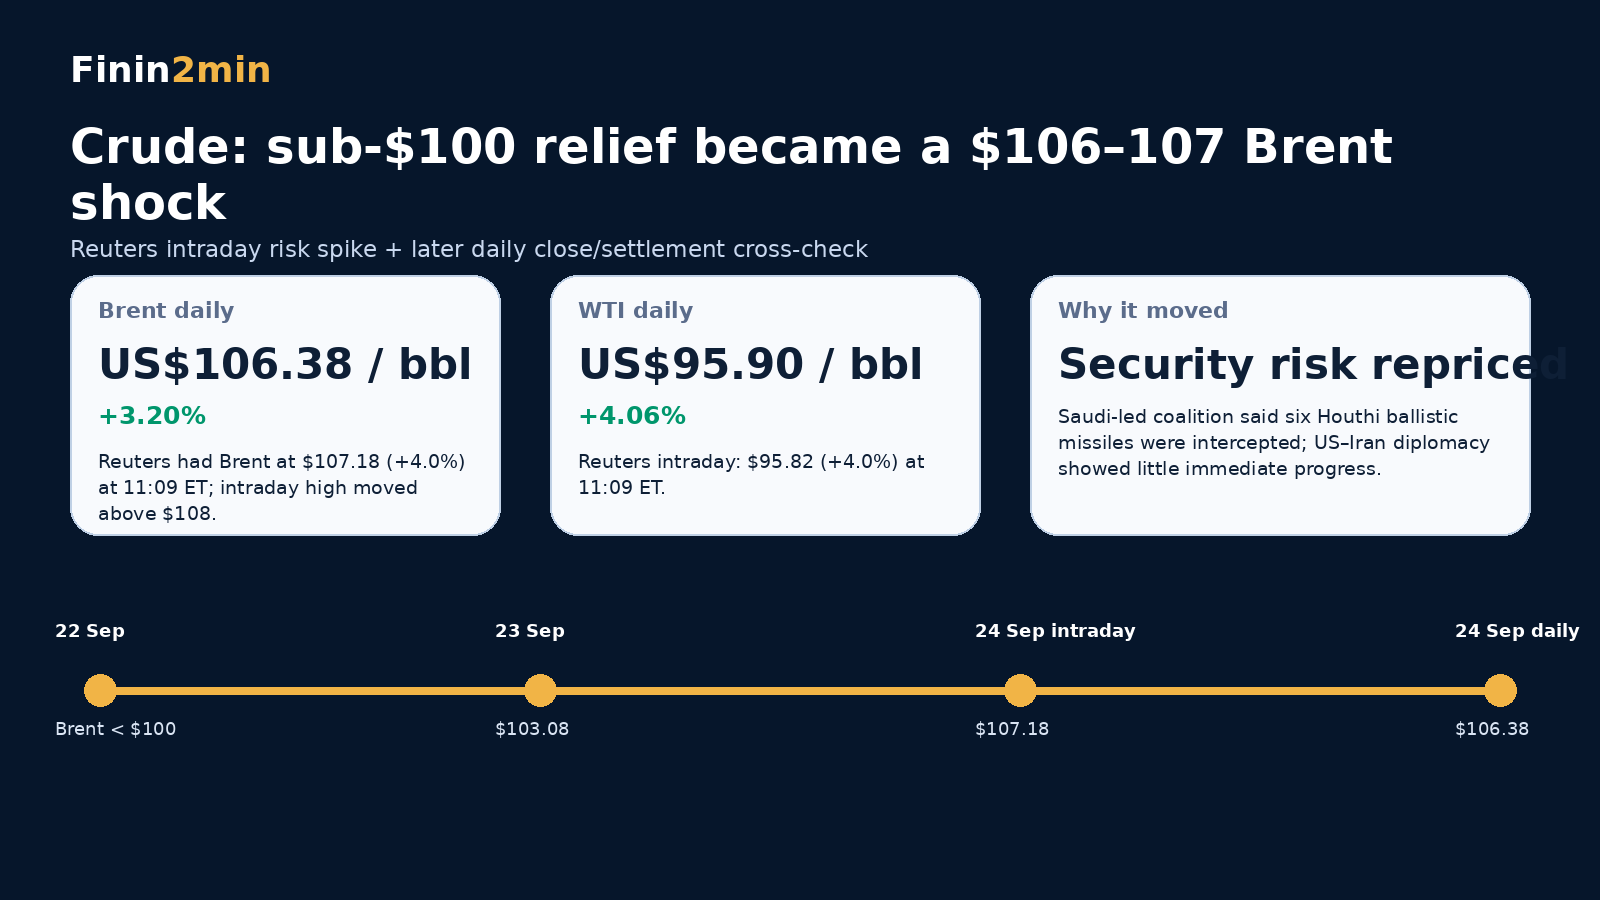
Crude: the macro shock intensified
Reuters reported Brent at $107.18 (+4.0%) and WTI at $95.82 (+4.0%) at 11:09 a.m. EDT after Saudi Arabia said it had intercepted six Houthi ballistic missiles and markets reassessed the outlook for Middle East supply. A later daily market-data cross-check placed Brent around $106.38 (+3.20%) and WTI around $95.90 (+4.06%) for 24 September. The distinction between the Reuters intraday reading and the later daily figure is deliberate.
For India, oil around the mid-$100s can affect imported inflation, refinery dollar demand, the rupee, bond-rate expectations and margins across energy-intensive businesses. The move is especially important because Brent had traded below $100 earlier in the week.
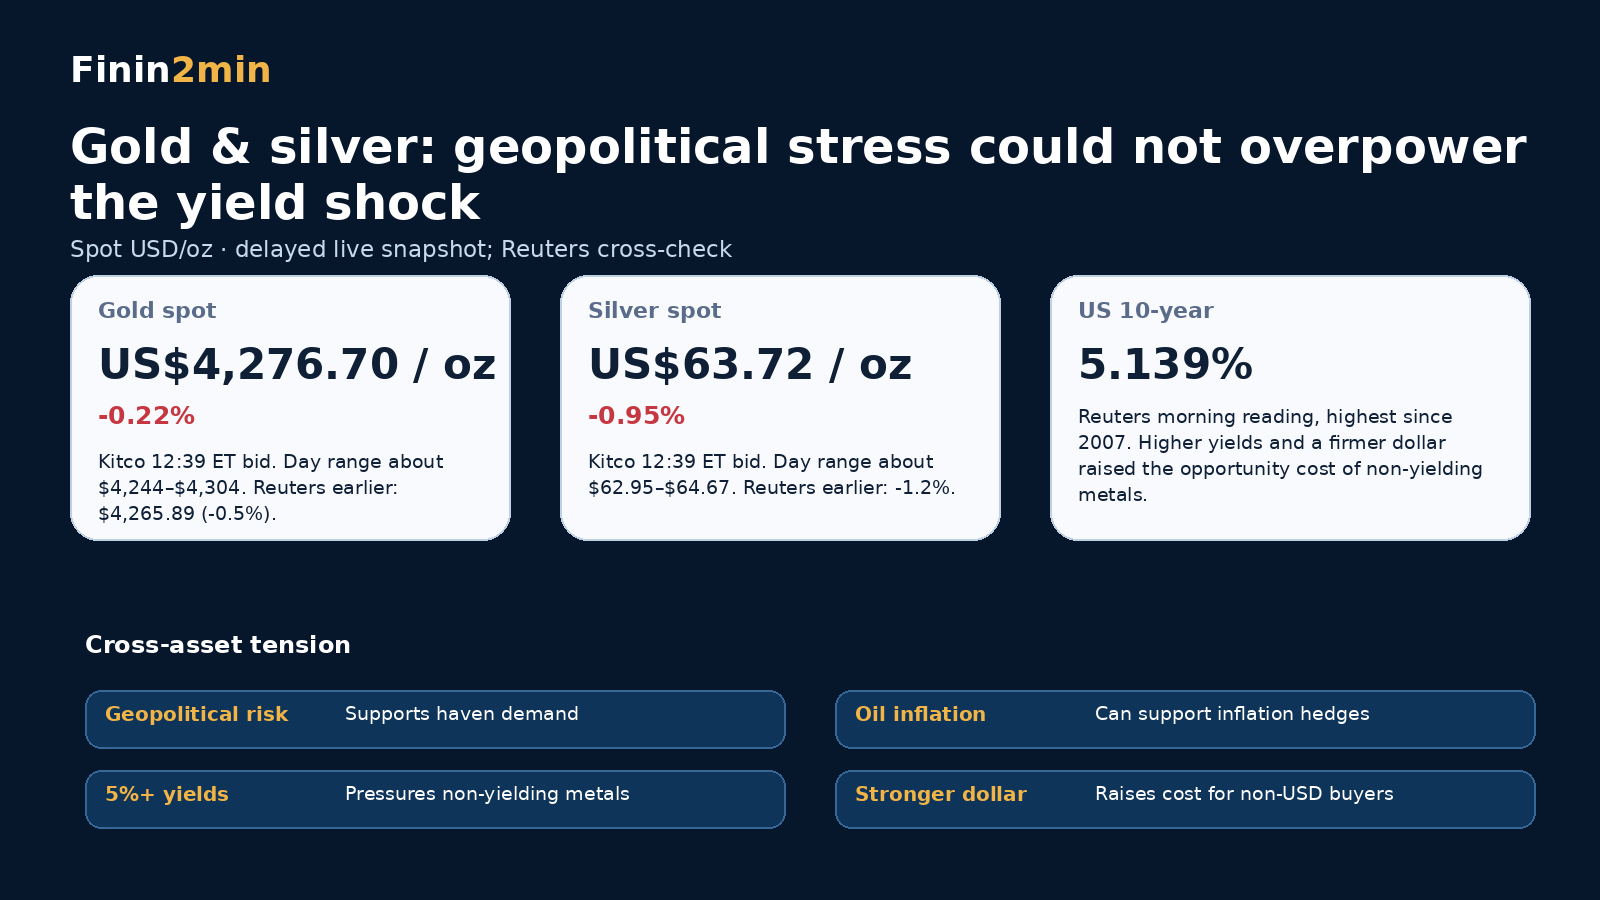
Gold & silver: haven demand meets a 5%+ yield hurdle
Reuters’ morning snapshot showed spot gold at $4,265.89/oz (-0.5%) and spot silver at $63.72/oz (-1.2%), while the US 10-year Treasury yield reached 5.139%, its highest since 2007 in Reuters coverage. A later Kitco delayed snapshot at 12:39 ET showed gold at $4,276.70 bid and silver at $63.72 bid. Gold’s quoted day range was about $4,244–$4,304; silver’s about $62.95–$64.67.
The cross-asset tension is important: geopolitical risk can create haven demand, but a stronger dollar and very high Treasury yields increase the opportunity cost of holding non-yielding metals. Silver typically moves more violently because it combines precious-metal and industrial-demand sensitivities.
Rupee: back near the 96 area
Reuters reported the rupee closing at 95.9550 per dollar, down about 0.2% and at a one-week low. Dollar sales by state-run banks, viewed by traders as likely RBI-linked, limited losses. NSE’s 17:00 IST reference rate was 95.9099; that is a separate reference rate and is not used as a substitute for the interbank close.
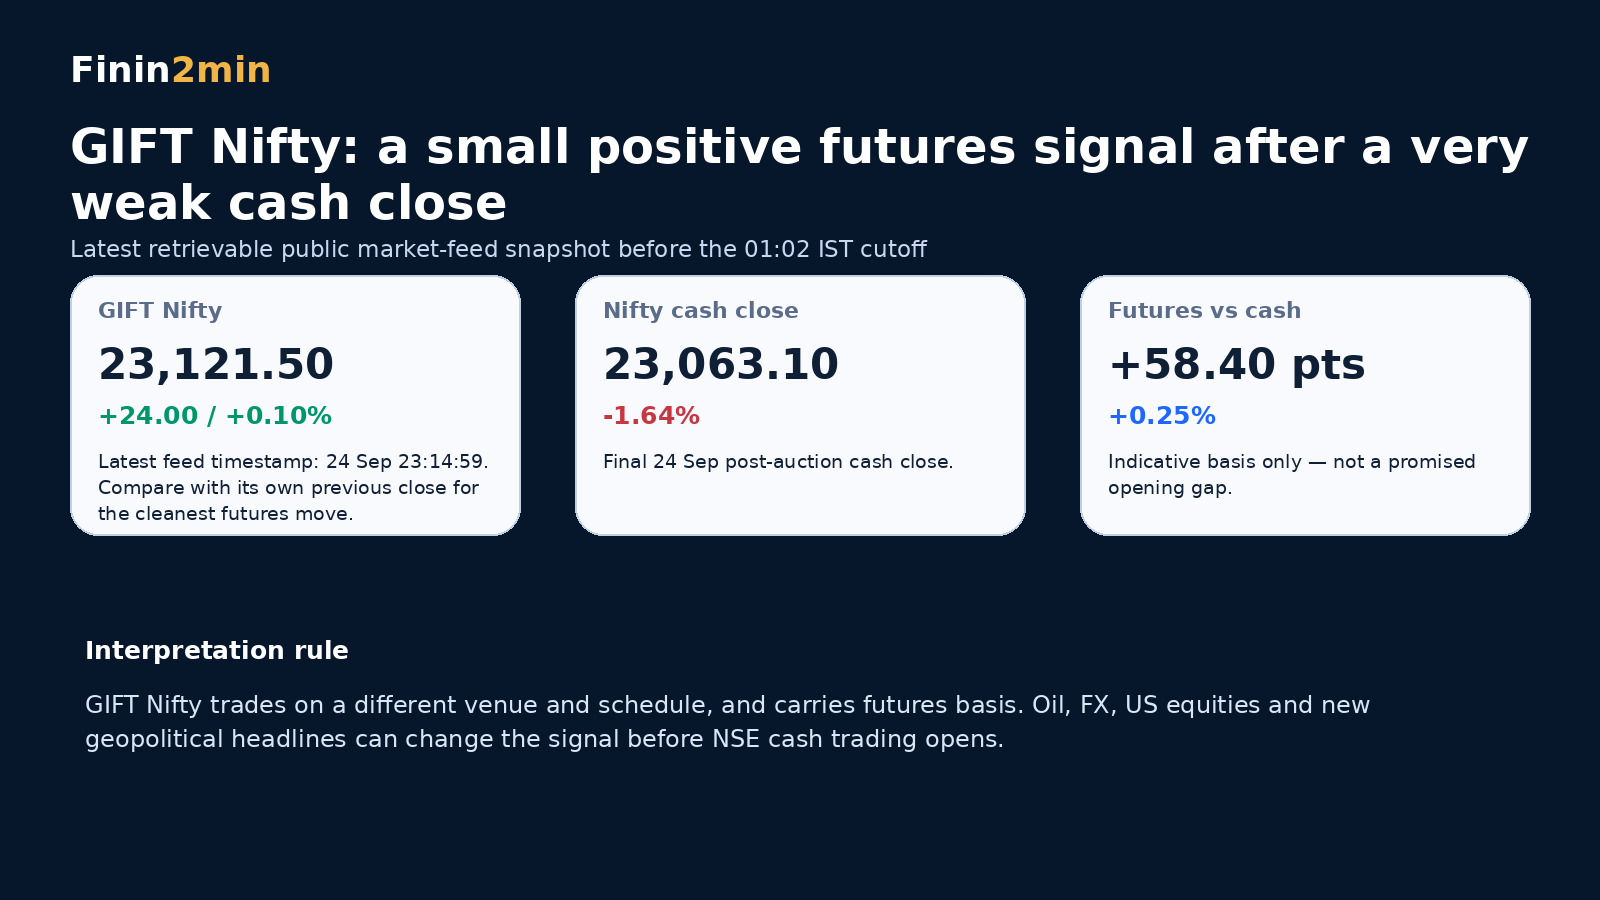
GIFT Nifty: modest positive signal, but basis matters
The latest retrievable GIFT Nifty market-feed snapshot before the 01:02 IST cutoff was 23,121.50, up 24 points (+0.10%) from its cited previous close. That is roughly 58.4 points (+0.25%) above Thursday’s Nifty cash close. Because GIFT Nifty is a futures contract on a different venue and schedule, the spread is indicative only and should not be interpreted as a promised opening gap.
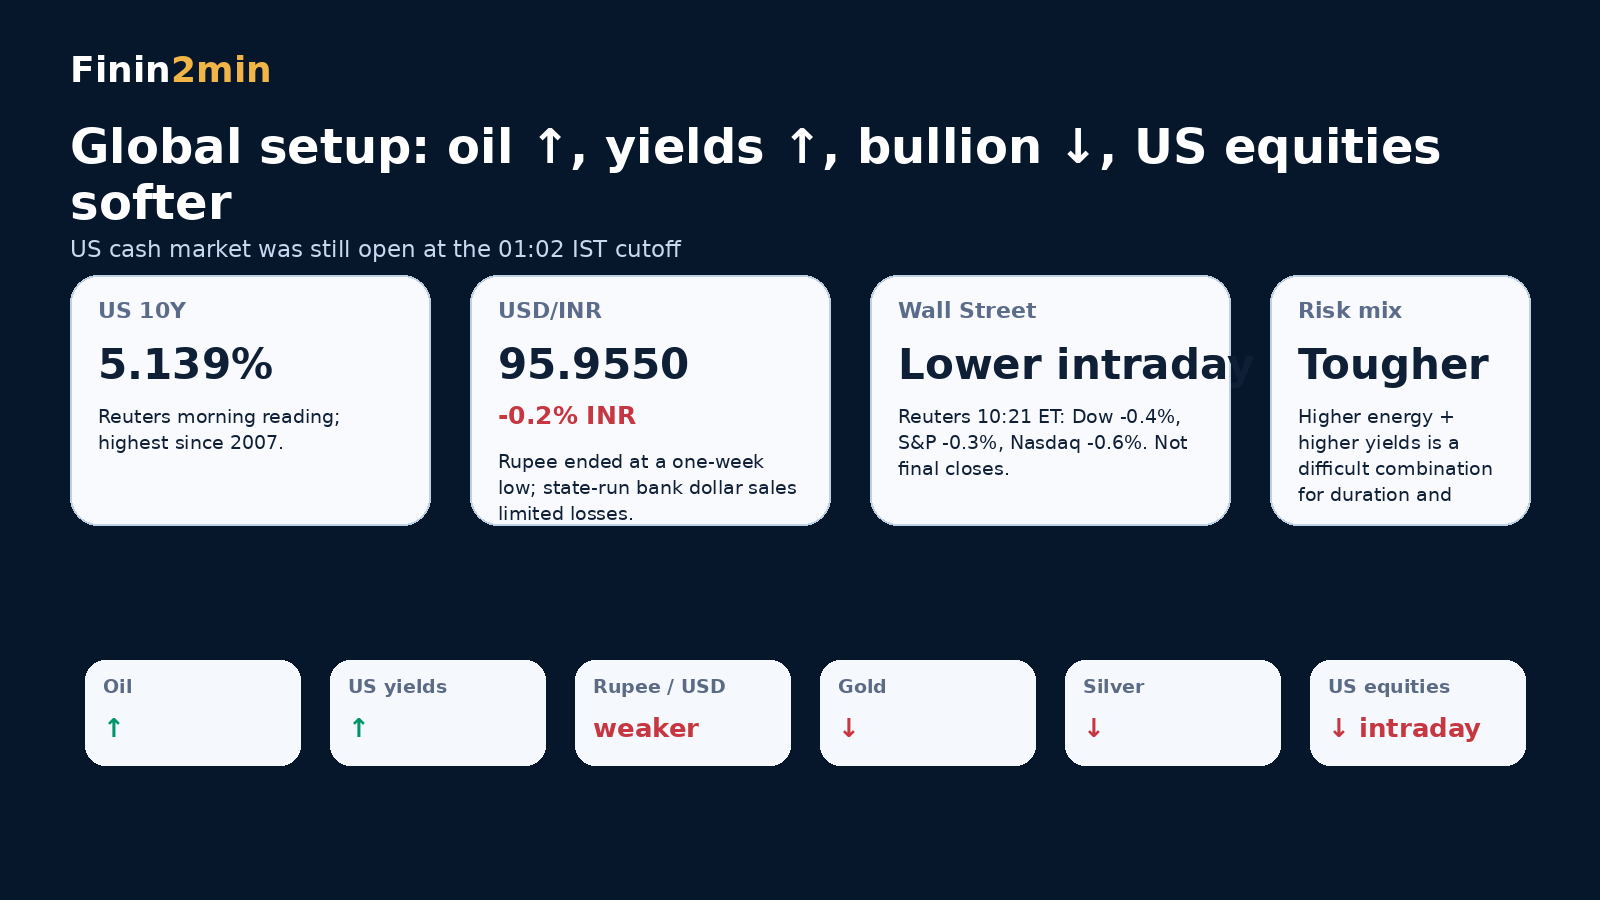
Global session: oil and yields stayed unfriendly
Reuters’ 10:21 a.m. ET Wall Street update showed the Dow down about 0.4%, the S&P 500 down 0.3% and Nasdaq down about 0.6%. The US cash session was still open at this edition’s cutoff, so those values are intraday, not final closes. The more durable signal for India was the combination of oil near the mid-$100s, a US 10-year yield above 5%, a rupee close to 96 and weaker precious metals despite geopolitical stress.
What to watch on 25 September
- Brent $105–108: whether supply/security headlines keep the geopolitical premium elevated.
- GIFT Nifty: treat the 23,121.50 snapshot as a futures indication, not a forecast.
- Nifty 23,000 area: a round-number reference after a 1.64% fall, not guaranteed support.
- USD/INR around 96: importer demand and possible RBI-linked dollar supply matter.
- Financials and insurers: distinguish the proposal/exposure-draft stage from final rules.
- Gold & silver vs US 10Y: 5%+ yields remain a meaningful hurdle for bullion.
- FII/DII flow follow-through: domestic buying almost, but not fully, offset foreign selling on Thursday.
Finin2min monitoring map
| Setup | Evidence to monitor | Cross-asset implication |
|---|---|---|
| Relief | Brent moves toward/below $103; rupee holds below 96; yields stop rising | Imported-cost pressure can ease; domestic breadth may stabilise |
| Volatile / range | Brent $103–108; rupee near 96; US 10Y around 5.1% | Rotation and headline sensitivity remain high |
| Stress extension | Brent sustains above $108; rupee breaks 96; yields climb; FII selling stays heavy | Imported-inflation and funding pressure intensify |
Primary / global source set
The editorial source stack is Reuters plus official/exchange and specialist global market-data sources. No Indian television/news-channel portal is used as an editorial source.
- NSE India — exchange/index framework
- NSE FII/DII — provisional institutional-flow methodology
- NSE IX — GIFT Nifty venue/product framework
- Reuters India — India equities, rupee and macro market coverage
- Reuters Energy — crude-oil developments and intraday readings
- Kitco — later delayed gold/silver spot cross-check
- US Treasury — official yield-curve source
- IRDAI — exposure-draft/regulatory repository
Data discipline: final cash closes, provisional flows, spot/futures/reference-rate distinctions and intraday-vs-final status are explicitly labelled. Scenario bands are monitoring frameworks, not forecasts or recommendations.
FinNews is educational and professional reference material, not financial, tax or legal advice. Confirm the current official position from the primary source before acting on any figure, rate, provision or deadline mentioned here.