Finin2min Daily Brief | 23 September 2026
India rebounds, then oil reverses: Brent settles above $103
India rebounds, then oil reverses: Brent settles above $103
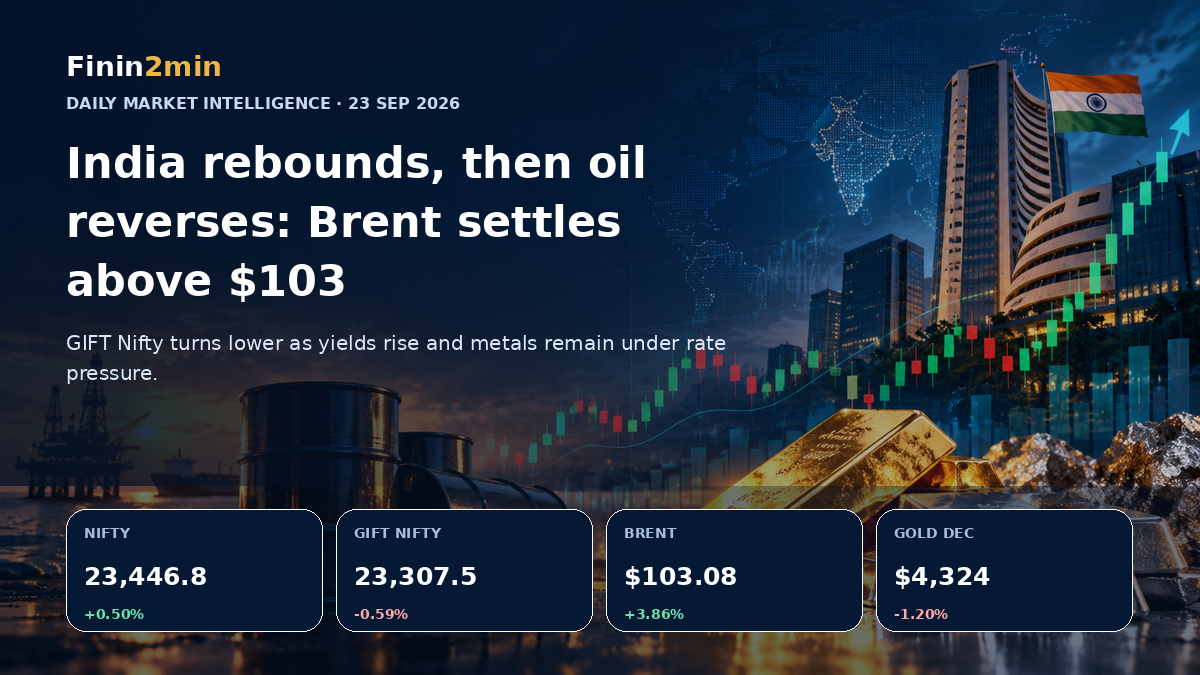
India’s Wednesday rebound was broad enough to look healthier than Tuesday’s move — until the global backdrop changed after the close. Brent reversed from sub-$100 levels to settle at $103.08, the U.S. 10-year yield jumped to 5.11%, the Nasdaq fell and the completed overnight GIFT Nifty session ended 0.59% lower.
The 2-minute view
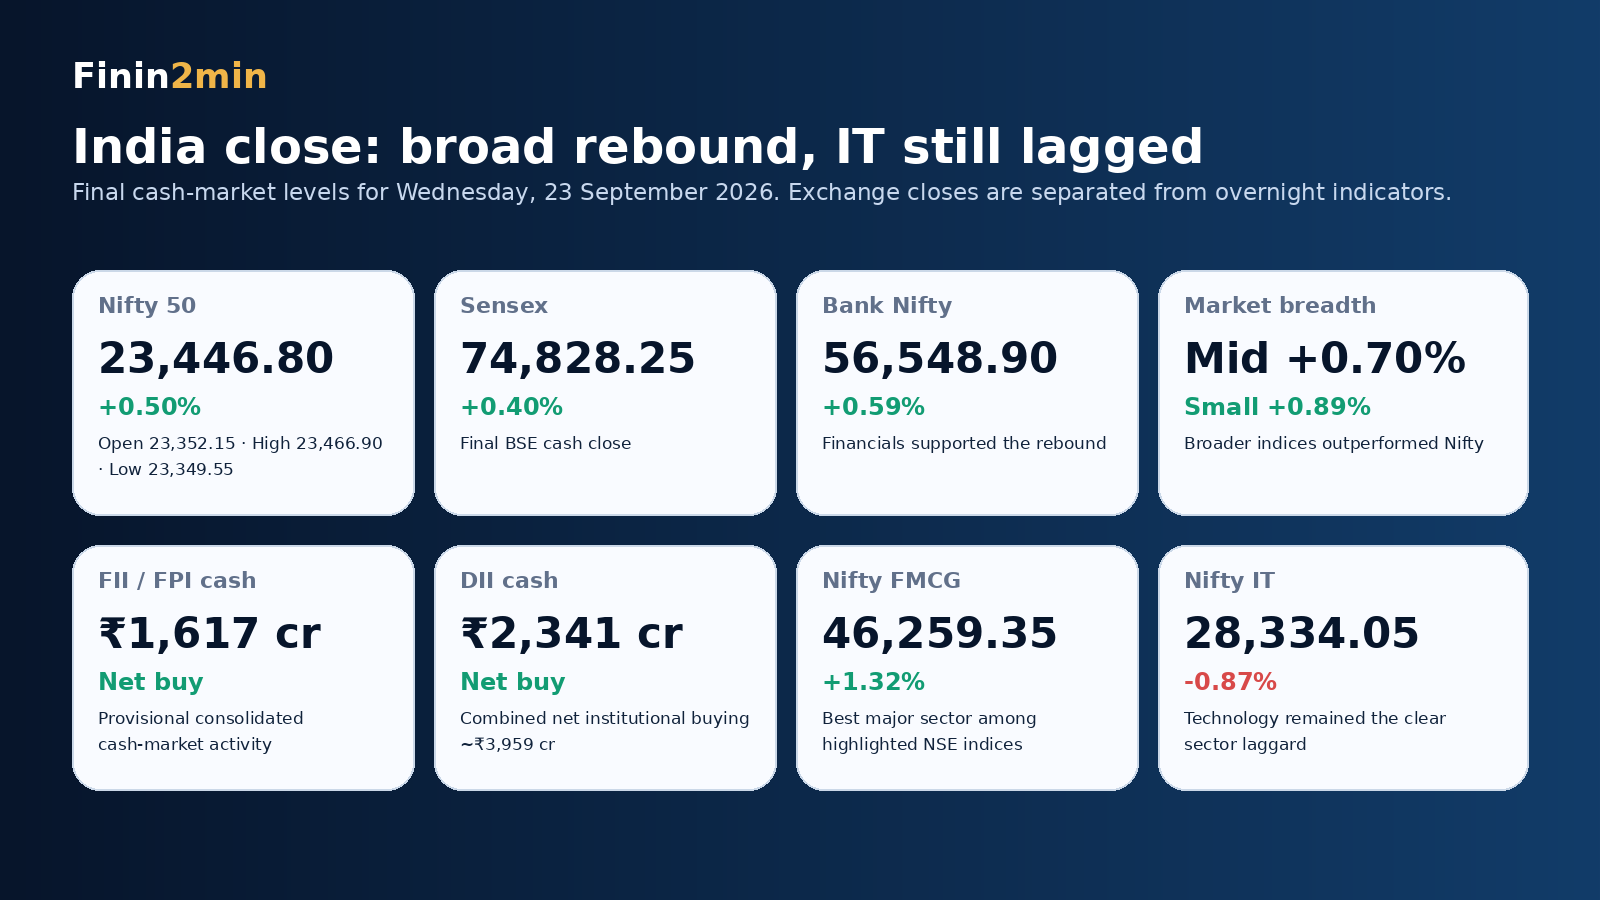
Nifty closed at 23,446.80 (+0.50%) and Sensex at 74,828.25 (+0.40%). Bank Nifty rose 0.59%, Midcap 100 0.70% and Smallcap 100 0.89%; IT was the major outlier at -0.87%. Provisional cash-market flows showed FIIs/FPIs buying about ₹1,617 crore and DIIs about ₹2,341 crore.
India close: a broader rebound
Wednesday’s advance was not just a headline-index move. FMCG rose 1.32%, Bank Nifty 0.59%, Midcap 100 0.70% and Smallcap 100 0.89%. Bajaj Finance, Hindalco and Tata Steel were among the stronger Nifty constituents, while IT remained weak. The final NSE snapshot is used throughout rather than pre-auction levels.
Institutions turned net buyers
Provisional consolidated cash activity showed FII/FPI net buying of about ₹1,617.45 crore and DII net buying of about ₹2,341.46 crore. Together that is roughly ₹3,958.91 crore of net institutional buying. These values are provisional and can be revised.
Crude: the biggest overnight reversal
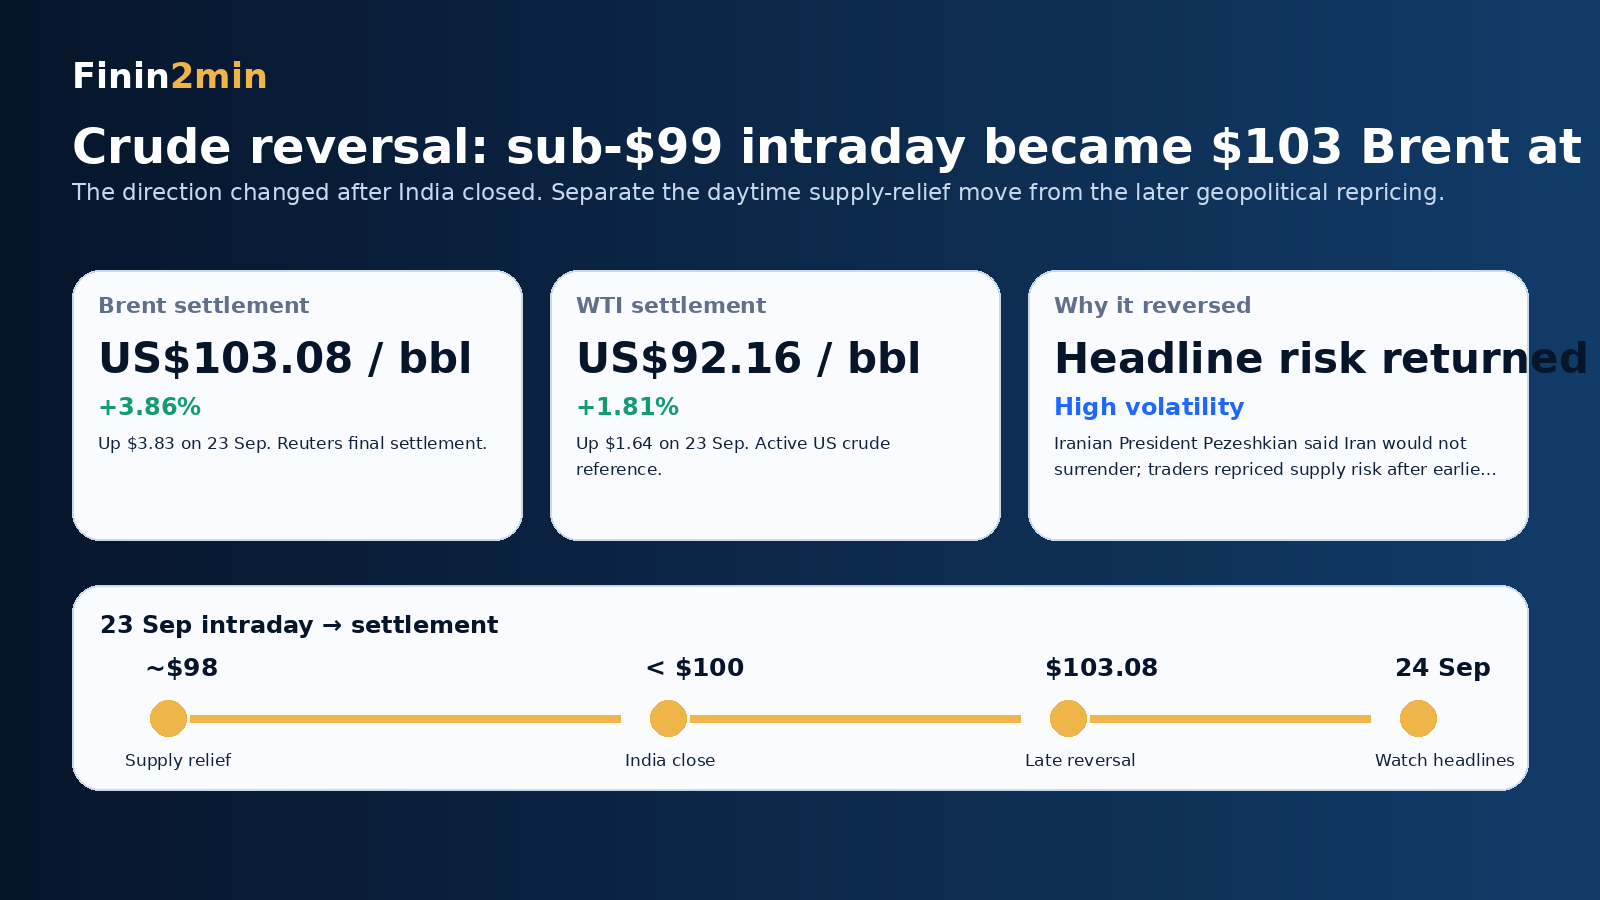
Crude was a tailwind during much of India’s session as markets focused on Saudi Arabia’s restored East-West Pipeline, improving alternative export routes and diplomacy. That narrative changed late. Reuters reported Brent settling $3.83 higher at $103.08 (+3.86%) and WTI $1.64 higher at $92.16 (+1.81%). Traders repriced geopolitical supply risk after Iranian President Masoud Pezeshkian said Iran would not surrender. No durable settlement to the conflict had been confirmed by this edition’s cutoff.
For India, the key issue is not simply whether Brent is above or below $100 for a few hours. A sustained oil-plus-dollar move can feed into import costs, inflation expectations, the rupee, bond yields and margins in oil-sensitive sectors.
Gold & silver: higher rates win the short-term tug-of-war
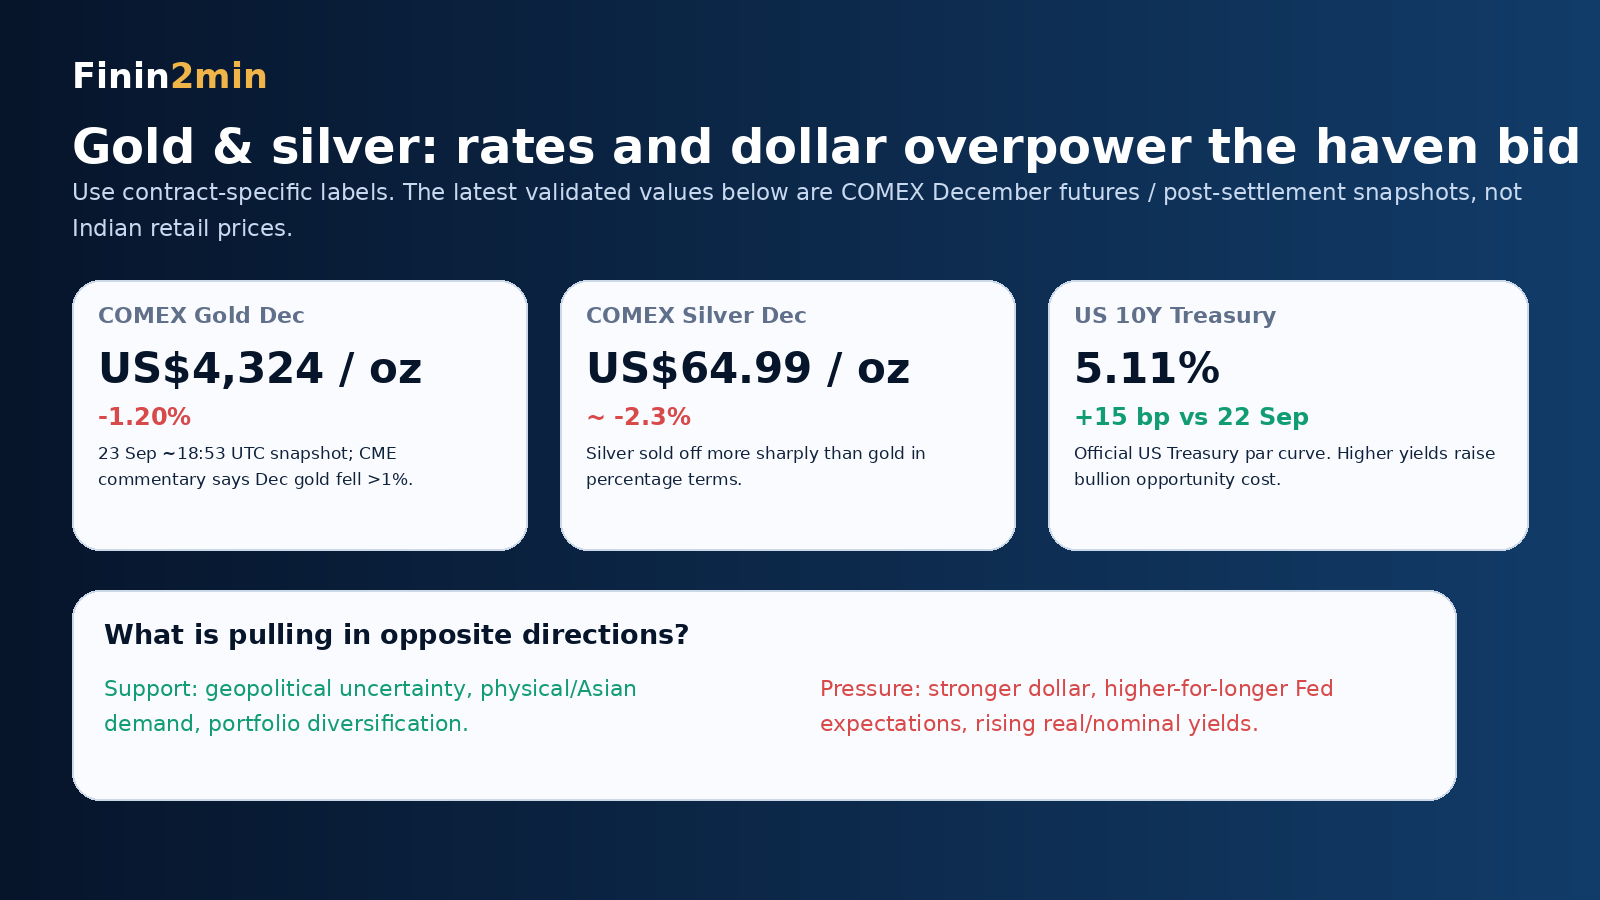
CME Group said December gold futures extended their slide by more than 1% as the dollar strengthened for a fourth session, while silver and platinum also lost ground. A validated post-settlement snapshot put December gold near $4,324/oz (-1.20%) and December silver near $64.99/oz (about -2.3%).
The official U.S. Treasury curve put the 10-year yield at 5.11%, up 15 basis points from 22 September. That raises the opportunity cost of holding non-yielding bullion. Geopolitical uncertainty remains a counterweight, so the metals can remain volatile even while the rate impulse is negative.
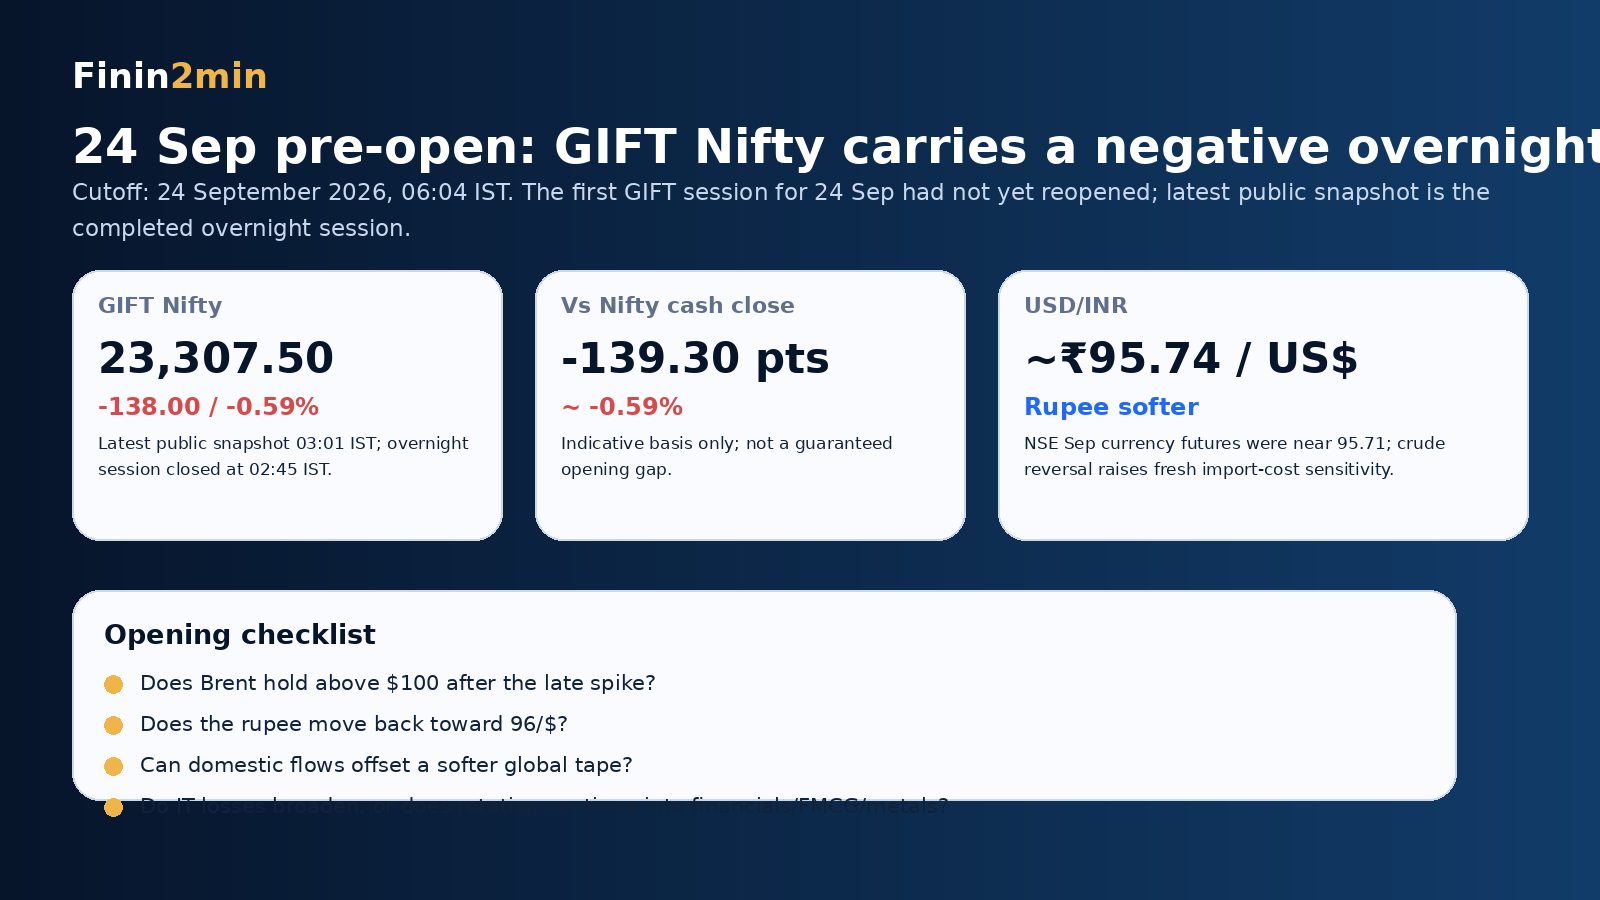
GIFT Nifty: negative overnight signal, but timestamp matters
The latest public NSE IX-derived snapshot was 23,307.50, down 138 points (-0.59%) from the cited previous close. It is about 139 points below Wednesday’s Nifty cash close. This is an indicative pre-open signal, not a guaranteed cash-market opening level.
The important timing detail: the completed overnight GIFT session ended before this 06:04 IST newsletter cutoff, and the next session begins at 06:30 IST. Any oil, currency or geopolitical development after 06:04 can change the opening signal.
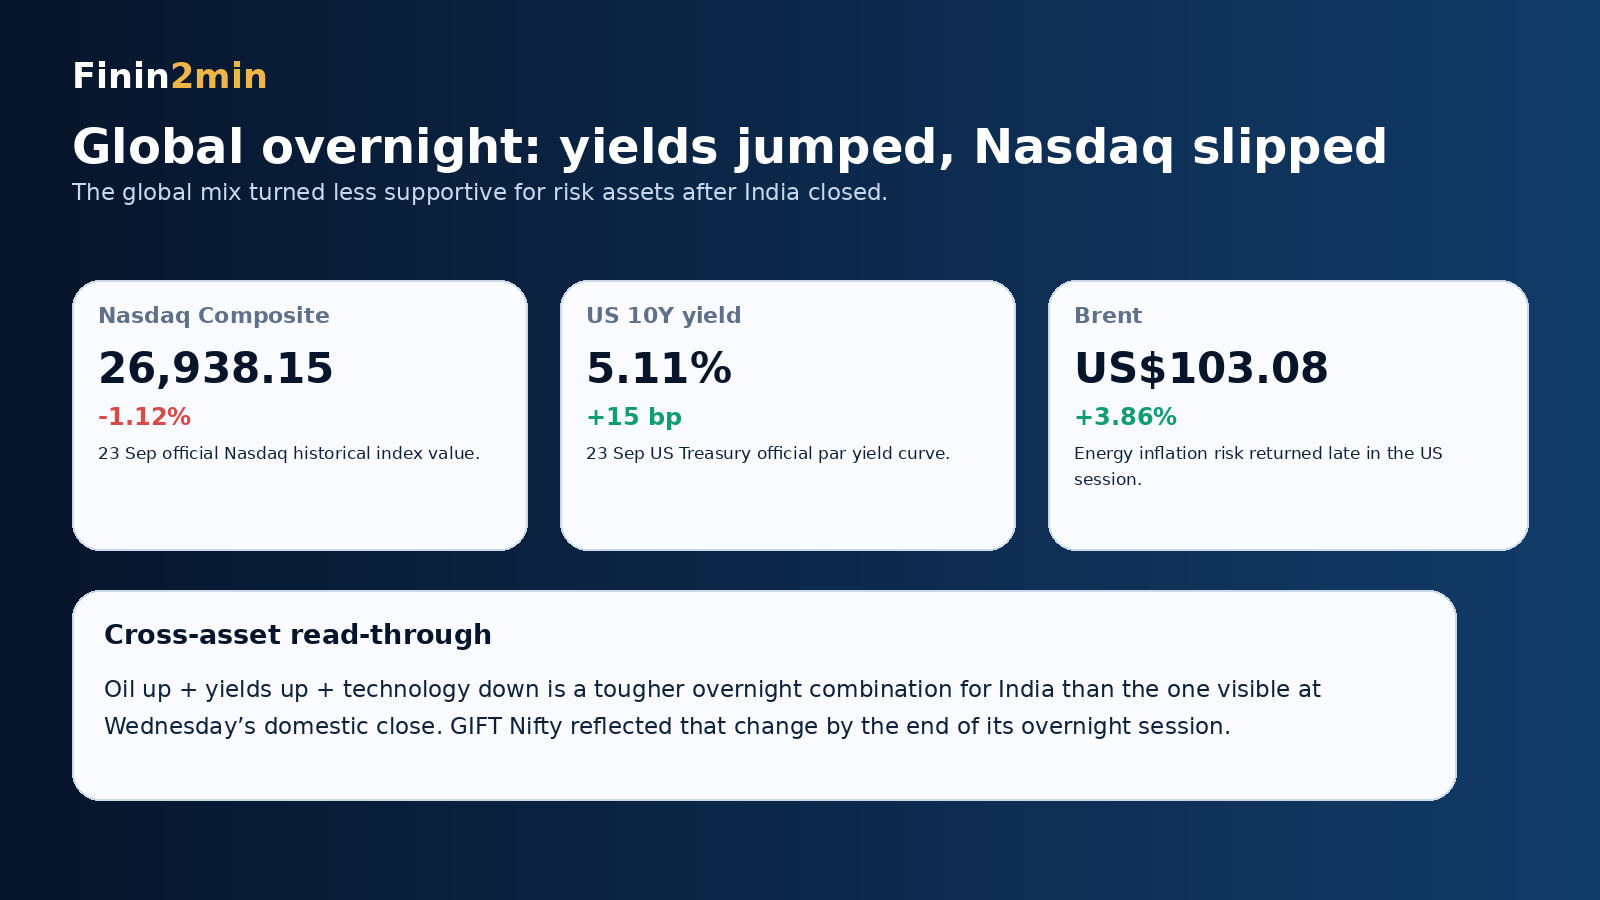
Global overnight: oil up, yields up, tech down
Nasdaq’s official historical page shows the Composite at 26,938.15 (-1.12%) on 23 September. The official U.S. Treasury curve shows the 10-year at 5.11%. Combined with Brent above $103, that is a tougher global mix for Indian risk assets than the setup visible during Wednesday’s domestic cash session.
Rupee & domestic macro
The rupee ended around ₹95.74 per US dollar; NSE’s September currency-futures reference was close to 95.71. The renewed oil spike makes the 96/$ region important to monitor, but this brief does not treat any level as a guaranteed intervention point.
India finance & corporate watch
NSE listing on 24 September
Reuters reported that National Stock Exchange shares are due to begin trading on Thursday after its approximately $2.3 billion IPO drew more than $10 billion of bids. The listing is a major domestic capital-market event and can affect liquidity and attention across exchange, broker and financial-market names.
UPI merchant-fee transition
The permitted 0.4% merchant fee on UPI transactions above ₹2,000 from 15 October remains a major payments-industry shift. It is not a universal consumer fee: commercial incidence depends on merchant, acquirer and platform arrangements.
RBI liquidity remains part of the rates story
Reuters reported earlier in the week that bond sales, FX operations and tax flows had sharply reduced banking-system surplus liquidity. That matters as India absorbs an external oil/rates shock while markets debate the future domestic policy path.
What to watch on 24 September
- Brent around/above $103 and whether Asia extends or fades the spike.
- The new GIFT Nifty session from 06:30 IST, which is more relevant than the completed overnight snapshot.
- USD/INR near 96 and any fresh importer/RBI activity.
- Whether IT weakness broadens or domestic rotation continues into financials, FMCG and metals.
- Gold and silver against a 5%+ U.S. 10-year yield.
- NSE listing-day liquidity and sentiment.
- Only verified Middle East diplomacy/shipping developments — distinguish confirmed agreements from negotiating positions.
Finin2min scenario map
| Setup | What would support it | Read-through |
|---|---|---|
| Constructive | Brent back below $100; rupee stable; GIFT recovers; domestic flows positive | Focus can return to domestic breadth and earnings |
| Choppy | Brent $100–104; yields elevated; GIFT only partly recovers | Rotation dominates; index upside harder to sustain |
| Risk-off | Oil extends above $104; rupee weakens toward/through 96; yields rise further | Pressure on import-sensitive sectors, bonds and broader risk appetite |
Primary / global source set
Reader-facing sources are Reuters plus independent official/exchange sources. No Indian TV/news-channel or portal source is cited.
- NSE India — Nifty 50, sector indices, index levels and exchange snapshots
- NSE India FII/DII — Methodology and provisional consolidated cash-market activity
- NSE IX — GIFT Nifty exchange and historical trade framework
- Reuters - India market — 23 Sep India market advance as lower oil aided sentiment; financials led
- Reuters - Energy — 23 Sep oil settlement: Brent US$103.08, WTI US$92.16; geopolitical reversal after intraday weakness
- Reuters - Gold — Higher-for-longer rates, stronger dollar and Middle East risk shaped precious metals
- CME Group — Gold futures extended slide as dollar rose; Silver also lost ground
- US Treasury — 23 Sep daily par yield curve; 10Y 5.11%
- Nasdaq — 23 Sep Nasdaq Composite final history
- Reuters - NSE IPO — NSE shares scheduled to begin trading 24 Sep after heavily subscribed IPO
- Reuters - UPI — 0.4% merchant fee above ₹2,000 from 15 Oct and payments-industry implications
- Reuters - RBI liquidity — Banking-system surplus liquidity was sharply reduced through RBI operations and market flows
- Reuters - Middle East diplomacy — US-Iran diplomatic signals remained mixed; no durable settlement confirmed by cutoff
- Reuters - Hormuz proposal — Iran signalled conditional readiness to reopen Hormuz if US eased pressure
FinNews is educational and professional reference material, not financial, tax or legal advice. Confirm the current official position from the primary source before acting on any figure, rate, provision or deadline mentioned here.