Section 194R TDS on Business Perquisites: 10% Rate
Reviewed by CA Nikhil Gupta · Last reviewed 9 October 2026
When a pharmaceutical company gives free product samples to doctors, or a brand sponsors an influencer's holiday in exchange for promotional posts, the value of that benefit is taxable income for the recipient - and since 2022, the person giving the benefit must deduct TDS on it under Section 194R.
What is Section 194R?
Section 194R, introduced by the Finance Act 2022 effective 1 July 2022, requires any person carrying on a business or profession to deduct TDS at 10% on the value of any benefit or perquisite (whether convertible into money or not) provided to a resident in connection with that business or profession.
The provision was introduced to plug a long-standing gap: businesses were giving valuable non-cash benefits - free samples, sponsored trips, gift vouchers, cars, gadgets - to doctors, dealers, distributors, and social media influencers, and these recipients were often not declaring the value as income.
Who Deducts and Who is Covered
| Particulars | Details |
|---|---|
| TDS Rate | 10% of the value or aggregate value of the benefit/perquisite |
| Threshold | Exempt if aggregate value to a single person does not exceed Rs 20,000 in the financial year |
| Who deducts | Any person (other than individuals/HUFs with turnover below Rs 1 crore for business or Rs 50 lakh for profession) providing the benefit |
| Who is covered | Any resident person carrying on business or profession who receives the benefit |
| Cash component required? | No - TDS applies even if the entire benefit is in kind |
Common Examples Covered
- Free medicine samples given by pharma companies to doctors
- Sponsored trips, hotel stays, and event tickets given to dealers, distributors, or influencers
- Gift vouchers, gold coins, electronics given as incentives for achieving sales targets
- Free products given to social media influencers for reviews, where the product is not returned
- Cars or other assets given to dealers as incentives, where ownership is transferred
How TDS is Paid on a Non-Cash Benefit
This is the most practically confusing part of Section 194R: if the entire benefit is in kind (say, a free car worth Rs 5 lakh), there's no cash from which to deduct 10% TDS. The law provides two options:
- The person providing the benefit can pay the TDS amount themselves (grossing up), in which case the TDS is paid before releasing the benefit
- The recipient can pay the TDS amount in cash to the person providing the benefit, who then deposits it with the government
In practice, most businesses choose to gross up and bear the TDS cost themselves as part of the promotional expense, since asking a dealer or doctor to pay cash TDS on a 'free' gift is commercially awkward.
Valuation of Benefits
The value of the benefit is generally its fair market value. If the business itself purchased the item (e.g., bought a car to give to a dealer), the purchase price is typically taken as the value. If the business manufactures the item (e.g., a pharma company giving away its own product samples), the value is based on the price at which the business sells that item to its customers, not the cost of production.
Impact on Recipients
From the recipient's side, the value of the benefit received (as reflected in Form 26AS against the TDS deducted under Section 194R) must be reported as business or professional income, and is taxable at the recipient's applicable slab rate. A doctor receiving free samples worth Rs 2 lakh in a year must include that Rs 2 lakh as professional income, separate from consultation fees.
Exclusions from Section 194R
- Benefits provided to non-residents are not covered (covered under other TDS/withholding provisions if applicable)
- Sales discounts, cash discounts, and rebates allowed to customers are excluded
- Benefits below the Rs 20,000 aggregate annual threshold per recipient
Business benefits/perquisites — TDS and recipient tax are separate tests
Decision table
| Situation | 2026 treatment / control | Why it matters |
|---|---|---|
| Aggregate benefit within threshold | No withholding under this provision if statutory threshold is not exceeded. | Aggregate per recipient for the year. |
| Cash/convertible benefit | Deduct tax under current rule where applicable. | Value the benefit correctly. |
| Wholly in-kind benefit | Provider must ensure tax is paid before release. | No cash exists to deduct from. |
| Recipient disputes taxability | TDS and final assessment are separate. | Preserve contract/business nexus and valuation. |
Worked practical example
A distributor receives an overseas trip worth ₹1.2 lakh as a sales incentive. The provider should not ignore withholding because nothing was paid in cash; it must apply the in-kind rule and valuation evidence.
Evidence checklist
- scheme/contract
- recipient-wise benefit ledger
- valuation support
- TDS challan/certificate
- recipient acknowledgement
Primary-source checks: Income Tax Department TDS rates · Income-tax Act 2025 — as enacted, 21 August 2025
Use this with the original article: this module tightens current-law, edge-case and evidence controls; it does not replace the article's existing explanation or your fact-specific professional review.
Updated analysis for Tax Year 2026-27: Section 194R Business Perquisites: 10% TDS, Valuation and Examples
Added and reviewed on 9 October 2026. This section adds worked examples and current-year controls to the guide above; where the two differ, follow the statute and the latest notification.
The transaction test before any arithmetic
A business may reward a distributor with an overseas trip, give a doctor product samples, transfer equipment to a sales influencer or provide a prize for hitting targets. The statutory question is whether the resident recipient receives a benefit or perquisite arising from the carrying on of business or profession. Not every free item is automatically taxable as a business perquisite; promotional material, ordinary trade discounts and true price reductions require examination of their actual nature. The giver needs to identify the recipient, the commercial purpose and the evidence that substantiates the classification.
Current statute and the former section number
The well-known 194R framework in the Income-tax Act, 1961 began in 2022. From April 2026 the corresponding rule appears in section 393(1) Table serial 8(iv) of the Income-tax Act, 2025. It specifies 10% withholding on the benefit or perquisite value and a ₹20,000 aggregate threshold for the relevant resident recipient, subject to the table's payer and applicability rules. Older circulars explaining the operation of 194R can be helpful for interpretation, but they should be read with current legislative wording rather than assumed to override it.
Who is responsible for the deduction?
The company or other specified giver ordinarily determines whether its provision of the benefit falls within the statutory rule and whether it has a withholding obligation. Do not shift that responsibility to the recipient merely because the benefit is physical rather than cash. The payee's residency, identity, business relationship and any statutory exclusion are part of the decision. For a chain of distributor incentives, identify the actual recipient of each benefit and check whether the commercial intermediary holds it for itself or simply passes it through on behalf of someone else.
Valuation drives the tax result
When a benefit is not cash, the payer must establish a defensible value. Purchase invoice, the actual cost of a sponsored trip, a reliable cost or valuation of goods, event invoices and agreement terms can support the computation. A company should document whether goods are returned, consumed in testing, provided for advertising or retained permanently by the business associate. Double counting is possible when a bill separately includes GST and the underlying perquisite value is taken from gross expenditure without examining the official valuation guidance and actual transaction.
Example: a dealer incentive weekend
A vehicle-component company promises a three-day reward trip for every dealer crossing a sales target. One dealer qualifies and the attributable benefit value is ₹72,000. If the dealer is a resident business recipient, the payer is within the statutory class and no special exception applies, the indicative TDS is ₹7,200 at 10%. The payer should document who enjoyed the trip, whether spouses or family members participated and whether some expenses represent genuine company business expenditure rather than personal benefit. The invoice total cannot replace this analysis automatically.
What if the reward is wholly in kind?
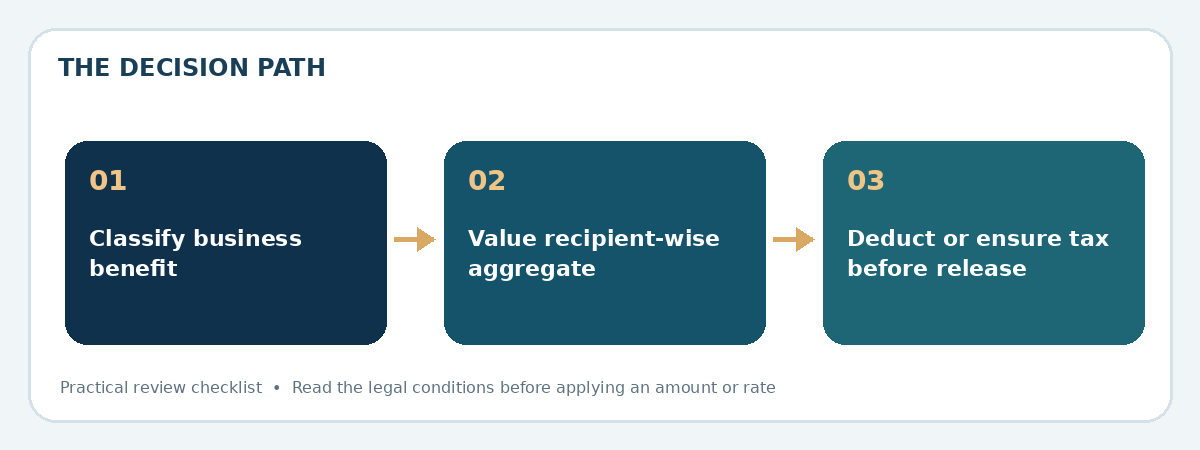
A fully in-kind benefit creates a collection problem because there may be no cash payment from which tax can be withheld. Before releasing the benefit, the giver needs to ensure the statutory tax compliance is satisfied under the applicable mechanism. Examples include transferring a mobile device to a professional or releasing a vehicle-related reward without any monetary settlement. Internal finance approval should check the tax payment evidence before the product is dispatched. Offering to “deduct it next month” may fail if there is no contract or later amount from which to deduct.
Cases that merit careful classification
Distributor year-end discounts, quantity rebates, free product samples, training events, conference attendance and employer-provided perquisites have different legal contexts. A reward attached to business performance is not equivalent to an employee salary benefit merely because an individual receives it. Likewise, consumer promotional gifts are not necessarily business perquisites in the recipient's hands. The finance team should cross-check the recipient's status and the legal substance, with specific reference to applicable CBDT guidance on section 194R where relevant.
Evidence and annual tracking
Maintain a recipient-wise register showing PAN, legal status, date, description, value, method of valuation, threshold utilisation, tax collected or borne, challan and return-reference number. A scheme advertised through marketing can still produce an accounts-payable withholding obligation, so marketing and finance must share award data. A ledger credit for an in-kind gift without a recipient map cannot support a reliable threshold test. Obtain sign-off before year-end benefits are distributed.
Common misunderstandings
The ₹20,000 threshold is not a general exemption for every benefit once a recipient has crossed it; check the statute's wording on the relevant aggregate. Charging GST or including an item in marketing costs does not determine the withholding result. A free sample sent for product testing may differ from a gift transferred for the recipient's personal use. Where the company bears the tax itself, evaluate grossing-up and the resulting accounting implications separately rather than assuming a flat 10% of the purchased item will always settle the matter.
Questions readers ask
Is cash needed for a section 194R type benefit?
No. The benefit or perquisite can be wholly in kind.
What is the general rate in Tax Year 2026–27?
The relevant section 393 table row provides 10%, subject to applicability.
Does an ordinary cash discount create TDS automatically?
No. Analyse the actual commercial nature, including whether it is a genuine price discount.
How is the ₹20,000 threshold monitored?
By aggregating relevant benefits recipient-wise during the tax year.
Who pays tax when the benefit is a physical item?
The payer must ensure the applicable withholding/tax mechanism is completed before release.
Does the old section 194R number remain the current legislative citation?
For the new tax year, use section 393(1) Table serial 8(iv) while identifying 194R as its historical counterpart.
Official sources for this update
- Income-tax Act 2025, s393(1) Table serial 8(iv)
- Old section 194R, historical reference
- Income-tax Act 2025 consolidated text
Related reading on Finin2min
Frequently Asked Questions
Source and review trail
Use the current official instrument, portal or regulator publication before acting.
- Primary category
- Income Tax
- Official starting point
- www.incometax.gov.in
Primary sources & related provisions
Statutory provisions referenced in this guide: