In 2 Minutes
The practical answer: How to read and respond to a notice under section 142(1) for earlier assessment years while recognising the 2025 Act transition for Tax Year 2026-27 onward. The safest workflow is to classify the proceeding, lock the applicable law and year, build a query-wise evidence file, respond through the prescribed channel and preserve the filing trail.
- Do not act from the keyword alone. “income tax notice section 142 demand” may use shorthand, old numbering or a non-statutory label.
- 2026 transition matters. Earlier assessment years can remain under the 1961 Act even though the 2025 Act is now in force.
- Evidence beats narrative. Every material factual claim should be capable of being traced to a document, ledger, portal record, statement or other reliable evidence.
- Deadlines are remedy-specific. Response, assessment, appeal, stay and document-retention periods are different clocks.
Why this topic matters in 2026
A notice seeks bank statements, books and an explanation of a variance. The taxpayer first confirms that the notice concerns an assessment year preserved under the 1961 Act, then answers each requisition in the same sequence and retains the transaction/acknowledgement record.
For work done in September 2026, the transition is not optional background. The Income-tax Act, 2025 has been in force from 1 April 2026, but the Department's own guidance confirms that earlier-year proceedings can remain governed by the 1961 Act under the savings provisions. Accordingly, this article uses the year/proceeding as the control key and does not mechanically substitute new section numbers into an older matter. Applied specifically to “Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition”.
The operational risk is often larger than the tax computation. A correct substantive position can still be weakened by an out-of-time filing, an answer sent through the wrong channel, missing proof of service, inconsistent amounts across annexures, or an appeal filed before the wrong forum. Conversely, a clean procedure cannot rescue weak facts. The objective is therefore a single defensible file that integrates law, chronology, computation and evidence. Applied specifically to “Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition”.
Legal framework and the governing-year test
A notice response is a procedural record, not merely a letter. Start by identifying the issuing authority, the section quoted, the year concerned, the response/hearing date and the electronic service trail. Then separate jurisdictional objections, factual explanations and documentary proof. Where the notice belongs to an assessment year beginning before 1 April 2026, do not casually replace the 1961 Act section numbers with the 2025 Act numbering: the savings/transition rules can preserve the old Act. Applied specifically to “Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition”.
For a September 2026 filing, create a “governing law” cover sheet before drafting. Record: (1) the income/tax year or assessment year, (2) the date and section of the underlying order/notice, (3) whether the proceeding was pending on 1 April 2026, (4) the savings/transition provision if an earlier-year matter is preserved, and (5) the prescribed form/rule currently applicable. This one-page control prevents a common error: citing a valid section from the wrong Act. Applied specifically to “Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition”.
| Control question | What to establish | Why it changes the answer |
|---|---|---|
| Which year is involved? | Assessment Year under the preserved 1961 Act or Tax Year under the 2025 Act. | Section numbers, forms and procedural rules can differ. |
| What is the actual proceeding? | Notice, assessment, reassessment, penalty, demand, appeal, summons/search, or special-law proceeding. | Each has a different power, response and remedy. |
| What was served and when? | Portal/service record, DIN/reference, date of service and due date. | Limitation and procedural fairness often turn on service. |
| Which rule/form applies? | Current prescribed form and filing channel for that governing Act/year. | A substantively correct case can fail operationally if filed in the wrong way. |
Decision table: choose the next action
| Situation | Practical response |
|---|---|
| Notice is genuine and clear | Respond query-by-query on the prescribed portal and preserve the acknowledgement. |
| Notice is genuine but scope is unclear | Seek a precise clarification or reasonable adjournment while preserving the original due date until relief is granted. |
| Year/section appears mismatched | Raise the point carefully with the underlying documents; do not ignore the notice. |
| Material is held by a third party | Explain custody, identify the third party, produce what is available and document efforts to obtain the balance. |
The table is a triage tool, not a substitute for the underlying provision. Where more than one route appears possible, protect the earliest limitation date first and record why the team chose one remedy over another. If a rectification or adjournment request is being pursued, do not assume it automatically suspends a separate appeal or response deadline unless the law/order expressly produces that result. Applied specifically to “Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition”.
Five evidence controls that decide the quality of the case
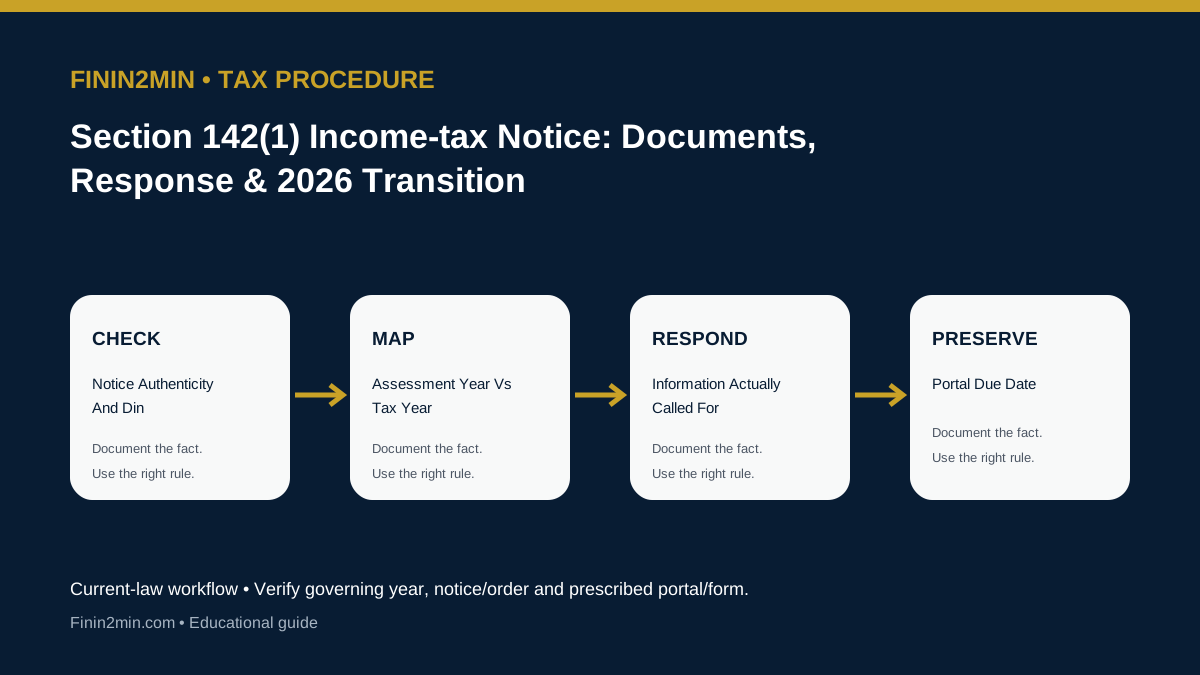
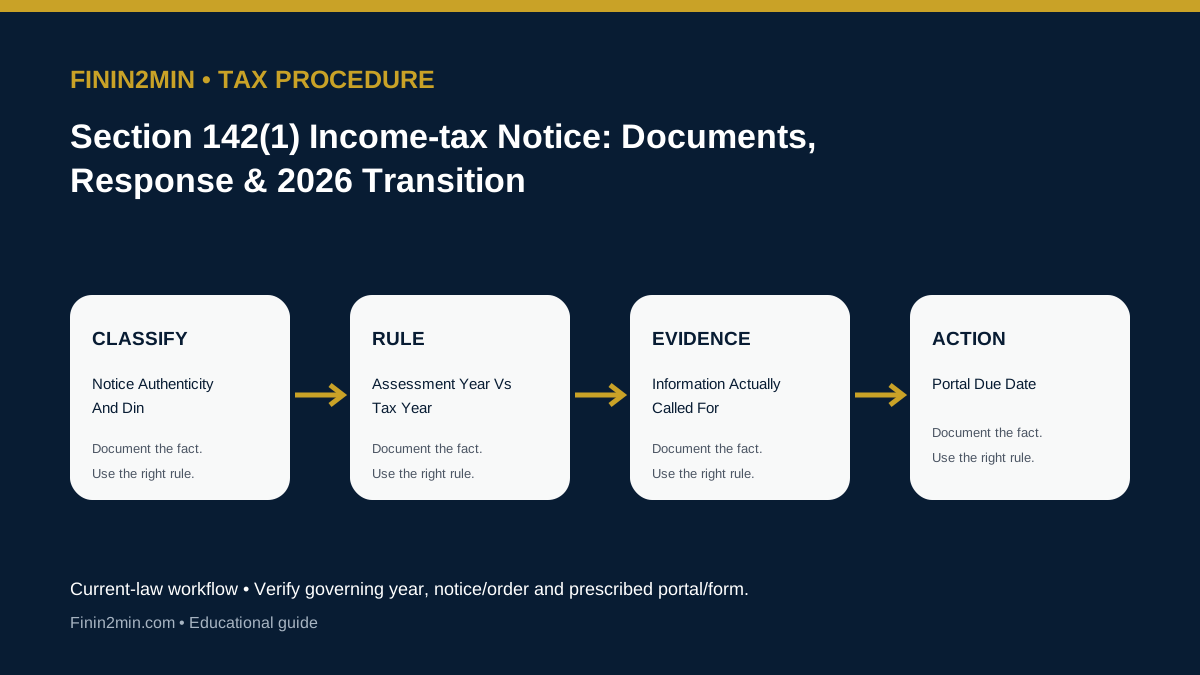
1. Notice Authenticity And Din
For Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition, notice authenticity and DIN should be treated as a separate work-paper heading. Record the source document, the date, the person responsible for the fact, the amount or period involved where relevant, and the way it connects to the notice/order. Do not let an oral explanation stand alone when a contemporaneous bank record, ledger, portal record, contract, return, challan, email or statutory document can prove the point more reliably.
A reviewer should be able to reproduce the conclusion from the file without asking what the taxpayer 'meant'. That means cross-referencing evidence by annexure number, explaining any mismatch rather than hiding it, and clearly distinguishing a fact, an estimate, an inference and a legal submission. Applied specifically to “Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition”.
2. Assessment Year Vs Tax Year
For Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition, assessment year vs tax year should be treated as a separate work-paper heading. Record the source document, the date, the person responsible for the fact, the amount or period involved where relevant, and the way it connects to the notice/order. Do not let an oral explanation stand alone when a contemporaneous bank record, ledger, portal record, contract, return, challan, email or statutory document can prove the point more reliably.
A reviewer should be able to reproduce the conclusion from the file without asking what the taxpayer 'meant'. That means cross-referencing evidence by annexure number, explaining any mismatch rather than hiding it, and clearly distinguishing a fact, an estimate, an inference and a legal submission. Applied specifically to “Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition”.
3. Information Actually Called For
For Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition, information actually called for should be treated as a separate work-paper heading. Record the source document, the date, the person responsible for the fact, the amount or period involved where relevant, and the way it connects to the notice/order. Do not let an oral explanation stand alone when a contemporaneous bank record, ledger, portal record, contract, return, challan, email or statutory document can prove the point more reliably.
A reviewer should be able to reproduce the conclusion from the file without asking what the taxpayer 'meant'. That means cross-referencing evidence by annexure number, explaining any mismatch rather than hiding it, and clearly distinguishing a fact, an estimate, an inference and a legal submission. Applied specifically to “Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition”.
4. Portal Due Date
For Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition, portal due date should be treated as a separate work-paper heading. Record the source document, the date, the person responsible for the fact, the amount or period involved where relevant, and the way it connects to the notice/order. Do not let an oral explanation stand alone when a contemporaneous bank record, ledger, portal record, contract, return, challan, email or statutory document can prove the point more reliably.
A reviewer should be able to reproduce the conclusion from the file without asking what the taxpayer 'meant'. That means cross-referencing evidence by annexure number, explaining any mismatch rather than hiding it, and clearly distinguishing a fact, an estimate, an inference and a legal submission. Applied specifically to “Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition”.
5. Document Index And Submission Proof
For Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition, document index and submission proof should be treated as a separate work-paper heading. Record the source document, the date, the person responsible for the fact, the amount or period involved where relevant, and the way it connects to the notice/order. Do not let an oral explanation stand alone when a contemporaneous bank record, ledger, portal record, contract, return, challan, email or statutory document can prove the point more reliably.
A reviewer should be able to reproduce the conclusion from the file without asking what the taxpayer 'meant'. That means cross-referencing evidence by annexure number, explaining any mismatch rather than hiding it, and clearly distinguishing a fact, an estimate, an inference and a legal submission. Applied specifically to “Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition”.
Step-by-step execution workflow
- Step 1. Download and archive the complete notice/order and record its DIN/reference, authority, section, year, service date and stated deadline.
- Step 2. Classify the issue behind “income tax notice section 142 demand”: identify the actual statutory proceeding rather than relying on the keyword label.
- Step 3. Determine whether the Income-tax Act, 1961 or Income-tax Act, 2025 governs the year/proceeding; where a special law applies, map that law separately.
- Step 4. Create an issue matrix for notice authenticity and DIN, assessment year vs tax year, information actually called for; assign each issue an evidence owner and annexure number.
- Step 5. Reconcile the facts to the return, AIS/TIS/SFT information, books, bank records, challans, earlier submissions and orders to the extent relevant.
- Step 6. Draft the legal/factual response in the same sequence as the notice/order. State what is admitted, disputed, not applicable or requires clarification.
- Step 7. Run a contradiction check across dates, amounts, names, account numbers and prior filings. Resolve differences in the text rather than leaving the reviewer to infer them.
- Step 8. File through the prescribed portal/form/channel, retain the final uploaded files plus transaction/acknowledgement evidence, and diarise the next statutory event.
Build a response chronology before writing prose
Use a simple chronology with columns for date, event, source document, amount/period, person involved and legal significance. For Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition, the chronology should include every event relevant to notice authenticity and DIN, assessment year vs tax year, information actually called for, portal due date. A chronology is especially valuable where a portal date differs from the printed order date, funds move through several accounts, evidence is received from a third party, or more than one statutory proceeding is active.
Use an issue–evidence–conclusion matrix
For each disputed point, state the department's proposition in one sentence, the taxpayer's position in one sentence, the documents that prove it, any computation, the legal rule relied on and the relief requested. This structure prevents the two most common drafting failures: a narrative that never answers the specific question and a document bundle that never explains what each document proves. Applied specifically to “Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition”.
Document and evidence checklist
| # | Evidence stream | Minimum file | Control test |
|---|---|---|---|
| 1 | Notice Authenticity And Din | Primary document + reconciliation + explanatory note | Cross-reference to the specific issue in Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition |
| 2 | Assessment Year Vs Tax Year | Primary document + reconciliation + explanatory note | Cross-reference to the specific issue in Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition |
| 3 | Information Actually Called For | Primary document + reconciliation + explanatory note | Cross-reference to the specific issue in Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition |
| 4 | Portal Due Date | Primary document + reconciliation + explanatory note | Cross-reference to the specific issue in Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition |
| 5 | Document Index And Submission Proof | Primary document + reconciliation + explanatory note | Cross-reference to the specific issue in Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition |
Worked practical scenario
Applied scenario: assume a taxpayer, finance team or entity is dealing with “income tax notice section 142 demand” in September 2026. The preparer first tests whether notice authenticity and din. The file then records whether assessment year vs tax year, before deciding the filing, payment, disclosure or commercial action.
The reviewer independently tests the third control—Information Actually Called For—against the cited primary sources and underlying documents. Any mismatch is put into an exception log with an owner and resolution date. This makes the example specific to Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition rather than a generic compliance checklist.
Common mistakes and how to avoid them
- Replying only by informal email when the notice requires e-proceedings. In Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition, this can distort the record or cause the taxpayer to choose the wrong procedural route. Correct it by tying the response to the exact order/notice, governing year and supporting evidence.
- Uploading an unindexed document dump. In Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition, this can distort the record or cause the taxpayer to choose the wrong procedural route. Correct it by tying the response to the exact order/notice, governing year and supporting evidence.
- Missing the distinction between an assessment year under the old act and a tax year under the 2025 act. In Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition, this can distort the record or cause the taxpayer to choose the wrong procedural route. Correct it by tying the response to the exact order/notice, governing year and supporting evidence.
- Making factual assertions that are not tied to contemporaneous evidence. In Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition, this can distort the record or cause the taxpayer to choose the wrong procedural route. Correct it by tying the response to the exact order/notice, governing year and supporting evidence.
- Assuming an adjournment request has been accepted before the portal/authority confirms it. In Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition, this can distort the record or cause the taxpayer to choose the wrong procedural route. Correct it by tying the response to the exact order/notice, governing year and supporting evidence.
Do not manufacture certainty
Some tax procedure questions cannot be answered from a section number alone. Authority, year, service, factual record, prescribed form, judicial developments and the exact relief sought can all matter. Where the record is incomplete, say what must be verified instead of filling the gap with a confident but unsupported assumption. Applied specifically to “Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition”.
Professional review checklist before submission
Frequently asked questions
What should I check first for Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition?
Start with Notice Authenticity And Din. Then lock the relevant period and facts before selecting a form, rate, accounting treatment or action.
What is the current 2026 position?
The practical answer: How to read and respond to a notice under section 142(1) for earlier assessment years while recognising the 2025 Act transition for Tax Year 2026-27 onward.…
Which facts can change the result?
The key change-points include whether notice authenticity and din, whether assessment year vs tax year, and whether information actually called for. Document any fact that could reverse the conclusion.
Which records should be retained?
For Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition, keep the underlying transaction records, calculation or reconciliation working, and filing/acknowledgement evidence. Retain the final approval, filing or acknowledgement and any later correction trail relevant to this topic.
What is a practical execution sequence?
A controlled sequence is to step 1. download and archive the complete notice/order and record its din/reference, authority, section, year, service date and stated deadline, then step 2. classify the issue behind “income tax notice section 142 demand”: identify the actual statutory proceeding rather than relying on the keyword label, and finally step 3. determine whether the income-tax act, 1961 or income-tax act, 2025 governs the year/proceeding; where a special law applies, map that law separately. The working should be reproducible by a reviewer.
What common error should be avoided?
A frequent error is replying only by informal email when the notice requires e-proceedings. in section 142(1) income-tax notice: documents, response & 2026 transition, this can distort the record or cause the taxpayer to choose the wrong procedural route. correct it by tying the response to the exact order/notice, governing year and supporting evidence. Another is uploading an unindexed document dump. in section 142(1) income-tax notice: documents, response & 2026 transition, this can distort the record or cause the taxpayer to choose the wrong procedural route. correct it by tying the response to the exact order/notice, governing year and supporting evidence. Both can create a technically neat but legally unsupported result.
How should the conclusion be reviewed?
For Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition, the reviewer should trace the conclusion back to the current primary source, the underlying evidence and the computation or reconciliation. Open assumptions and mismatches should be recorded explicitly.
When is professional advice appropriate?
Obtain transaction-specific professional advice where Section 142(1) Income-tax Notice: Documents, Response & 2026 Transition involves material amounts, cross-border facts, disputed interpretation, regulatory exposure, litigation risk or facts that do not fit the standard case described here.
Key takeaways
- Translate “income tax notice section 142 demand” into the correct statutory proceeding before acting.
- In 2026, always run the old-Act/new-Act governing-year test.
- Use an issue-wise evidence file rather than a narrative-only response.
- Protect limitation independently from requests for adjournment, rectification, stay or instalments.
- Preserve a complete electronic audit trail of what was served and what was filed.
Primary and authoritative sources
Income Tax Department, Government of India. Governing provisions of the Income-tax Act, 2025 and transition framework. Checked 13 September 2026.
Central Board of Direct Taxes / Gazette of India. Prescribed rules and forms effective from 1 April 2026. Checked 13 September 2026.
Central Board of Direct Taxes / Gazette of India. Form 119 and Rule 197 for DRC applications under section 379. Checked 13 September 2026.
Official source used for the legal/regulatory position in this article. Checked 13 September 2026.
Income Tax Department, Government of India. Viewing/responding to notices, partial/full responses, attachment handling, acknowledgements and adjournment. Checked 13 September 2026.
Income Tax Department, Government of India. Official transition guidance for old/new forms, including Form 97/98, Form 128, Form 145/146, tax audit forms and simultaneous old/new portal support. Checked 13 September 2026.
Official source used for the legal/regulatory position in this article. Checked 13 September 2026.