DuPont analysis decomposes return on equity into operating profitability, asset efficiency and financial leverage. It helps boards distinguish genuine operating improvement from ROE increased mainly by leverage or shrinking equity.
Finin2min takeaway
- Classify before computing.
- Use the law/regulation in force for the actual transaction or process date.
- Separate legal, tax, accounting and cash-flow conclusions.
- Reconcile every material conclusion to evidence and the filed output.
1. Overview — what exactly are we analysing?
DuPont analysis decomposes return on equity into operating profitability, asset efficiency and financial leverage. It helps boards distinguish genuine operating improvement from ROE increased mainly by leverage or shrinking equity.
This version focuses on mechanics, computation, evidence and worked examples. For DuPont Analysis: Board-Ready Framework with Practical Example, the objective is not to produce a one-line rate or checklist answer. The objective is to make the position reproducible: another reviewer should be able to identify the legal event, apply the current rule, rebuild the calculation and trace the result into the relevant return, form, register, financial statement or board paper.
What makes this topic difficult?
For DuPont Analysis: Board-Ready Framework with Practical Example, the difficult part is linking model purpose and source data to formula architecture and then proving the result through income statement. A commercially similar transaction can produce a different outcome when the profile-specific facts change. The first failure mode to guard against is using a generic label instead of the legally relevant DuPont Analysis classification, so this guide starts with classification and evidence rather than a headline percentage.
2. Current framework — 5 September 2026
Current-position note for DuPont Analysis: Board-Ready Framework with Practical Example. A decision-grade financial model should state its purpose, valuation/reference date, currency, units, source data and scenario assumptions before producing an output. Debt schedules, covenants, WACC/CAPM, beta, terminal value and market-multiple analyses should preserve the bridge from source evidence to formula to sensitivity to decision. Accounting numbers and valuation inputs may differ for legitimate reasons, but the model should explain every bridge and avoid false precision.
Use a consistent three-step or extended DuPont definition across periods and peers. This point is the first technical checkpoint because a wrong classification at this stage contaminates every later calculation. For DuPont Analysis: Board-Ready Framework with Practical Example, that means the computation file should show the classification step separately from the amount calculation.
Reconcile net margin to audited profit and identify one-offs/tax effects that distort recurring profitability. In practice, finance teams often discover this issue only during return preparation or diligence; the better control is to resolve it when the transaction is designed. If the fact changes, the team should rerun the conclusion rather than preserve the old answer for convenience.
Use average assets and equity where balances change materially during the period. The supporting memo should state the factual assumption that makes the rule relevant and identify the document that proves that assumption. The practical consequence is that the same source fact can produce a different legal, tax, accounting or valuation result when the governing classification or measurement basis changes.
Separate operating asset turnover from leverage effects; asset-light models can look very different from capital-intensive peers. A reviewer should be able to reproduce the conclusion from the source records without relying on a management explanation or a spreadsheet note. This is also where audit defence is won: consistent contracts, registers, bank evidence and filed forms are stronger than a later explanatory note.
Flag ROE improvement caused by buybacks, impairments or higher debt so management does not mistake balance-sheet contraction for operating progress. Where a contract, ledger, model or business label uses broad terminology, the analysis should translate it into the topic-specific legal, tax, accounting or valuation concept before applying a rate, formula or filing rule. The article therefore treats this as a decision rule, not as a generic caution.
For DuPont Analysis: Board-Ready Framework with Practical Example, where an older circular, precedent, section number or accounting policy is relevant to an earlier period, keep it in the chronology but label it as historical. The current-period analysis should not silently mix two regimes.
3. Detailed mechanics
Computation and evidence focus
This version focuses on mechanics, computation, evidence and worked examples. For DuPont Analysis: Board-Ready Framework with Practical Example, start with the legal event and transaction date, then build a source-to-output bridge. The computation should show opening position, event-specific movement, tax/accounting/regulatory classification, amount recognised, closing position and the exact return/form/register where the outcome is reported.
For DuPont Analysis: Board-Ready Framework with Practical Example, a reviewer should be able to select any material number and trace it backwards to the governing rule and source document. Where the answer is conditional, show both the base case and the fact that would flip the result. This is more useful than a single “applicable/not applicable” conclusion because it tells the finance team what to monitor before filing.
How the mechanics should be documented
For DuPont Analysis: Board-Ready Framework with Practical Example, create a transaction sheet with six columns: legal event, date, party/status, source document, rule relied on and amount/result. This prevents the common problem where the amount is correct but the legal reason is missing, or the legal memo is correct but the underlying amount is pulled from the wrong ledger. Add a seventh column for the person responsible for the next action.
For DuPont Analysis: Board-Ready Framework with Practical Example, create a reconciliation bridge that begins with the source system or legal register and ends with the statutory output. Differences should be explained, not manually forced to zero. In this article, the bridge may need to distinguish operating forecast, debt and cash-flow schedules, accounting carrying amounts, valuation inputs, enterprise value, equity value and decision-case outputs. The working should state the purpose, date and source of each value so a legitimate difference is not mistaken for an error — and an actual mismatch is not hidden as a “valuation difference”.
Practitioner deep dive — five topic-specific checkpoints
Technical checkpoint 1
Use a consistent three-step or extended DuPont definition across periods and peers. For DuPont Analysis: Board-Ready Framework with Practical Example, this checkpoint should be resolved before the team moves to "define the exact DuPont Analysis event and valuation/reporting date". The working paper should identify the exact fact being tested, the date on which that fact is measured, and the source record used to support it. A useful evidence anchor here is income statement. If that record points in a different direction from the spreadsheet or commercial summary, the legal classification should be reconsidered before any number is carried into a return, model or statutory form.
Computation consequence. The failure mode to test is using a generic label instead of the legally relevant DuPont Analysis classification. Do not solve that risk by inserting a balancing figure. Instead, rebuild the bridge from source fact → applicable rule → amount/character → reporting destination. For DuPont Analysis: Board-Ready Framework with Practical Example, the calculation file should preserve both the original source amount and every adjustment, allocation, valuation or classification step applied to it. This lets a reviewer distinguish a genuine legal adjustment from an unexplained spreadsheet difference.
Technical checkpoint 2
Reconcile net margin to audited profit and identify one-offs/tax effects that distort recurring profitability. For DuPont Analysis: Board-Ready Framework with Practical Example, this checkpoint should be resolved before the team moves to "collect the governing contract, statement and statutory evidence for DuPont Analysis". The working paper should identify the exact fact being tested, the date on which that fact is measured, and the source record used to support it. A useful evidence anchor here is average asset schedule. If that record points in a different direction from the spreadsheet or commercial summary, the legal classification should be reconsidered before any number is carried into a return, model or statutory form.
Computation consequence. The failure mode to test is using stale law, circulars, scheme terms or dates for DuPont Analysis. Do not solve that risk by inserting a balancing figure. Instead, rebuild the bridge from source fact → applicable rule → amount/character → reporting destination. For DuPont Analysis: Board-Ready Framework with Practical Example, the calculation file should preserve both the original source amount and every adjustment, allocation, valuation or classification step applied to it. This lets a reviewer distinguish a genuine legal adjustment from an unexplained spreadsheet difference.
Technical checkpoint 3
Use average assets and equity where balances change materially during the period. For DuPont Analysis: Board-Ready Framework with Practical Example, this checkpoint should be resolved before the team moves to "classify the transaction before computing any amount". The working paper should identify the exact fact being tested, the date on which that fact is measured, and the source record used to support it. A useful evidence anchor here is average equity schedule. If that record points in a different direction from the spreadsheet or commercial summary, the legal classification should be reconsidered before any number is carried into a return, model or statutory form.
Computation consequence. The failure mode to test is mixing commercial value with statutory, tax, accounting or regulatory value. Do not solve that risk by inserting a balancing figure. Instead, rebuild the bridge from source fact → applicable rule → amount/character → reporting destination. For DuPont Analysis: Board-Ready Framework with Practical Example, the calculation file should preserve both the original source amount and every adjustment, allocation, valuation or classification step applied to it. This lets a reviewer distinguish a genuine legal adjustment from an unexplained spreadsheet difference.
Technical checkpoint 4
Separate operating asset turnover from leverage effects; asset-light models can look very different from capital-intensive peers. For DuPont Analysis: Board-Ready Framework with Practical Example, this checkpoint should be resolved before the team moves to "build the calculation / reconciliation and a second-review check". The working paper should identify the exact fact being tested, the date on which that fact is measured, and the source record used to support it. A useful evidence anchor here is one-off adjustment memo. If that record points in a different direction from the spreadsheet or commercial summary, the legal classification should be reconsidered before any number is carried into a return, model or statutory form.
Computation consequence. The failure mode to test is losing lot-level, invoice-level, claim-level or facility-level reconciliation for DuPont Analysis. Do not solve that risk by inserting a balancing figure. Instead, rebuild the bridge from source fact → applicable rule → amount/character → reporting destination. For DuPont Analysis: Board-Ready Framework with Practical Example, the calculation file should preserve both the original source amount and every adjustment, allocation, valuation or classification step applied to it. This lets a reviewer distinguish a genuine legal adjustment from an unexplained spreadsheet difference.
Technical checkpoint 5
Flag ROE improvement caused by buybacks, impairments or higher debt so management does not mistake balance-sheet contraction for operating progress. For DuPont Analysis: Board-Ready Framework with Practical Example, this checkpoint should be resolved before the team moves to "map the conclusion to the correct return, register, filing or model output". The working paper should identify the exact fact being tested, the date on which that fact is measured, and the source record used to support it. A useful evidence anchor here is debt/equity bridge. If that record points in a different direction from the spreadsheet or commercial summary, the legal classification should be reconsidered before any number is carried into a return, model or statutory form.
Computation consequence. The failure mode to test is filing or modelling a number that cannot be traced back to source evidence. Do not solve that risk by inserting a balancing figure. Instead, rebuild the bridge from source fact → applicable rule → amount/character → reporting destination. For DuPont Analysis: Board-Ready Framework with Practical Example, the calculation file should preserve both the original source amount and every adjustment, allocation, valuation or classification step applied to it. This lets a reviewer distinguish a genuine legal adjustment from an unexplained spreadsheet difference.
4. Decision workflow
For DuPont Analysis: Board-Ready Framework with Practical Example, each workflow step should have a named evidence owner. Finance may own the ledger, legal may own contract/approval status, tax may own classification/return treatment and secretarial/compliance teams may own statutory registers and filings. The hand-off points should be recorded because an ownerless spreadsheet is not a control.
5. Worked example
Illustrative worked example
Facts. Net margin is 8%, asset turnover 1.5x and equity multiplier 2.0x.
Analysis. DuPont ROE is 24%. The board should see that doubling leverage would raise ROE mechanically even if margin and asset efficiency do not improve.
Finin2min control. This DuPont Analysis: Board-Ready Framework with Practical Example example is deliberately simplified. In a live case, replace every illustrative assumption with the actual dates, amounts, classifications, source documents, approvals and filings relevant to this topic before relying on the result.
The DuPont Analysis: Board-Ready Framework with Practical Example worked example should be accompanied by a sensitivity note. Identify the profile-specific assumption most likely to change the result and show how the conclusion changes if it moves. The sensitivity should use the actual driver in this article — not a generic market variable — so management can monitor the fact that truly changes the legal, tax or model outcome.
6. Scenario analysis
| Scenario | What changes | Reviewer action |
|---|---|---|
| Base case | Core facts align with the intended legal route | Compute and report using the primary rule, with a clear source bridge. |
| Classification changes | One decisive fact changes — instrument, party, project use, resident status or process stage | Re-run the rule before changing only the numeric output. |
| Timing changes | All facts are same but transaction/allotment/default/completion date changes | Re-test the applicable law, rate, deadline and limitation/holding-period consequences. |
| Data mismatch | Commercial report differs from statutory register/return/bank record | Pause filing and reconcile the underlying records first. |
For DuPont Analysis: Board-Ready Framework with Practical Example, scenario analysis is a control for conditional law and model sensitivity rather than forecasting theatre. The scenario table should identify the fact that must be watched, the evidence that proves a change, and the action that follows when the fact crosses from the base case into an exception.
7. Documentation and audit trail
Core evidence file
- income statement
- average asset schedule
- average equity schedule
- one-off adjustment memo
- debt/equity bridge
- peer DuPont dashboard
Evidence standards
- Use final signed/executed documents, not only drafts.
- Preserve the version of valuations and models actually approved.
- Keep bank/portal acknowledgements and not just screenshots.
- Reconcile dates across agreement, ledger, register and filing.
- Record reviewer name/date and unresolved assumptions.
- Archive the current primary-source rule relied on.
For high-value or litigated DuPont Analysis: Board-Ready Framework with Practical Example matters, add a chronology and an issues index. The chronology should be factual and date-based; the issues index should state the rule, management position, contrary evidence and remediation owner. This makes future assessment, diligence or dispute work materially faster.
Evidence-to-conclusion matrix for DuPont Analysis: Board-Ready Framework with Practical Example
Use this DuPont Analysis: Board-Ready Framework with Practical Example matrix as a file-index template. It links each source record to a process step and a known failure mode, so evidence is collected for a reason rather than archived as an undifferentiated document dump.
| Evidence | Decision step | Reviewer test | Red flag |
|---|---|---|---|
| income statement | define the exact DuPont Analysis event and valuation/reporting date | Reconcile income statement to the working used for define the exact DuPont Analysis event and valuation/reporting date; investigate dates, quantities, values and legal status before sign-off. | using a generic label instead of the legally relevant DuPont Analysis classification |
| average asset schedule | collect the governing contract, statement and statutory evidence for DuPont Analysis | Reconcile average asset schedule to the working used for collect the governing contract, statement and statutory evidence for DuPont Analysis; investigate dates, quantities, values and legal status before sign-off. | using stale law, circulars, scheme terms or dates for DuPont Analysis |
| average equity schedule | classify the transaction before computing any amount | Reconcile average equity schedule to the working used for classify the transaction before computing any amount; investigate dates, quantities, values and legal status before sign-off. | mixing commercial value with statutory, tax, accounting or regulatory value |
| one-off adjustment memo | build the calculation / reconciliation and a second-review check | Reconcile one-off adjustment memo to the working used for build the calculation / reconciliation and a second-review check; investigate dates, quantities, values and legal status before sign-off. | losing lot-level, invoice-level, claim-level or facility-level reconciliation for DuPont Analysis |
| debt/equity bridge | map the conclusion to the correct return, register, filing or model output | Reconcile debt/equity bridge to the working used for map the conclusion to the correct return, register, filing or model output; investigate dates, quantities, values and legal status before sign-off. | filing or modelling a number that cannot be traced back to source evidence |
| peer DuPont dashboard | archive evidence, assumptions, approvals and post-event monitoring | Reconcile peer DuPont dashboard to the working used for archive evidence, assumptions, approvals and post-event monitoring; investigate dates, quantities, values and legal status before sign-off. | ignoring a later amendment, contractual condition or event that changes the DuPont Analysis conclusion |
8. Risk controls and common mistakes
- using a generic label instead of the legally relevant DuPont Analysis classification
- using stale law, circulars, scheme terms or dates for DuPont Analysis
- mixing commercial value with statutory, tax, accounting or regulatory value
- losing lot-level, invoice-level, claim-level or facility-level reconciliation for DuPont Analysis
- filing or modelling a number that cannot be traced back to source evidence
- ignoring a later amendment, contractual condition or event that changes the DuPont Analysis conclusion
Most DuPont Analysis: Board-Ready Framework with Practical Example errors are not simple arithmetic errors. They arise when the right arithmetic is applied to the wrong legal bucket, a stale rule is used, a decisive date is missed, or commercial-system data is allowed to overwrite the statutory evidence trail. Controls should therefore target the specific risks listed above rather than merely recalculate the final total.
9. Professional review checklist
- Has model purpose and source data been resolved using the current framework for the actual transaction/process date?
- Can the conclusion be traced to income statement and average asset schedule?
- Has the team separately documented formula architecture and valuation/accounting consistency rather than assuming one answers the other?
- Are the dates needed for define the exact DuPont Analysis event and valuation/reporting date and collect the governing contract, statement and statutory evidence for DuPont Analysis supported by source records?
- Has the specific red flag “using a generic label instead of the legally relevant DuPont Analysis classification” been tested and closed?
- Do the working papers explain any difference among operating forecast, debt and cash-flow schedules, accounting carrying amounts, valuation inputs, enterprise value, equity value and decision-case outputs?
- Are the worked-example assumptions clearly separated from the actual DuPont Analysis: Board-Ready Framework with Practical Example fact pattern?
- Has a second reviewer checked the technical conclusion, arithmetic and evidence trail for DuPont Analysis: Board-Ready Framework with Practical Example?
For DuPont Analysis: Board-Ready Framework with Practical Example, a finance expert should review the economics and reconciliation; a tax/legal/secretarial professional should review the governing framework and filing; and the transaction owner should confirm that the factual assumptions used in the memo are actually true. The review is complete only when these perspectives agree on the same dated fact set and unresolved exceptions are explicitly assigned.
Updated analysis for Tax Year 2026-27: DuPont Analysis and Financial Ratios: Why ROE Can Mislead CFOs
Added and reviewed on 9 October 2026. This section adds worked examples and current-year controls to the guide above; where the two differ, follow the statute and the latest notification.
Three drivers behind one headline ratio
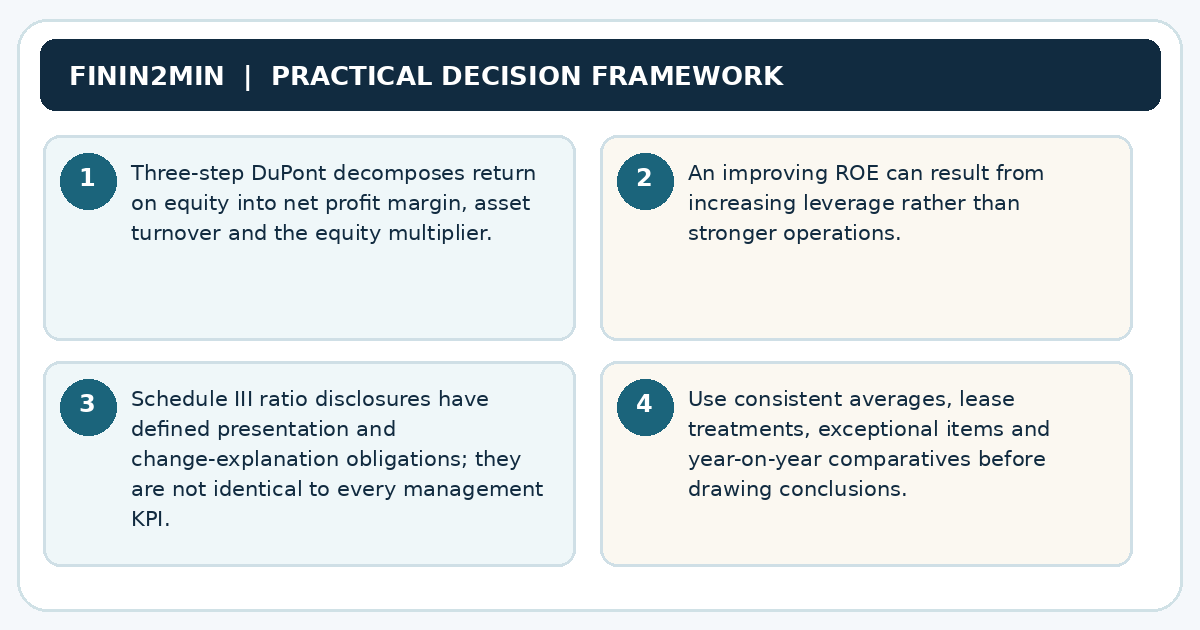
Return on equity measures profit relative to the ownership base, but does not describe why the figure moved. The three-factor DuPont formula is net profit margin × total asset turnover × equity multiplier, using compatible profit, sales, total assets and equity measures. Margin shows operating and financing quality translated into bottom-line earnings; turnover indicates how intensively assets create sales; the equity multiplier exposes financial leverage. The identities only work when numerator and denominator periods and definitions match. A ₹9-crore profit divided by ₹30-crore equity signals 30% ROE, but before celebrating a CFO should ask whether debt grew faster than operating productivity or whether one-off gains inflated the numerator.
Worked case: two companies with the same ROE
Company A earns ₹9 lakh net income from ₹90 lakh sales, holds ₹60 lakh average assets and ₹30 lakh average equity. Margin is 10%, turnover is 1.5 times and equity multiplier is 2: DuPont ROE equals 30%. Company B earns ₹6 lakh from ₹60 lakh sales, holds ₹60 lakh average assets and ₹20 lakh average equity. Margin is again 10%, turnover is 1 time and multiplier is 3, still 30% ROE. An investor or banker should not conclude these companies are equally efficient. A’s operations turn assets faster; B depends on a larger leverage multiplier and could face greater stress if finance costs or cash collections deteriorate.
Expand DuPont when finance cost and tax matter
A five-factor variation splits profitability into tax burden, interest burden, operating margin, asset turnover and financial leverage. Use profit before tax, EBIT and revenue definitions that match the chosen bridge. It can expose a profit jump caused by lower tax expense or a financing restructuring rather than higher unit economics. When a company has material other comprehensive income, extraordinary-like one-offs or discontinued operations, check whether net income captures the appropriate continuing performance. Ratio charts should show each factor and its year-to-year movement, ideally using actual audited comparatives. A company with a negative equity base or deep losses needs special treatment: a mathematically large positive ROE may be meaningless.
Add liquidity, cash conversion and coverage ratios
The full financial dashboard needs operating cash-flow conversion, current ratio, quick ratio, inventory days, receivable days, payable days, debt-equity and debt service coverage. Higher receivable turnover usually indicates faster collection, but changes in credit policy, factoring or seasonality can distort it. Debt service coverage should compare cash-generation or EBITDA-related measures with scheduled servicing according to a disclosed policy or lender covenant; do not combine different definitions within one time series. A strong profit margin with negative operating cash flow may signal a weak collections process. When inventory turns abruptly, check stock-outs, product mix, valuation changes and year-end cut-off before labelling management as efficient.
Schedule III disclosure duties differ from management analytics
The MCA Schedule III amendments enumerate eleven statutory ratios and expect numerator-denominator explanations and reasons for ratio changes exceeding 25% compared with the prior year. A banker may define adjusted EBITDA, net debt or DSCR differently from the financial statement note. Present one bridge linking the mandated statutory disclosures, credit covenant definitions and internal management metrics. Record the reference period and use average balance-sheet metrics for operational comparisons where suitable. If the reporting note uses end-year values under a specified method, explain that method instead of silently substituting a more flattering average. Comparability outweighs the appeal of a perfect-looking dashboard.
Scenario analysis: leverage boost versus real profitability
Imagine Company B issues new debt to fund an asset purchase, increasing the equity multiplier from 3 to 4 while margin and asset turnover remain unchanged. Mechanical ROE rises from 30% to 40%, but future financing costs, covenants and repayment obligations could reduce net income and strain liquidity. Run a sensitivity showing 1% lower gross margin, 20 additional debtor days and a higher borrowing rate. Then compute interest coverage and DSCR alongside ROE. The business decision should be based on return on invested capital relative to capital cost and free cash generation, not a target ROE engineered through thin equity.
Practical ratio dashboard controls
Maintain a data dictionary for each KPI, with definitions, units, period, inclusion of exceptional items and whether the source is consolidated or standalone. Run numerator and denominator checks that tie to signed statements. Flag negative denominators, zero equity, unrepresentative one-off balances and inconsistent comparison periods. For a diversified group, add segment reporting and capital-employed views to avoid profitable divisions hiding under a weak consolidated figure. Explain meaningful movements in ordinary language: what caused them, whether they are temporary and what operating response management intends. A clear ratio analysis is a decision brief, not a collection of coloured gauges.
Practitioner checklist
- Reconcile numerator/denominator to financial statements.
- Identify operating, tax and leverage sources of ROE.
- Include statutory Schedule III ratio disclosures.
- Test debt covenants and cash conversion alongside profitability.
- Flag negative equity and one-off distortions.
Questions readers ask
What are the three DuPont components?
Net profit margin, total asset turnover and equity multiplier.
Can debt raise ROE?
Yes, higher leverage can raise the multiplier, but increases financial risk.
What is the difference between ROE and ROIC?
ROIC examines return on invested capital, generally before capital-structure effects, while ROE focuses on shareholders.
Does Schedule III require ratio movement explanations?
It requires explanations for changes of more than 25% from the preceding year under its disclosure framework.
Should average equity be used?
Average balances can improve analytical representativeness; disclose chosen methodology consistently.
Why might negative equity make ROE unusable?
A negative denominator can reverse the sign and produce an economically misleading ratio.
Official sources for this update
- MCA - Schedule III Amendment Notification GSR 207(E), 24 March 2021
- ICAI - Compendium of Indian Accounting Standards (2025-2026)
Related reading on Finin2min
10. Frequently asked questions
What is the first question to ask?
Start with model purpose and source data for DuPont Analysis: Board-Ready Framework with Practical Example. A commercial label is not enough; identify the parties, the profile-specific legal/economic event, the decisive date and the governing regime before calculating or filing anything.
Which law should be cited for a 2026 transaction?
For DuPont Analysis: Board-Ready Framework with Practical Example, A decision-grade financial model should state its purpose, valuation/reference date, currency, units, source data and scenario assumptions before producing an output. Debt schedules, covenants, WACC/CAPM, beta, terminal value and market-multiple analyses should preserve the bridge from source evidence to formula to sensitivity to decision. Accounting numbers and valuation inputs may differ for legitimate reasons, but the model should explain every bridge and avoid false precision.
Can I rely only on a broker, ERP, portal or consultant report?
No. For DuPont Analysis: Board-Ready Framework with Practical Example, secondary reports are useful working evidence, but the final position should reconcile to the profile-specific source file — including income statement, average asset schedule — and to the current primary-source rule.
What if two values are different?
For DuPont Analysis: Board-Ready Framework with Practical Example, do not force them to match. First identify whether they answer different questions. In this pillar, the relevant bridge may involve operating forecast, debt and cash-flow schedules, accounting carrying amounts, valuation inputs, enterprise value, equity value and decision-case outputs. Label each value by purpose, valuation date and source, then document why the difference is legitimate or what correction is required.
What is the biggest practical error?
using a generic label instead of the legally relevant DuPont Analysis classification. The remedy is to resolve the classification and evidence before filing or closing.
How should I prepare for scrutiny or diligence?
For DuPont Analysis: Board-Ready Framework with Practical Example, maintain a dated technical memo and a file index that includes income statement, average asset schedule, average equity schedule. Preserve the calculation version, reviewer sign-off and the reconciliation from those source records to the statutory filing, model, board paper or financial statement that uses the conclusion.
Should the example be copied into my return or model?
No. The DuPont Analysis: Board-Ready Framework with Practical Example example demonstrates mechanics only. Replace each assumption with the actual dates, status, amounts and documents in your case, and re-check the current rule before using the result in a return, model, filing or decision memo.
When should the analysis be refreshed?
Refresh the DuPont Analysis: Board-Ready Framework with Practical Example analysis whenever a fact affecting model purpose and source data, formula architecture or valuation/accounting consistency changes, or when the applicable law/regulation, approval status, transaction date or source evidence is updated.
11. Primary sources and validation basis
This article is anchored to primary/regulator material. Always check later amendments, notifications, circulars and transaction-specific facts before acting.
Disclaimer: This DuPont Analysis: Board-Ready Framework with Practical Example guide is for general educational information and does not constitute legal, tax, accounting, investment or financial advice. Transaction-specific positions may differ based on facts, dates, jurisdiction, documentation and later amendments. Obtain professional advice before acting.