Budgeting vs Forecasting vs Rolling Forecast: A CFO's Framework
Reviewed by CA Nikhil Gupta · Last reviewed 9 October 2026
"What's our forecast?" means three different things depending on who's asking and when. Budgets, forecasts and rolling forecasts answer different questions, run on different cycles, and get confused constantly — usually right before a board meeting. Here's how to keep them straight.
Three Tools, Three Questions
| Tool | Question It Answers | Frequency | Horizon | Changes During the Year? |
|---|---|---|---|---|
| Budget | "What did we commit to deliver?" | Annual | Fixed fiscal year (12 months) | No — used as the fixed benchmark |
| Forecast | "What do we now expect for the rest of the year?" | Quarterly (typical) | Remainder of fiscal year (shrinks over time) | Yes — re-estimated each cycle |
| Rolling Forecast | "What does the next 12-18 months look like, always?" | Monthly or quarterly | Constant 12-18 months (rolls forward) | Yes — continuously extended |
The budget is your contract with the board. The forecast is your best current estimate against that contract. The rolling forecast is your radar — it never lets the planning horizon shrink to zero just because March is approaching.
Why "Forecast Shrinkage" Is a Problem
In a traditional quarterly re-forecast model, by Q4 your "forecast" only covers the next 1-3 months — you've effectively stopped planning. Decisions that need 6-9 months of lead time (hiring, capex approvals, inventory positioning for the next festive season) get made with no forward visibility, right when they matter most.
A rolling forecast solves this by always adding a new period at the far end as the current period closes. If you're on a monthly rolling 12-month forecast, the moment April closes, you drop April from the model and add the following March — the horizon never shrinks below 12 months.
Zero-Based vs Incremental Budgeting
| Incremental Budgeting | Zero-Based Budgeting (ZBB) | |
|---|---|---|
| Starting point | Last year's actual/budget | Zero — every line re-justified |
| Effort | Low — apply a growth % | High — every cost centre builds up from activity drivers |
| Typical use | Annual cycle, most years | Periodic deep-dive (every 3-5 years) or after a major change (new CFO, post-acquisition, turnaround) |
| Risk | Perpetuates inefficiencies — "we've always spent this much on X" | Time-intensive; can create internal friction if not change-managed well |
| Typical first-cycle savings | 0% (by design) | 5–15% of addressable costs |
A practical middle ground used by many Indian mid-market companies: run ZBB on discretionary/overhead cost lines (travel, admin, marketing, professional fees — typically 15-25% of total cost base) every 2-3 years, and incremental budgeting on the rest (statutory costs, contracted rentals, committed headcount).
Variance Analysis — Where Budget Meets Reality
Every month, FP&A compares Actuals vs Budget (and increasingly, Actuals vs Latest Forecast). The standard decomposition for revenue/cost variances:
- Volume variance: Impact of selling more/fewer units than budgeted, at budgeted price/cost
- Price/Rate variance: Impact of actual price/cost differing from budgeted price/cost, at actual volume
- Mix variance: Impact of selling a different proportion of high-margin vs low-margin products than assumed
- FX variance: For businesses with import/export exposure — impact of currency movement vs the budget rate
| Metric | Budget | Actual | Variance | Driver |
|---|---|---|---|---|
| Units Sold | 10,000 | 10,800 | +8% (Favourable) | Volume — stronger demand |
| Avg Realised Price | ₹1,000 | ₹950 | -5% (Unfavourable) | Price — discounting to drive volume |
| Revenue | ₹1.00 Cr | ₹1.026 Cr | +2.6% (Favourable, net) | Volume gain > price erosion |
Reporting revenue variance alone (+2.6%) hides the story — discounting drove the result, not demand at full price. Decomposing into volume and price variance is what turns a variance report into a management decision: is this discount strategy sustainable, or is it eroding margin for vanity volume?
A Practical Cadence for Indian Mid-Market Companies
- Annual Budget: Set 2-3 months before fiscal year start (Jan-Mar for an April-start year). Locked once board-approved.
- Quarterly Forecast Refresh: Updated full-year view at end of Q1, Q2, Q3 — compares to budget, explains variance, revises full-year expectation.
- Monthly Rolling 12-Month Cash Forecast: Operational tool, separate from the P&L budget — see our Working Capital CFO Playbook for the cash flow drivers that feed this.
- ZBB Deep-Dive: Every 3-5 years, or triggered by a CFO change, M&A integration, or margin-pressure event.
2026 Accuracy & Decision Check
Turn Budgeting vs Forecasting vs Rolling Forecast: A CFO's Framework into a reconciled management decision, not a dashboard number
A CFO-grade answer states the definition, data source, formula/accounting treatment, period, owner and decision threshold. It then reconciles the metric to financial statements or source systems and tests a downside case. This prevents a KPI, valuation or budget from looking precise while being driven by hidden assumptions.
Decision / evidence controls
- Define numerator/denominator and accounting perimeter.
- Tie source data to ledger/bank/contract or audited reporting.
- Run base, downside and liquidity cases.
- Record owner, review frequency and action threshold for each metric.
Primary-source checks
Updated analysis: Rolling Forecast for CFOs: 12-Month Driver Model, Cash and Scenario Rules
Added and reviewed on 9 October 2026. This section adds worked examples and current-year controls to the guide above; where the two differ, follow the standard text and the latest notification.
Finin2min two-minute summary
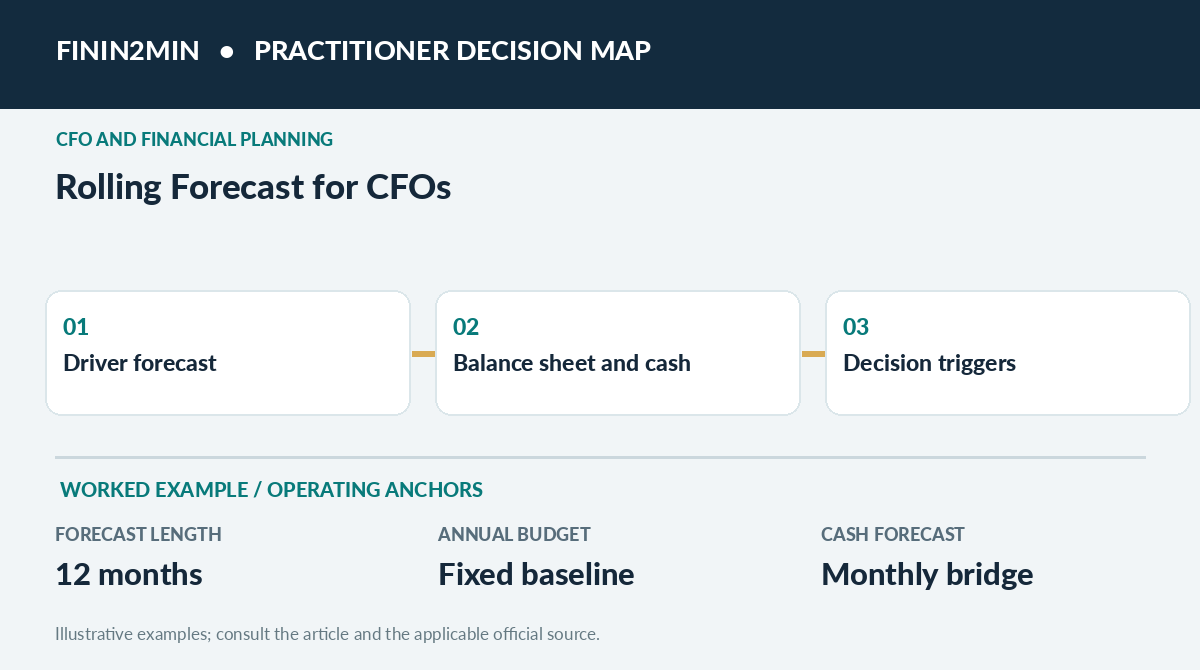
- A rolling forecast always maintains a forward-looking horizon: at each close it adds one future period instead of only shrinking toward March.
- The board-approved annual budget remains the accountability baseline. A forecast is the best current estimate, not a rewritten performance target.
- Build revenue, margin, payroll, inventory, receivables, payables, capital expenditure and taxes from operational drivers rather than applying the same growth percentage everywhere.
- A credible model reconciles P&L, balance sheet and cash flow; otherwise a profit forecast can hide a liquidity shortfall.
- Preserve version history, data cut-off, assumption owners, downside cases and decisions triggered by forecast changes.
At-a-glance reference table
| Driver | Forecast formula | Evidence |
|---|---|---|
| Sales | Units × realisation, less returns | Orders and pricing |
| Debtors | Opening + credit sales − collections | Receivables ageing |
| Stock | Opening + receipt − usage/dispatch | WMS and production |
| Cash | Opening + receipts − payments | Bank and treasury |
Fixed budget, periodic forecast and rolling horizon
An annual budget asks what management originally committed to deliver. A quarter-end forecast asks what the current year will probably produce. A rolling 12-month forecast asks what is likely over the coming twelve months from any reporting date, with a fresh month added each cycle. These tools are complementary. If the finance team overwrites the board budget every time sales change, it destroys the variance benchmark and weakens accountability.
Choose the horizon for the decision. A trading business might use a weekly 13-week cash forecast for liquidity and a monthly rolling 12-month forecast for operating plans. A heavy manufacturer making eighteen-month machinery commitments may require a longer horizon. Do not interpret “rolling” as a claim that every item can be estimated with equal precision.
Design the driver tree before the spreadsheet
Revenue should be units × realisation or active customers × average revenue, with separate drivers for price, churn, returns and seasonality. Materials should follow production units, standard BOM, scrap and raw-material price. Staff cost should follow headcount, joining dates, annual increments, variable incentive and payroll burden. Operating expenses should distinguish committed contracts, usage-variable spend and discretionary projects.
Map the financial plan to cash timing. Sales recognised in November may not be collected until January if receivable terms are sixty days; materials purchased in October may be paid in December. Inventory replenishment may precede seasonal sales, and GST/other statutory settlements may occur at different dates from expense recognition. The resulting working-capital swings can dominate the liquidity projection.
A practical twelve-month revenue and cash illustration
Suppose a business closes September with monthly sales of ₹1 crore, a gross margin of 30% and receivables of ₹1.8 crore. Management expects volume growth of 2% monthly for the coming quarter but anticipates a five-per-cent price reduction from a new competitor. A sound model applies these drivers separately instead of projecting sales up by a neat 2% each month. The price cut may outweigh volume growth; use cohort or product-line estimates if different customers are affected.
For a simplified one-month example, assume sales ₹1.00 crore, collections ₹0.80 crore, material purchases paid ₹0.65 crore, payroll ₹0.18 crore and other cash operating payments ₹0.08 crore. Net operating cash movement before tax, financing and capex is negative ₹0.11 crore, even if the income statement reports positive gross margin. The point is not the selected figures but the separate linkage of billing, collections and supplier payment timing. The forecast must begin with actual bank balances and reconcile expected receipts to receivable ageing.
Build three connected statements
Forecast the P&L by product or profit centre, then generate receivables, inventories, payables, tax liabilities, borrowings and fixed assets on the balance sheet. Derive cash flow from opening cash plus operating movements, investing cash, financing cash and statutory payments. An unexplained “cash balancing” plug is evidence that the model is broken, not that it has balanced.
Use a monthly bridge for closing working capital: opening receivables + credit sales − collections − supported credits/adjustments = closing receivables. Similar stock and AP bridges expose timing mistakes. Reconcile the rolling model to the general ledger at each close, then lock actual months and push the horizon forward. The model should never reforecast actual invoices to match an optimistic plan.
Scenarios and triggers
A meaningful downside case changes drivers together: weaker sales may increase inventory days and receivable defaults even as management cuts spending. Model supplier-credit constraints, borrowing headroom, delayed customer approvals and essential capex. Under a stressed scenario, calculate the month cash first approaches a minimum operating threshold and the lead time for corrective actions.
Set decision triggers rather than merely red/amber/green charts. For example, if projected cash falls below two months of fixed operating payments, management reviews hiring, discretionary capex, collections and working-capital facilities. These thresholds are illustrative governance choices rather than universal finance standards. Name the person authorised to intervene and the meeting where the decision will be made.
Month-end FP&A operating rhythm
Within a defined close timetable, load actual P&L, bank cash, revenue cohorts, working-capital ageing and committed expenses. Ask commercial leaders to refresh pipeline probabilities, operations to update yield and inventory, HR to update approved hiring, and treasury to update debt and interest. Finance reconciles inputs, locks assumptions, tests model integrity and explains changes versus both prior forecast and annual budget.
The management pack should contain a waterfall from previous expected EBITDA to the new estimate, a cash bridge, three largest changed assumptions, downside liquidity and decisions required. Separate the impact of actual results from changes in the future outlook. A business that beat September budget but missed November order bookings needs a forward response, not celebratory reporting.
Avoid common forecast traps
Percent-of-sales for every balance sheet line can conceal terms and seasonality. A forecast based only on booked sales may ignore collections and GST obligations. Replacing an old forecast without an archived version makes forecast accuracy impossible to evaluate. An excessively complicated workbook without clear source owners can be less useful than a smaller auditable model with robust assumptions.
Questions readers ask
Does a rolling forecast replace the annual budget?
Usually not; they serve different planning and accountability purposes.
How does a rolling 12-month model work in October?
It projects the next twelve months and adds another month at each subsequent close.
Must a rolling forecast include cash?
For useful finance decision-making, yes; at least reconcile expected cash to the forecast balance sheet and liquidity drivers.
Should actual months ever be reforecast?
Lock them after closing, subject to properly documented accounting adjustments, and forecast the remaining periods.
Is one downside assumption enough?
Rarely. Revenue, margins, collections, inventory and funding often interact in stress.
How do you measure forecast quality?
Compare prior locked forecast versions with actual results by driver and horizon, then document persistent bias and corrective actions.
Official sources for this update
- ICMAI management accounting education
- ICMAI Paper 11 — Financial Management and Business Data Analytics (2026)
Related reading on Finin2min
Frequently Asked Questions
Source and review trail
Use the current official instrument, portal or regulator publication before acting.
- Primary category
- Corporate Finance & CFO
- Official starting point
- www.finmin.gov.in