Oil above $104, Nifty at an 18-month low: RBI tightening meets a major GST reform day
Daily Finance Intelligence | Markets | Crude | Bullion | FX | Rates | Macro | Tax | GST | SEBI | Compliance
2-Minute Summary
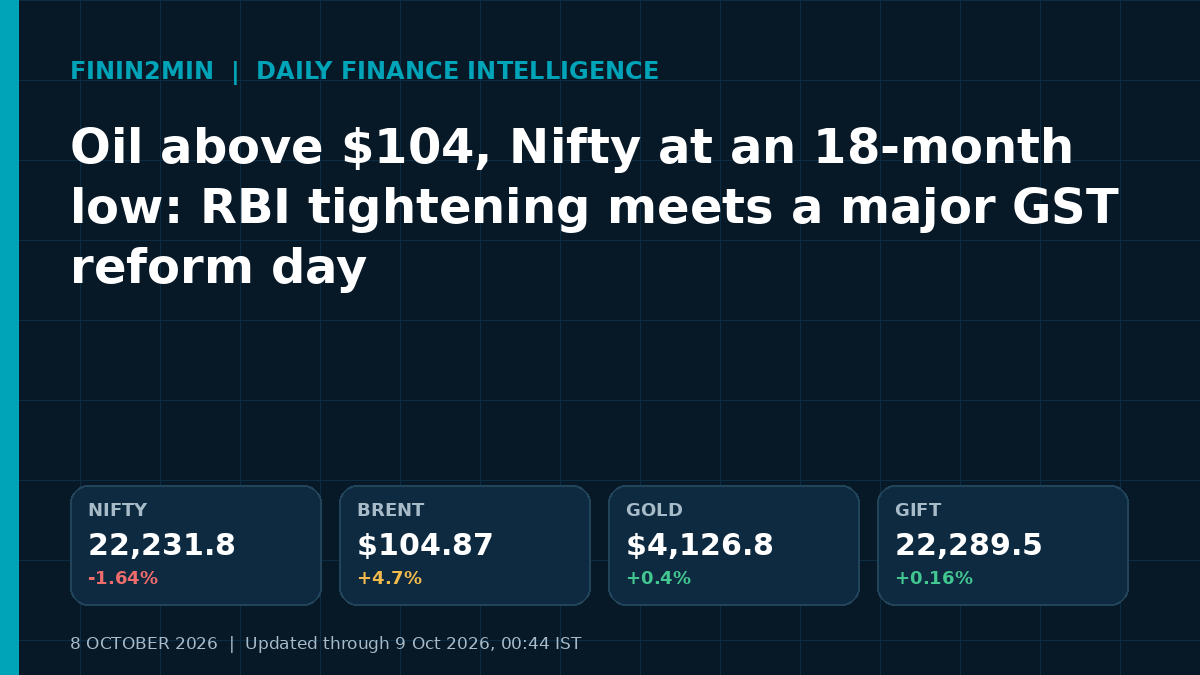
- Indian risk assets had a difficult 8 October: Nifty 50 closed at 22,231.80 (-1.64%), its lowest close in about 18 months, while Sensex ended at 71,593.24 (-1.44%). All 16 major sectors fell; mid- and small-caps lost more than 2%.
- Foreign selling intensified. Provisional combined NSE/BSE/MSEI cash data show FII/FPI net selling of Rs 12,943.58 crore versus DII net buying of Rs 10,703.11 crore - a large domestic cushion, but not enough to offset the risk-off session.
- Oil was the dominant global macro risk. A later Reuters market snapshot showed Brent at US$104.87/bbl (+4.7%) and WTI at US$92.30 (+4.6%). The drivers were Gulf shipping attacks, US Gulf production shut-ins and uncertainty around US-Iran negotiations.
- Gold steadied despite high yields: spot gold was US$4,126.78/oz (+0.4%) in US closing hours, while spot silver fell 1.9% to US$58.98/oz. The US 10-year yield was 5.305%, keeping the opportunity-cost pressure on bullion.
- The late-session Oct-26 GIFT Nifty reference was 22,289.50 at 23:33 IST, up 34.50 points (+0.16%) versus its own previous futures close. It stood only about 58 points above the Nifty cash close, so the signal was mildly positive rather than a strong gap cue.
- The rupee ended around 96.78 per US dollar, close to its record-low zone. High crude, elevated global yields and continued foreign selling remain the key transmission channels into imported inflation and domestic financial conditions.
- RBI has already moved: the repo rate is 5.50% after a 25-bp hike on 7 October, with the stance shifted to calibrated tightening. A Reuters poll now sees September CPI near 5.40% versus 4.82% in August; that is an estimate, not the official print.
- The 57th GST Council meeting produced a major compliance-reform package: recommended withdrawal of GST arrest powers, prosecution threshold raised to Rs 5 crore, general penalty reduced to Rs 10,000, broader ITC/refunds, more automated registration/refunds, and tighter standards for notices. These are Council recommendations; notifications, circulars and law amendments will determine legal effect.
- TCS opened the large-cap earnings season after market hours: Q2 revenue was US$7.642 billion, constant-currency sequential growth 0.5%, TCV US$9.6 billion and annualised AI revenue US$3.1 billion. The headline shows AI scaling quickly, while core discretionary IT demand remains selective.
Market Dashboard
| Indicator | Level | Move | Status |
|---|---|---|---|
| Nifty 50 | 22,231.80 | -1.64% | 8 Oct India close |
| Sensex | 71,593.24 | -1.44% | 8 Oct India close |
| FII/FPI cash | -Rs 12,943.58 cr | Net seller | 8 Oct provisional |
| DII cash | +Rs 10,703.11 cr | Net buyer | 8 Oct provisional |
| USD/INR | 96.78 | Nearly flat | 8 Oct close |
| GIFT Nifty Oct-26 | 22,289.50 | +34.50 / +0.16% | 8 Oct 23:33 IST |
| Brent | US$104.87/bbl | +4.7% | 8 Oct ~21:43 IST |
| WTI | US$92.30/bbl | +4.6% | 8 Oct ~21:43 IST |
| Spot gold | US$4,126.78/oz | +0.4% | 8 Oct 23:46 IST |
| Spot silver | US$58.98/oz | -1.9% | 8 Oct 23:46 IST |
| US 10Y | 5.305% | +2.8 bps | 8 Oct ~21:43 IST |
| S&P 500 | 7,753.82 | -0.61% | 8 Oct US mid-afternoon |
| Nasdaq | 27,160.19 | -1.37% | 8 Oct US mid-afternoon |
India close: oil, rates and foreign selling converge
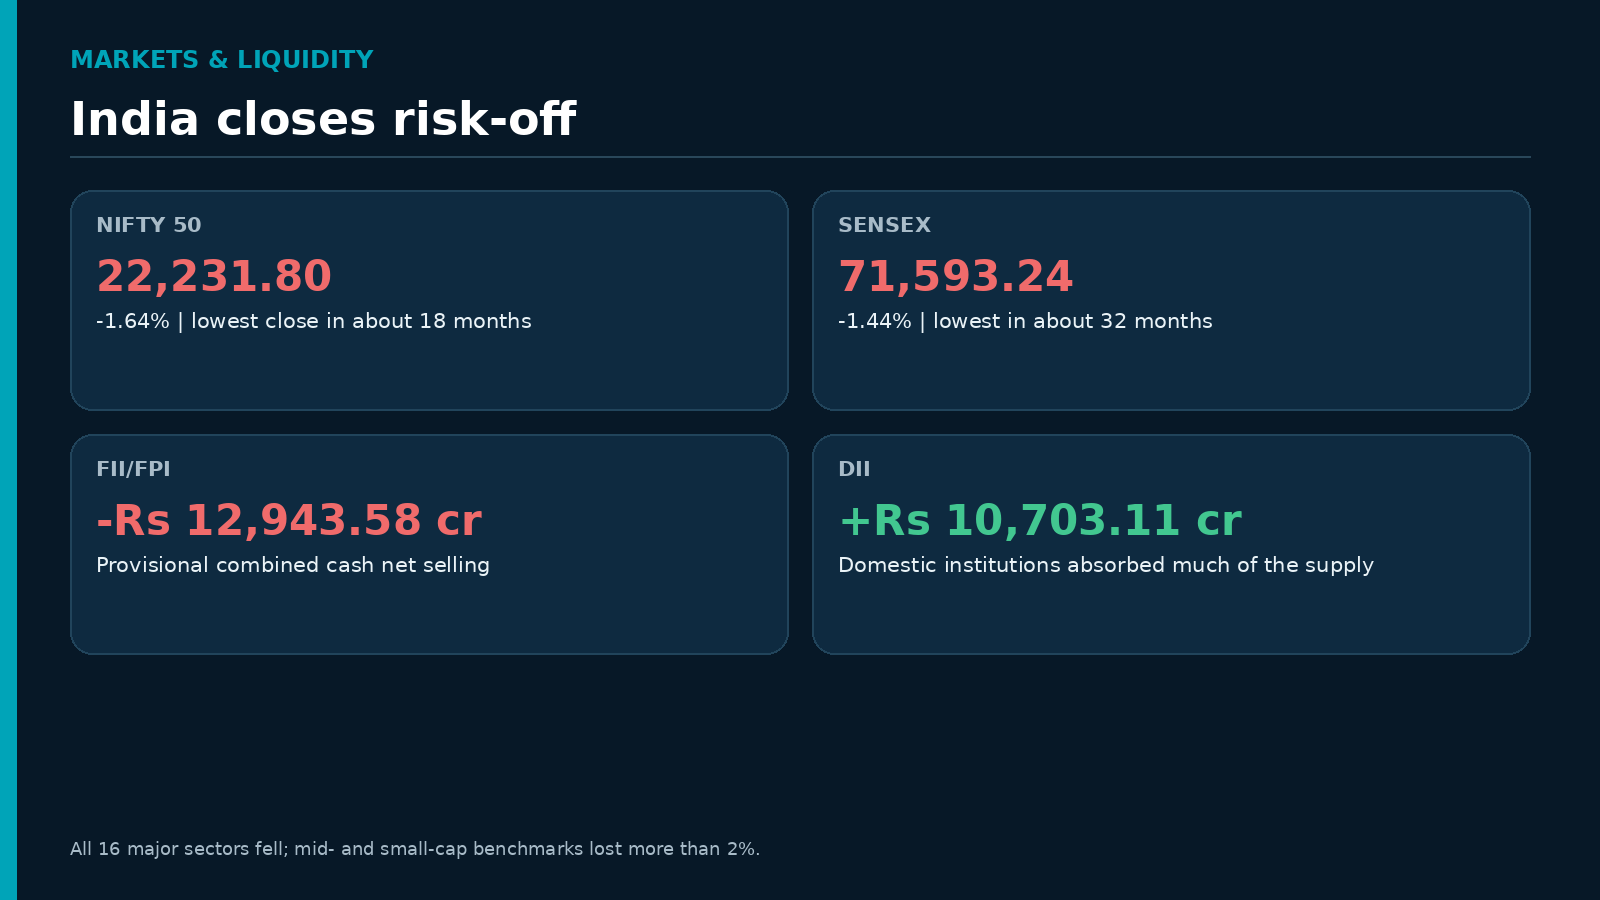
Indian equities absorbed several pressure points at once. Nifty 50 fell 1.64% to 22,231.80 and Sensex lost 1.44% to 71,593.24. All 16 major sectors declined, while small- and mid-cap benchmarks lost more than 2%.
Provisional combined NSE/BSE/MSEI cash data show FII/FPI net selling of Rs 12,943.58 crore and DII net buying of Rs 10,703.11 crore. High oil, a weak rupee, rising global yields and foreign selling combined into a cross-asset macro squeeze.
Crude, gold and silver

A later Reuters market snapshot showed Brent at US$104.87/bbl (+4.7%) and WTI at US$92.30 (+4.6%). These are intraday references, not settlements. Supply risk came from Hormuz shipping attacks, US Gulf shut-ins and uncertainty around Iran-US talks.
In US closing hours, spot gold was US$4,126.78/oz (+0.4%) while spot silver was US$58.98/oz (-1.9%). The US 10-year yield was 5.305%, keeping a strong opportunity-cost headwind on bullion.
GIFT Nifty: mildly positive, not a gap guarantee

The Oct-26 GIFT Nifty future was 22,289.50 at 23:33 IST, up 34.50 points (+0.16%) versus its own previous futures close. It was only about 58 points above the Nifty cash close, so the late-session signal was mildly positive rather than a strong opening-gap cue.
RBI, rupee and inflation

The rupee ended around 96.78 per US dollar, close to its record-low zone. RBI raised the repo rate to 5.50% on 7 October and shifted to calibrated tightening. A Reuters poll estimated September CPI at 5.40%; the official CPI release is still awaited.
57th GST Council: a major process-reform package

The Council recommended withdrawal of GST arrest powers, a higher Rs 5 crore prosecution threshold, a lower Rs 10,000 general penalty, broader ITC/refund eligibility, more system-based registration/refunds and stronger standards for notices and transit interception.
Return reconciliation reforms are proposed from the return of April 2027; selected inverted-duty input-service ITC refunds are recommended for ITC availed on/after 1 November 2026; and specified capital-goods refund eligibility is proposed for ITC availed on/after 1 April 2027.
Tax, SEBI, IBC and payments

For specified AY 2026-27 audit cases, the current operative dates remain 21 October 2026 for the audit report and 21 November 2026 for the corresponding ITR. SEBI issued three debt-market circulars on 7 October covering Credit Risk-o-Meter disclosure, a merchant-banker exemption for certain private placements and ISIN provisions.
MCA reported 107 NCLT resolution-plan approvals in Q2 FY2026-27. On UPI, Reuters reported a possible delay in the proposed 0.4% merchant fee on certain transactions above Rs 2,000; a final NPCI decision remained pending at the cutoff.
TCS Q2 FY27: AI scales, core demand remains measured
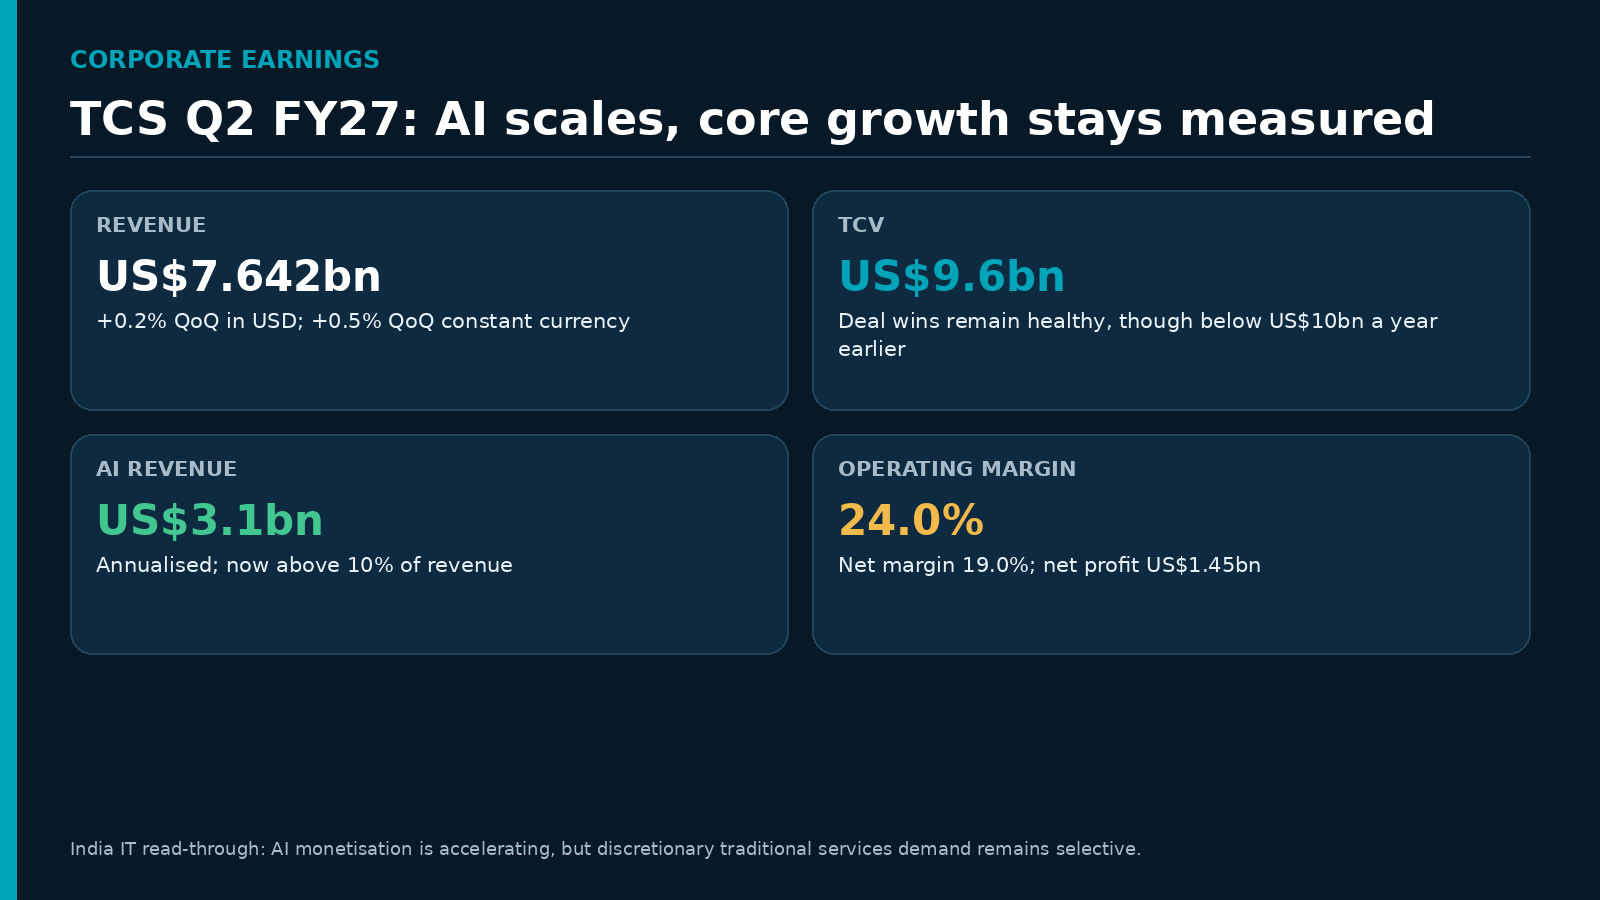
TCS reported US$7.642 billion of Q2 revenue, +0.5% sequential constant-currency growth, US$9.6 billion TCV and annualised AI revenue of US$3.1 billion. Operating margin was 24.0%. AI is becoming material, but traditional discretionary demand remains selective.
Global markets and what to monitor
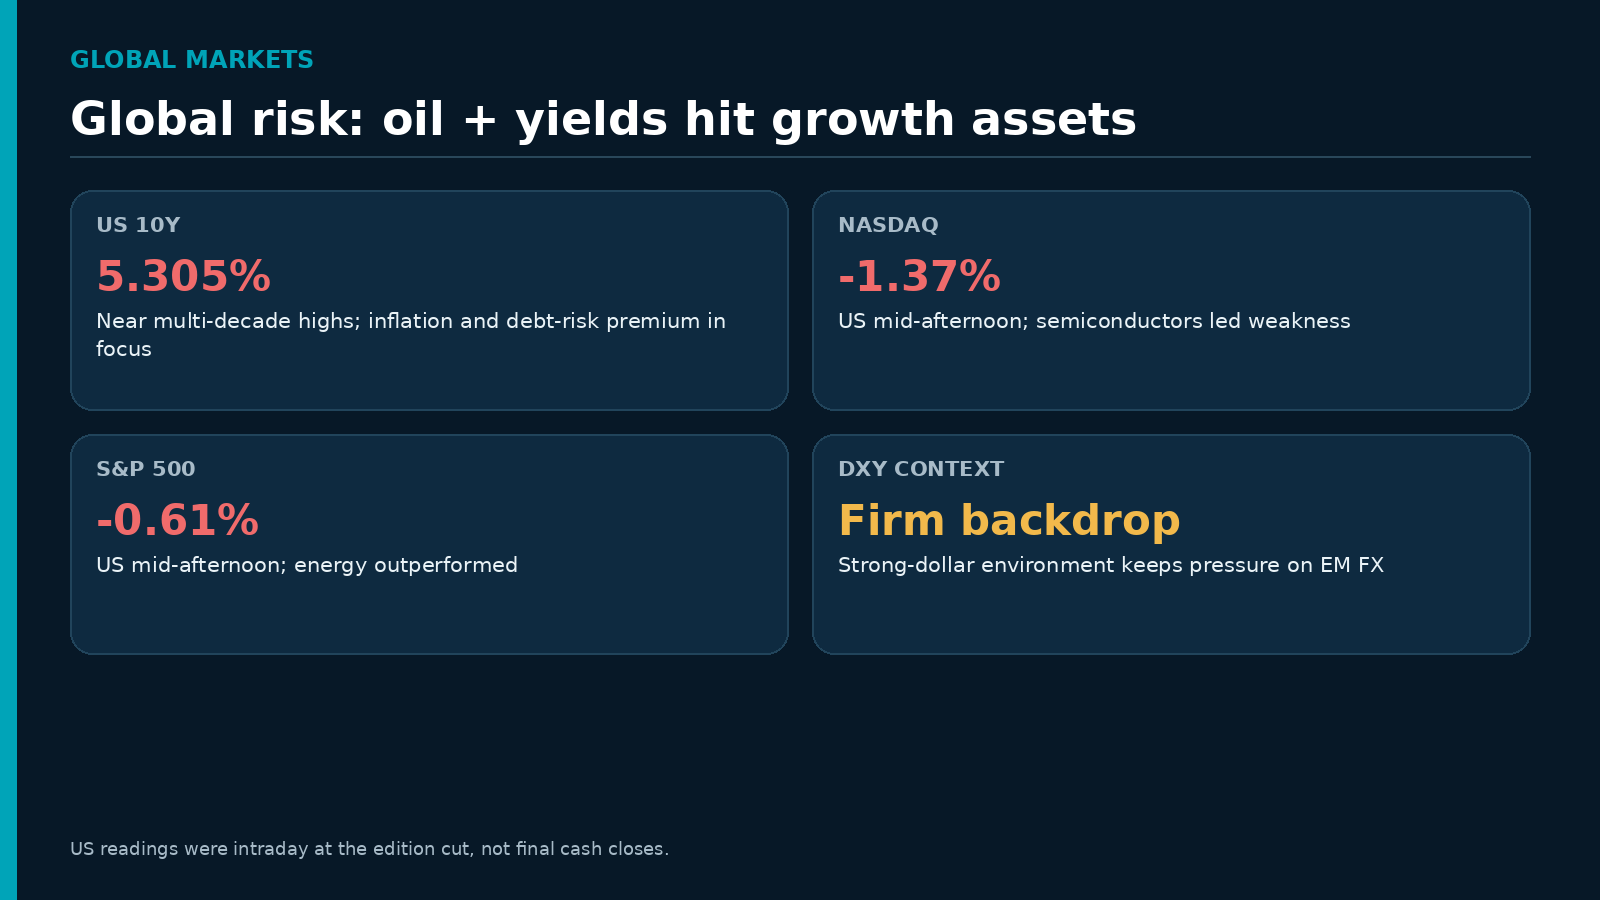
US stocks were still trading at the edition cut: Nasdaq -1.37%, S&P 500 -0.61% and Dow -0.07% in Reuters' mid-afternoon update. The next cross-asset checkpoints are crude above/below US$100, the rupee around 97, fresh GIFT Nifty before India opens, official September CPI, GST implementation instruments and the final UPI fee decision.
Reader note
Educational and informational content only. Not investment, tax or legal advice. Market prices and regulatory positions can change; readers should verify current applicability for their circumstances.
Sources
- Reuters - India equities / sector breadth / FPI context
- NSE India - FII / DII provisional cash flows
- Reuters - Rupee
- Reuters - Crude oil
- Reuters - Crude drivers / shipping / hurricane
- Reuters - Gold and silver
- LiveIndex - GIFT Nifty
- Reuters - Global equities
- Reuters - US rates
- Reuters - RBI policy
- Reuters - September CPI preview
- Press Information Bureau / Ministry of Finance - 57th GST Council
- Income Tax Department - Income-tax audit/ITR deadlines
- SEBI - SEBI debt-market circulars
- Reuters - UPI merchant-fee timeline
- Tata Consultancy Services - TCS Q2 FY27
- Reuters - TCS Q2 context
- Press Information Bureau / Ministry of Corporate Affairs - NCLT / IBC
- GST Portal - Routine GST return due-date reference