Rally broadens before RBI: Nifty +0.98%, oil holds near $100, gold/silver rise as yields ease
India extended its rebound, but the rupee stayed weak and foreign cash selling continued. The 7 October RBI decision, live GIFT Nifty, energy risk and global bond yields now define the next decision window.
Information cut: 7 October 2026, 01:13 IST
2-Minute Summary
- Indian equities extended their rebound: Nifty 50 closed at 22,776.10 (+0.98%) and Sensex at 73,067.81 (+0.95%). Fourteen of 16 major sectors advanced; small-caps rose 1.6% and mid-caps 1.1%.
- Flows improved but did not reverse: provisional FII/FPI cash selling moderated to Rs 2,961.30 crore while DIIs bought Rs 5,088.92 crore, leaving combined institutional cash flow positive by about Rs 2,127.62 crore.
- The rupee weakened to 96.42/$, its weakest in more than two months. The RBI repo rate remained 5.25% ahead of the 7 October MPC decision; Reuters reported likely RBI market operations helping contain FX/liquidity pressure.
- At 01:09:43 IST, the Oct-26 GIFT Nifty screen showed 22,780.50, +6.50 (+0.03%) in live Session 2. That is only about 4 points above the Nifty cash close, so it should be read as a near-flat futures cue, not a guaranteed opening gap.
- Crude settled almost unchanged: Brent at US$100.58/bbl (+0.3%) and WTI at US$89.44. Larger Middle East exports and the planned G7 emergency-stock release offset continuing Gulf security and weather risks.
- Bullion strengthened as the dollar and US yields eased: spot gold rose 0.7% to US$4,168.33/oz and silver 0.8% to US$61.56/oz; December US gold futures settled at US$4,187.10.
- India Services PMI improved to 55.2 and Composite PMI to 55.9 in September, but the July-September averages remained the weakest since early 2022. Domestic demand improved while export-order and hiring momentum were softer.
- Compliance watch: RBI policy is due 7 October; covered AY 2026-27 tax-audit reports are due 21 October and related returns 21 November; the FADS 2026 declaration window runs to 31 December; the UPI merchant-MDR framework is due to start 15 October.
Market Dashboard
| Indicator | Level | Move | Timestamp / status |
|---|---|---|---|
| Nifty 50 | 22,776.10 | +0.98% | 6 Oct India close |
| Sensex | 73,067.81 | +0.95% | 6 Oct India close |
| FII/FPI cash | -Rs 2,961.30 cr | Net seller | 6 Oct provisional cash |
| DII cash | +Rs 5,088.92 cr | Net buyer | 6 Oct provisional cash |
| USD/INR | 96.42 | Rupee -0.1% | 6 Oct close |
| RBI repo rate | 5.25% | Decision due 7 Oct | Current policy rate before MPC decision |
| GIFT Nifty Oct-26 | 22,780.50 | Screen: +6.50 (+0.03%) | 01:09:43 IST; live Session 2 |
| Brent | US$100.58/bbl | +0.3% | 6 Oct settlement |
| WTI | US$89.44/bbl | +US$0.01 | 6 Oct settlement |
| Spot gold | US$4,168.33/oz | +0.7% | 6 Oct 18:12 GMT Reuters |
| Spot silver | US$61.56/oz | +0.8% | 6 Oct Reuters US-close hours |
| US 10Y | 5.26% | -4.4 bp | Reuters afternoon US trade |
| S&P 500 | Late session | +0.66% | Reuters afternoon US trade |
| Nasdaq | Late session | +0.60% | Reuters afternoon US trade |
| Dow | Late session | +0.50% | Reuters afternoon US trade |
| India Services PMI | 55.2 | Aug: 54.1 | September 2026 |
| India Composite PMI | 55.9 | Aug: 54.3 | September 2026 |
India equities: two-day rebound becomes broad-based
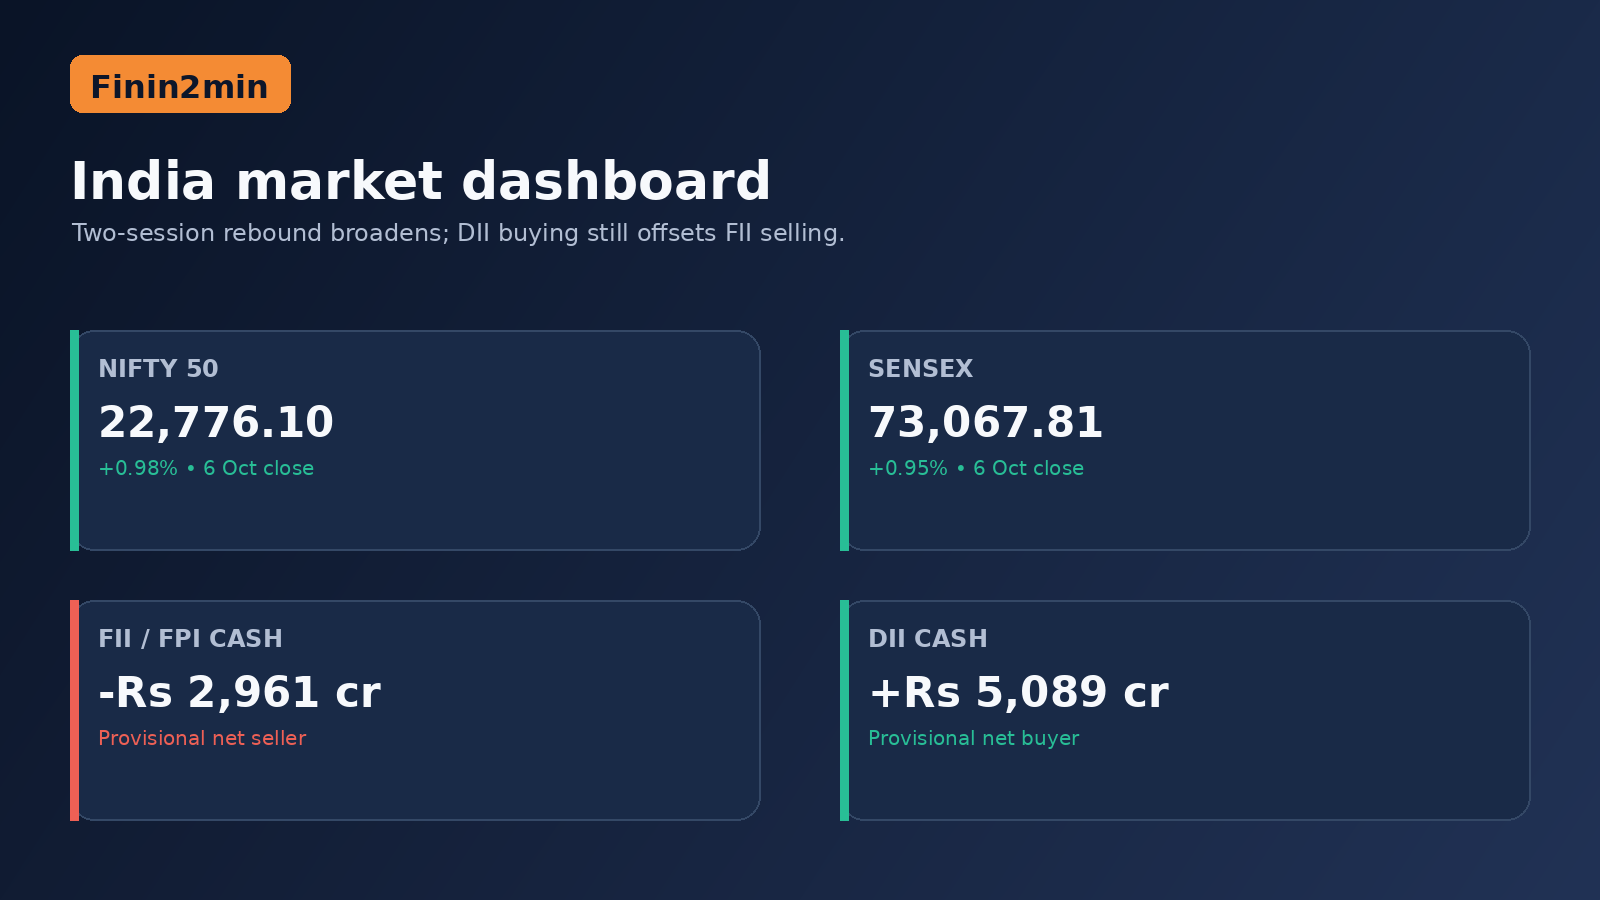
Nifty 50 added 220.35 points to 22,776.10 and Sensex gained 685.34 points to 73,067.81. The breadth was stronger than the headline move: 14 of 16 major sector indices advanced, while small-caps and mid-caps rose 1.6% and 1.1%. Financials, banks and private banks gained roughly 0.75%-1.5%.
Stock-specific business updates amplified the move. Kotak Mahindra Bank rose 3.8% and Axis Bank 2.1% after advances/deposit updates; Reliance Industries gained 2.7%; Trent jumped 12.6% after projecting about 23% year-on-year standalone revenue growth for the September quarter. Dabur and Godrej Consumer also rose on business updates.
The quality of the rebound is better than a narrow index squeeze, but the market still carries the scar tissue of eight consecutive losing weeks. A durable shift would be easier to validate if foreign cash selling turns neutral/positive, the rupee stabilises and long global yields stop testing multi-decade highs.
Institutional flows: DII absorption still doing the heavy lifting
Provisional 6 October cash-market data showed FIIs/FPIs buying Rs 11,258.72 crore and selling Rs 14,220.02 crore, for a net outflow of Rs 2,961.30 crore. DIIs bought Rs 20,146.40 crore and sold Rs 15,057.48 crore, for a net inflow of Rs 5,088.92 crore.
That leaves a positive combined institutional balance of roughly Rs 2,127.62 crore for the session. FII selling has moderated from the very heavy outflows seen around month-end, but it has not reversed. The cleaner signal for risk appetite would be simultaneous DII support and sustained FII net buying rather than domestic institutions repeatedly absorbing foreign supply.
Rupee, rates and the RBI decision: policy transmission matters more than the headline
USD/INR closed at 96.42, down about 0.1% for the rupee and the weakest level in more than two months. State-run bank dollar sales, likely on behalf of the RBI, helped contain the move. Reuters also reported market expectations that the RBI has used sell/buy FX swaps, open-market bond sales and reverse repos to absorb excess rupee liquidity.
The policy repo rate remained 5.25% going into the 7 October MPC decision. A Reuters poll showed about 60% of 61 economists expect a 25-basis-point increase; swap markets attach a modest chance to a larger move. This remains an expectation, not the policy decision.
For finance teams, the decision matrix is broader than repo alone: watch the vote split, stance, inflation/growth assumptions, liquidity-drain tools, bond-market operations and FX language. Banks and NBFCs should assess deposit repricing and ALM; borrowers should check floating-rate reset clauses; treasuries should model oil-plus-rupee stress rather than treat the two risks separately.

GIFT Nifty: latest live cue, with session labels intact
At 01:09:43 IST on 7 October, the Oct-26 GIFT Nifty screen showed 22,780.50, with the provider displaying +6.50 (+0.03%) for the live quote. The live Session 2 screen range at that moment was 22,780-22,802; the full 6 October historical range on the same provider was 22,618-22,870.
The Nifty cash close was 22,776.10, leaving a small numerical futures basis of about +4.40 points. That comparison is useful context, but it is not a forecast of the opening gap because cash and GIFT futures trade on different clocks and react to overnight news before the domestic cash market opens.
The practical overnight checklist is therefore: first fresh GIFT quote, Brent/WTI, USD/INR offshore pricing, US Treasury yields, Asian equity breadth and any RBI-policy leaks or geopolitical shock. Avoid treating one futures print as a standalone directional call.

Crude oil: $100 Brent becomes a balance point, not a comfort zone
Brent settled 26 cents higher at US$100.58/bbl and WTI added one cent to US$89.44/bbl. The market is balancing materially better physical flows against still-elevated security risk.
Around 12 million barrels per day of crude and 2 million bpd of refined products left the Middle East in the preceding 7-10 days, according to the Vitol CEO cited by Reuters. G7 economies also agreed to release 100 million barrels of diesel and crude from emergency reserves. These factors reduce immediate scarcity pressure.
The offset is geopolitical and weather risk: attacks around Saudi infrastructure remain a tail risk, and the US Gulf faced a high probability of cyclone formation. EIA projected 2026 global petroleum production at 101.1 million bpd and demand at 102.4 million bpd, underscoring why the physical buffer remains thin. For India, watch the combined effect on the import bill, INR, freight, aviation, chemicals, paints and inflation expectations.

Gold, silver and global rates: yields ease, safe-haven demand stays alive
Spot gold rose 0.7% to US$4,168.33/oz by 18:12 GMT; December US gold futures settled 0.7% higher at US$4,187.10. Silver rose 0.8% to US$61.56/oz. Platinum fell about 1%, while palladium was roughly unchanged in the Reuters update.
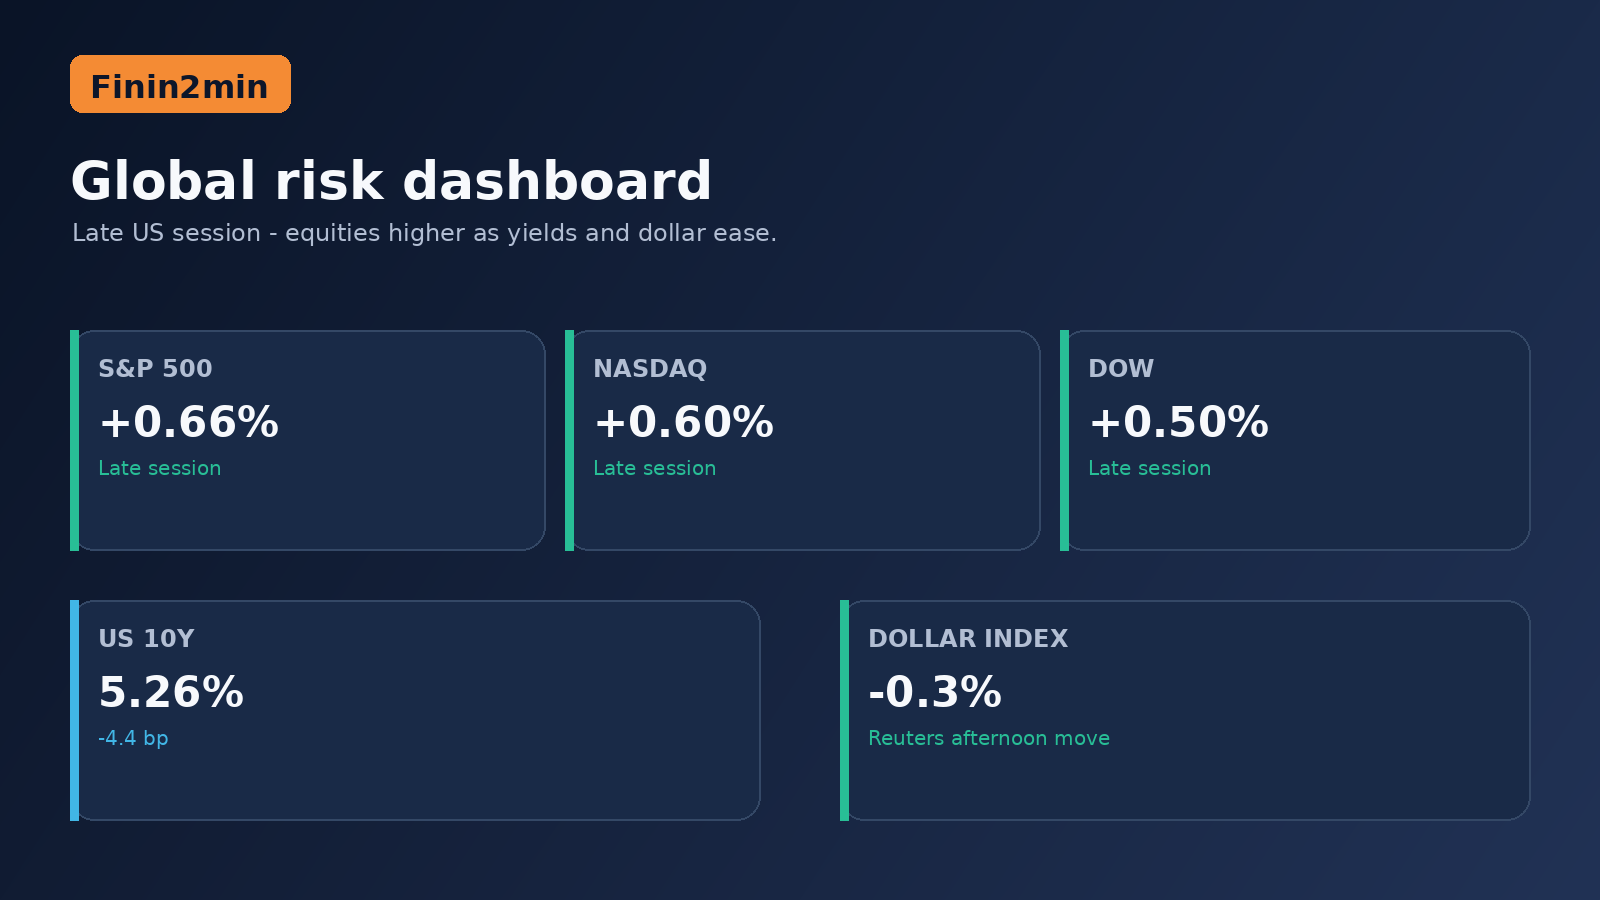
The immediate support came from a weaker dollar and a pullback in long US Treasury yields. The US 10-year yield fell about 4.4 basis points to 5.26% and the 30-year yield about 2.9 basis points to 5.63% in Reuters afternoon trading. Markets had cut the implied probability of an October Fed hike sharply after softer payroll growth.
For Indian investors, bullion is being pulled in opposite directions: geopolitical/fiscal risk and currency weakness support domestic gold, while very high global yields raise the opportunity cost of holding non-yielding assets. Silver adds industrial-demand sensitivity, so it can move more violently than gold even when the macro driver is the same.
Global markets: equities rally even as the discount rate stays historically high
Reuters afternoon US trading had the S&P 500 up about 0.66%, Nasdaq up 0.60% and Dow up 0.50%; the S&P touched a record high and Nasdaq was on track for a third consecutive record. The STOXX 600 was up about 0.5%. These were late-session/intraday readings, not final US closes at the newsletter cut.
The dollar index fell about 0.3%, and the euro recovered to around 1.126. The macro tension is clear: equity earnings expectations and AI-linked capex remain strong, while sovereign yields are still near levels not seen for decades. For India, falling US yields would be supportive for valuation and capital-flow pressure, but the level of yields remains restrictive.
India macro: services recover, but the quarter still signals slower momentum
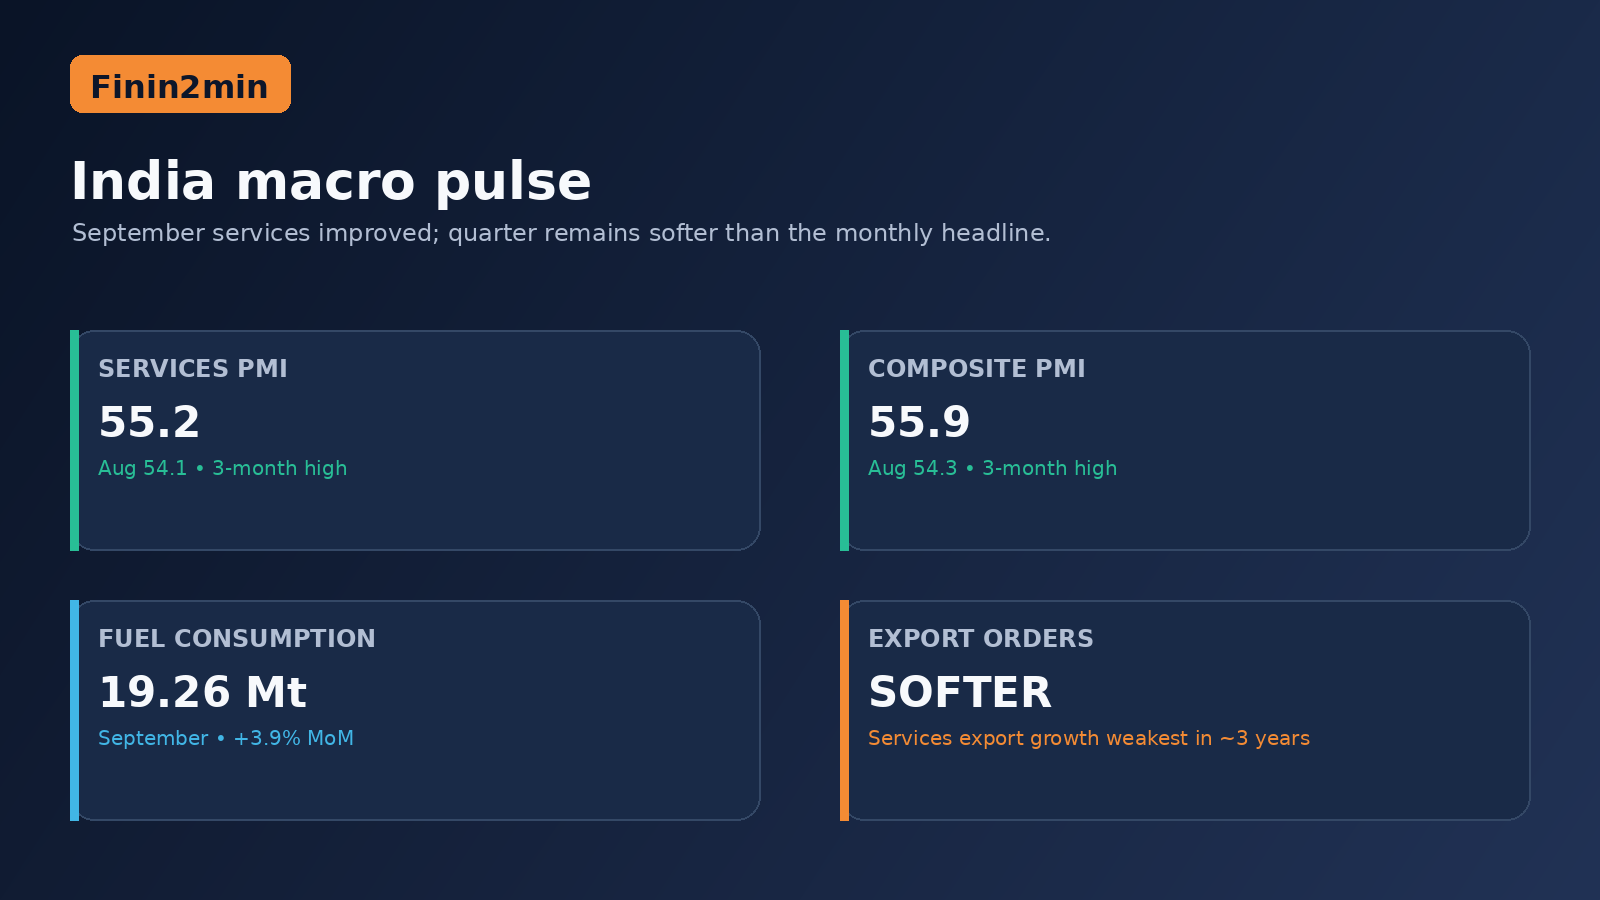
HSBC India Services PMI rose to 55.2 in September from 54.1 in August, a three-month high. New business expanded at the fastest pace since June, helped by financial, consumer and digital services. Composite PMI rose to 55.9 from 54.3.
The caveat is the quarter: the July-September average for services was the weakest since the quarter ended March 2022. Export-order growth slowed to its weakest in nearly three years and employment growth eased. Input-cost inflation was the lowest in 10 months, while selling-price inflation was the slowest since June.
Separately, September fuel consumption rose 3.9% month-on-month to about 19.26 million metric tonnes. Read together, the data point to resilient domestic activity but a less uniform expansion across external demand, hiring and energy use.
Tax and compliance desk: operative dates and active disclosure windows
CBDT Circular 07/2026 remains the operative timeline for the covered AY 2026-27 audit category: the specified date for the audit report is 21 October 2026 and the related income-tax return due date is 21 November 2026. Finance teams should remove superseded 30 September/31 October dates from trackers for the covered cases.
The Foreign Assets of Small Taxpayers Disclosure Scheme, 2026 (FADS) is open from 16 August to 31 December 2026. The Income Tax Department manual says Category 1 covers specified undisclosed foreign assets/income up to an aggregate Rs 1 crore, with 30% tax plus an equal amount (effectively 60% of the relevant amount); Category 2 covers specified previously taxed/non-resident-period foreign assets up to Rs 5 crore with a flat Rs 1 lakh fee, subject to conditions. This is a specialist compliance decision and requires fact-specific review.
CBDT has also highlighted Notification 121/2026 on TDS reporting for non-resident property transactions and Notification 120/2026 extending the registration deadline for Registered Valuers and Authorised Income-tax Practitioners to 31 March 2027. Verify exact applicability before filing.

GST, payments and regulatory radar
For monthly GST filers, the standard GSTR-1 cycle is generally anchored to the 11th of the following month and GSTR-3B to the 20th, subject to taxpayer category, state, filing frequency and any extension. GSTR-1A is available after GSTR-1/the due date and before GSTR-3B for same-period corrections. Portal status should be checked before relying on a generic calendar.
From 15 October, the UPI merchant-pricing framework is scheduled to apply a 0.4% MDR to qualifying person-to-merchant payments above Rs 2,000, with a Rs 300 cap for transactions of Rs 75,000 and above; certain essential sectors have a flat Rs 5 charge and capital-market payments a separate 0.02% capped structure. The government has stated that MDR is within the merchant-payment ecosystem and should not be passed to customers as a UPI fee.
SEBI's latest material press release before the cut remains the 5 October Project Jagrook rollout, including the MUST initiative and investor-awareness presence on WhatsApp. SEBI also revamped its Document Number Verification System on 1 October. The IBBI circular register showed no substantive circular newer than 9 September; IFSCA on 6 October highlighted a consumer-awareness and protection conference during IOSCO World Investor Week.
Corporate / earnings radar: Q2 updates start shaping the tape
Titan reported 25% growth in quarterly consumer-business sales, while Dabur said it expects double-digit growth in consolidated revenue and profit after tax for the September quarter. These updates supported consumer names during the session.
TCS earnings on 8 October are the next major India-IT test. The broader sector enters results season with pressure from cautious client spending and AI-driven pricing disruption, even as rupee weakness can support reported revenue translation. Read guidance, deal wins and pricing commentary alongside headline profit.
What to watch next
- RBI on 7 October: repo decision, vote split, stance, inflation/growth projections, liquidity and FX-management language.
- GIFT Nifty: use the first fresh quote after the policy result rather than the pre-policy overnight print as the next directional cue.
- FII/DII: whether foreign cash selling falls further or reverses while DII buying remains robust.
- Oil: whether Brent can hold near/below US$100 as G7 emergency stocks and stronger Gulf exports meet security and weather risks.
- USD/INR and India G-Secs: policy transmission will show quickly through the rupee, benchmark yield and money-market liquidity.
- Gold/silver: Fed minutes, US yields and dollar direction; silver is likely to remain the higher-beta metal.
- Tax/payments: 7 October monthly TDS deposit for applicable deductors; 11 October GSTR-1 general monthly cycle; 15 October UPI merchant-MDR start; 21 October covered tax-audit report date.
October Compliance Calendar
| Date | Regulator | Obligation / event | Audience | Status / action |
|---|---|---|---|---|
| 07 Oct 2026 | RBI | Monetary Policy Committee decision | Banks, borrowers, treasuries, investors | Decision pending at publication cut; market base case is +25 bp, not a confirmed outcome |
| 07 Oct 2026 | Income-tax | Monthly TDS deposit for September - general rule | Applicable deductors | Verify entity-specific exceptions/holidays on the tax portal |
| 11 Oct 2026 | GST | GSTR-1 for September - monthly filers | Monthly GST filers | Standard cycle; verify category/state/extension |
| 15 Oct 2026 | NPCI / Payments | UPI merchant MDR framework begins | Merchants, acquirers, payment firms | 0.4% on qualifying P2M > Rs 2,000; caps/sector rates apply; not a consumer UPI fee |
| 20 Oct 2026 | GST | GSTR-3B for September - monthly filers | Monthly GST filers | Standard cycle; verify category/state/extension |
| 21 Oct 2026 | CBDT | Audit report - covered AY 2026-27 cases | Covered taxpayers and auditors | Operative extended specified date under Circular 07/2026 |
| 31 Oct 2026 | Income-tax | Q2 TDS statements - form/category dependent | Deductors | Verify form, category and any specific extension |
| 21 Nov 2026 | CBDT | ITR - same covered audit category | Covered taxpayers | Operative extended date under Circular 07/2026 |
| 31 Dec 2026 | CBDT | FADS 2026 declaration window closes | Eligible taxpayers with specified foreign asset/income disclosure issues | Declaration window stated in official user manual; specialist review advised |
Selected primary/global sources
- Reuters - India equities close
https://www.reuters.com/world/india/indian-shares-poised-extend-rebound-ahead-rbi-policy-verdict-2026-10-06/ - NSE - Institutional flows
https://www.nseindia.com/reports/fii-dii - Reuters - Rupee / RBI liquidity
https://www.reuters.com/world/india/rupee-pressured-by-us-yields-euro-led-dollar-strength-rbi-acts-buffer-2026-10-06/ - Investing.com India - GIFT Nifty Oct-26
https://in.investing.com/indices/gift-nifty-50-c1-futures-historical-data - Reuters - Crude settlement
https://www.reuters.com/business/energy/oil-prices-slip-traders-weigh-strong-mideast-exports-against-gulf-tensions-2026-10-06/ - Reuters - Gold & silver
https://www.reuters.com/world/india/gold-inches-lower-firmer-dollar-higher-yields-weigh-2026-10-06/ - Reuters - Global markets & rates
https://www.reuters.com/world/china/global-markets-global-markets-2026-10-06/ - Reuters / S&P Global-HSBC survey - India services PMI
https://www.reuters.com/world/india/india-services-growth-3-month-high-quarter-weakest-since-2022-pmi-shows-2026-10-06/ - Reuters / PPAC - India fuel consumption
https://www.reuters.com/business/energy/indias-september-fuel-consumption-rises-39-previous-month-2026-10-06/ - Income Tax Department - Tax audit / ITR extension
https://www.incometax.gov.in/iec/foportal/ - Income Tax Department - FADS 2026
https://www.incometax.gov.in/iec/foportal/newdownloads/form%201%20of%20fads-um - SEBI - SEBI investor awareness
https://www.sebi.gov.in/sebiweb/home/HomeAction.do?doListing=yes&sid=6&ssid=23 - SEBI - SEBI document verification
https://www.sebi.gov.in/sebiweb/home/HomeAction.do?doListing=yes&sid=6&ssid=23 - PIB / NPCI - UPI MDR
https://www.pib.gov.in/PressReleseDetailm.aspx?PRID=2310586&lang=1®=3 - GST Portal - GST return mechanics
https://tutorial.gst.gov.in/userguide/returns/GSTR_1.htm - IBBI - IBBI circular register
https://ibbi.gov.in/legal-framework/circulars
Methodology & disclaimer
Primary regulators/exchanges and official releases are preferred for tax, regulatory and compliance items. Reuters is used for time-sensitive market/global reporting. Market series are instrument-, contract-, status- and timestamp-labelled.
Educational and informational content only. Not investment, tax or legal advice. Market prices and regulatory positions can change; readers should verify current applicability for their circumstances.