Relief rally, unresolved macro: India rebounds as oil eases - but ₹96 rupee, FII selling and RBI risk keep the bar high
Daily Finance Intelligence | Markets • Crude • Bullion • FX • Rates • Macro • Tax • SEBI • Compliance
2-Minute Summary
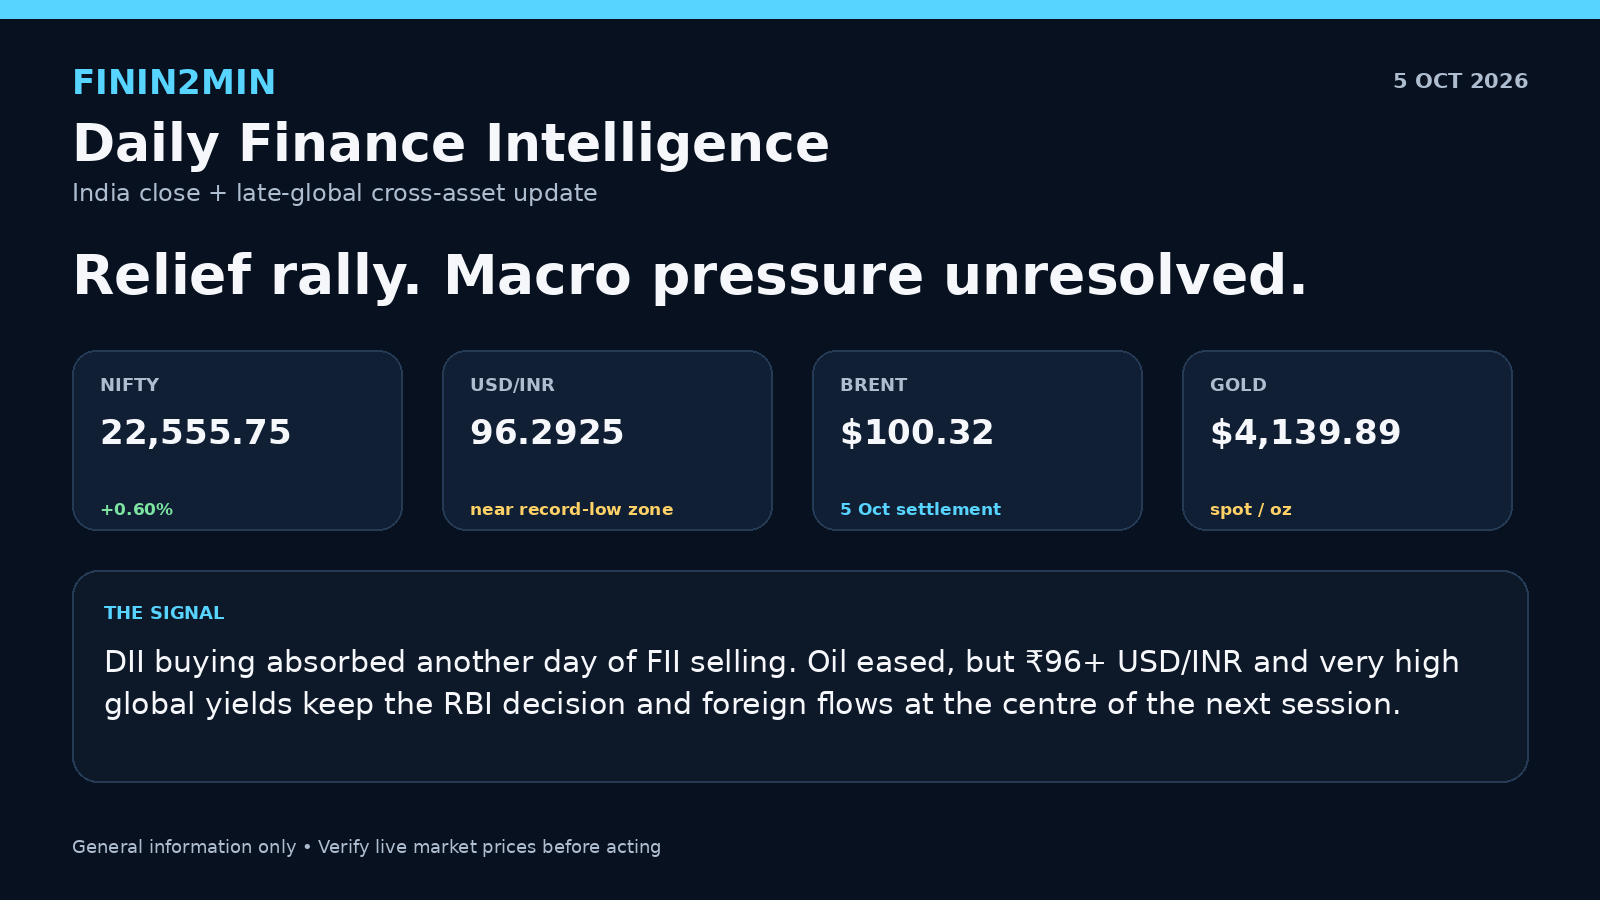
- Indian equities finally produced a relief session after eight consecutive weekly declines: Nifty 50 closed at 22,555.75 (+0.60%) and Sensex at 72,382.47 (+0.66%). Thirteen of 16 major sectors rose, with ITC and financial names supporting the rebound.
- The rebound did not remove the flow problem. Provisional cash-market data showed FII/FPI net selling of ₹4,699.14 crore against DII net buying of ₹5,181.62 crore. Domestic liquidity again absorbed foreign supply.
- The rupee ended almost flat at ₹96.2925/$, with suspected RBI intervention offsetting a stronger dollar, high oil and importer hedging demand. Importers booked US$576.6 billion of forwards during January-September versus US$305.6 billion by exporters.
- GIFT Nifty stood at 22,667.00 at 01:08 AM, up 91.00 points (+0.40%) on the 1D display. The screen showed a day low of 22,501.00 and high of 22,723.00, giving a positive overnight futures cue while still not guaranteeing the cash-market opening level.
- Crude settled lower: Brent closed at US$100.32/bbl and WTI at US$89.43 as recovering Middle East exports and a planned G7 release of 100 million barrels of emergency stocks offset continuing Gulf infrastructure and tanker risks.
- Gold was nearly flat at US$4,139.89/oz while silver rose 1.2% to US$61.09/oz. Weak US payrolls reduced the probability of an October Fed hike, but a strong dollar and very high Treasury yields capped gold.
- RBI is the next domestic macro catalyst. A Reuters poll showed nearly 60% of economists expecting a 25-bp repo increase to 5.50% on 7 October. This is a market expectation, not a decision.
- Compliance remains active: SEBI launched its nationwide Project Jagrook campaign/MUST initiative on 5 October; covered AY 2026-27 tax-audit reports are due 21 October and the related returns 21 November.
| Indicator | Level | Move | Timestamp/status |
|---|---|---|---|
| Nifty 50 | 22,555.75 | +0.60% | 5 Oct India close |
| Sensex | 72,382.47 | +0.66% | 5 Oct India close |
| USD/INR | 96.2925 | rupee +0.02% vs prior | 5 Oct close |
| FII/FPI cash | -₹4,699.14 cr | net seller | 5 Oct provisional |
| DII cash | +₹5,181.62 cr | net buyer | 5 Oct provisional |
| GIFT Nifty | 22,667.00 | +91.00 (+0.40%) | 6 Oct, 01:08 AM screen snapshot |
| Brent | $100.32/bbl | -1.89% | 5 Oct settlement |
| WTI | $89.43/bbl | -1.84% | 5 Oct settlement |
| Spot gold | $4,139.89/oz | -0.1% | 5 Oct 18:04 GMT Reuters update |
| Spot silver | $61.09/oz | +1.2% | 5 Oct Reuters US-close update |
| US gold Dec futures | $4,156.80/oz | -0.1% | 5 Oct settlement |
| S&P 500 | 7,775.33 | +0.68% | 5 Oct Reuters afternoon snapshot |
| Nasdaq | 27,458.40 | +0.98% | 5 Oct Reuters afternoon snapshot |
| Dow | 51,306.65 | +0.25% | 5 Oct Reuters afternoon snapshot |
India equities: relief rally, not yet a regime change
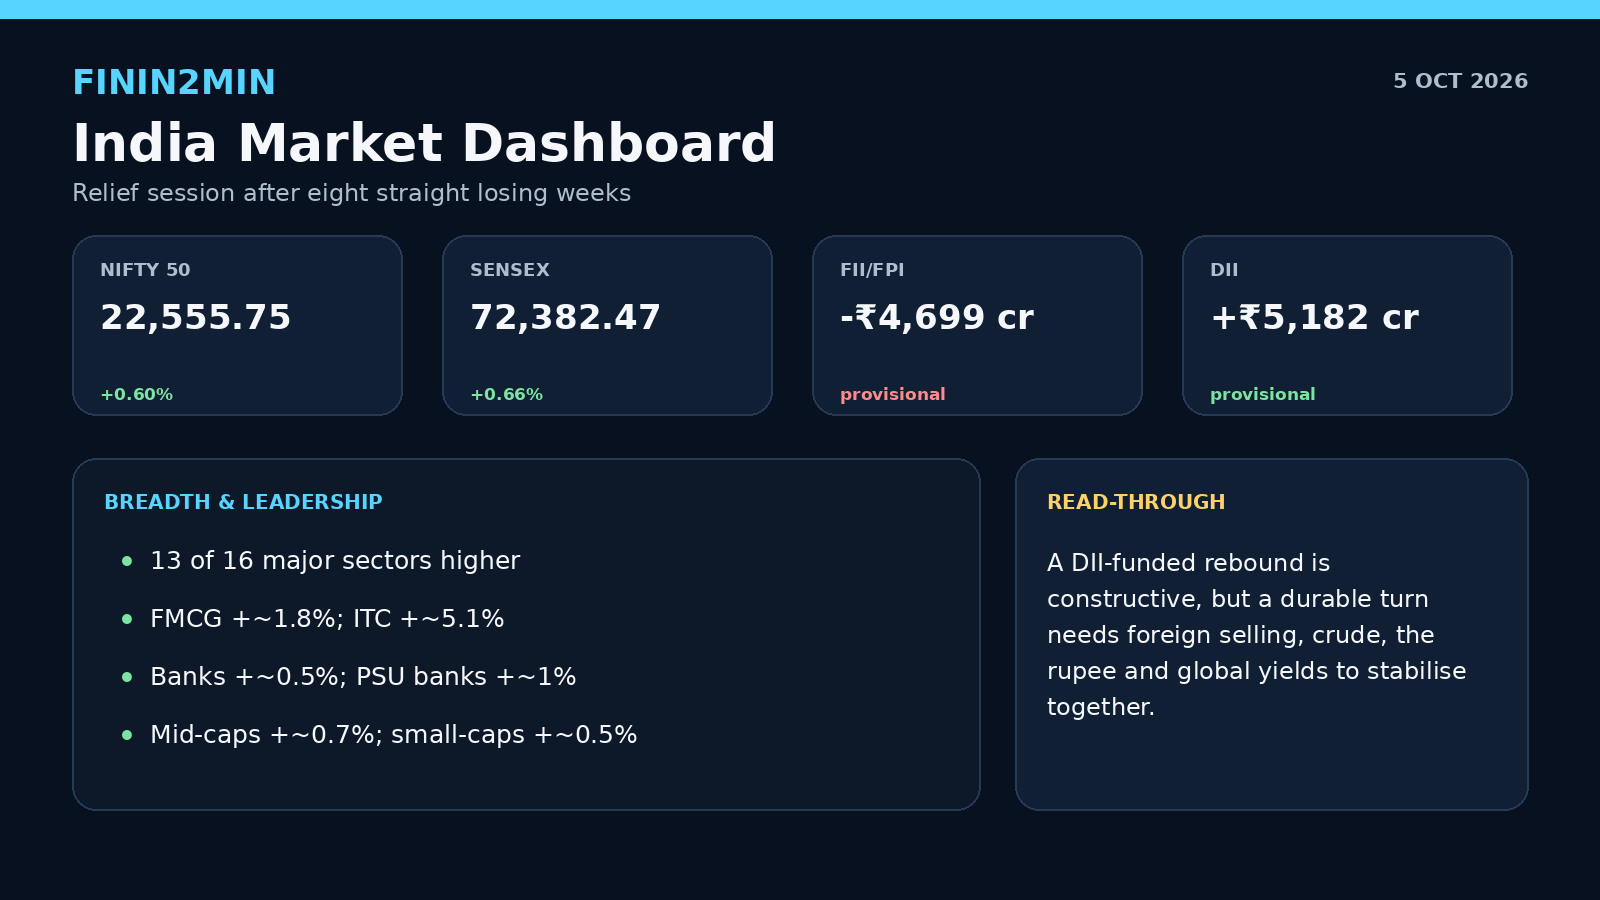
Nifty 50 gained 133.80 points to 22,555.75 and Sensex rose 472.77 points to 72,382.47. The session followed the market’s longest weekly losing sequence in roughly 25 years, so the rebound should be read against a deeply risk-off starting point.
Breadth improved: 13 of 16 major sectors advanced. Banks rose about 0.5%, broader financials about 0.4% and PSU banks around 1%. ITC jumped roughly 5.1%, helping the FMCG index rise about 1.8%. Mid-caps and small-caps also recovered around 0.7% and 0.5%.
The structural test is flows. FIIs remained net sellers while DIIs were larger net buyers. A sustainable re-rating would be stronger if foreign selling slows at the same time as oil, the rupee and global yields stabilise. A single DII-funded up-day is helpful, but not sufficient evidence that the eight-week risk-off regime has reversed.
Rupee and India rates: policy credibility is the next test
The rupee closed at ₹96.2925/$ versus 96.3150 previously, a small improvement despite a strong global dollar and oil above US$100. Reuters reported suspected RBI intervention as one factor keeping the currency in a narrow range.
The corporate hedge book shows why spot stability does not mean pressure has disappeared. Importers booked US$576.6 billion of forwards during January-September, versus US$305.6 billion for exporters. September alone saw exceptionally heavy importer hedging.
For CFOs, the useful framework is three-way: operating exposure (import/export cash flows), balance-sheet exposure (foreign-currency assets/liabilities) and funding exposure (interest-rate and refinancing risk). With oil and USD/INR both elevated, hedging policy should be treated as a treasury-control issue rather than a directional currency bet.

RBI MPC: 7 October decision is the key domestic event
The RBI policy decision is due on Wednesday, 7 October. A Reuters poll found nearly 60% of economists expect a 25-basis-point increase, which would take the repo rate from 5.25% to 5.50%. The expectation follows August CPI inflation of 4.82%, a weak rupee and elevated global yields.
This is not a confirmed hike. Markets should separate the probability of a move from the eventual decision, vote split, stance, inflation forecast and liquidity commentary. A hike accompanied by cautious guidance can produce a different bond/rupee response from the same 25-bp move paired with a more aggressive tightening signal.
Borrowers should watch floating-rate reset mechanics, banks should watch deposit/ALM repricing, and fixed-income investors should focus on the whole curve rather than the policy rate alone.
GIFT Nifty: positive overnight cue, not a guaranteed gap
The GIFT Nifty screen at 01:08 AM showed 22,667.00, up 91.00 points (+0.40%) on the 1D display. The day range shown on the screen was 22,501.00 to 22,723.00.
Against the 5 October Nifty cash close of 22,555.75, the numerical difference is about +111 points. That difference is a cross-session futures basis, not a guaranteed opening gap: cash and futures have different trading hours and mechanics, and overnight oil, FX, yields, Asia and geopolitical headlines can change the setup before the cash open.
For the next session, read the 01:08 AM GIFT Nifty signal together with Brent, USD/INR, US Treasury yields, Asian equities and overnight headlines. It is a useful directional cue, not a promise of the cash-market opening level.

Crude oil: supply relief meets unresolved logistics risk
At the 5 October settlement, Brent closed at US$100.32/bbl (-1.89%) and WTI at US$89.43 (-1.84%). Middle East crude exports had recovered above pre-war levels on several recent days, and G7 countries agreed to release 100 million barrels of diesel and crude from emergency reserves over four months.
At the same time, the market remains exposed to infrastructure attacks, tanker-security risk, elevated insurance/freight costs and constrained refined-product availability. OPEC+ kept November production targets unchanged, while Saudi Aramco cut November Asian official selling prices sharply, another sign that physical flows and regional pricing are normalising unevenly.
For India, the macro transmission runs through the trade deficit, rupee, fuel/freight costs, airlines, chemicals, paints, logistics and inflation expectations. The most important signal is not simply whether Brent is above US$100; it is whether physical product tightness and shipping costs normalise alongside the headline crude price.

Gold, silver and the rates trade
Spot gold was US$4,139.89/oz (-0.1%) in Reuters’ US-close-hours update; December US gold futures settled at US$4,156.80. Silver outperformed, rising 1.2% to US$61.09/oz.
The US September jobs report weakened the near-term Fed-hike case: payrolls increased by only 29,000 and unemployment was 4.2%. October hike probability fell sharply from the prior week. Even so, the dollar strengthened and long Treasury yields stayed near multi-decade highs, limiting the benefit to non-yielding gold.
Portfolio interpretation: gold remains a hedge against geopolitical/inflation uncertainty but faces real/nominal yield pressure. Silver has the same monetary sensitivity plus industrial-demand beta, which explains its larger daily swings. Spot, futures, ETF/NAV and Indian retail prices should never be mixed without labels.
Global markets: equities resilient despite the bond shock
Reuters’ afternoon US snapshot showed S&P 500 +0.68% at 7,775.33, Nasdaq +0.98% at 27,458.40 and Dow +0.25% at 51,306.65. The Nasdaq reached record territory, led by megacap technology.
The resilience is notable because the dollar index was near a 17-month high and US 10-year yields were around the 5.3% area. That combination normally raises the discount rate for equities and competes with emerging-market assets for global capital.
Weak payroll growth lowered near-term Fed-hike pricing, but the global message is still two-sided: easier expected short-rate policy is supportive, while very high long yields and a strong dollar remain restrictive. India therefore needs both oil relief and global yield stabilisation for a cleaner risk-on transmission.

India-US trade: negotiations reach a plateau
Finance Minister Nirmala Sitharaman said India-US trade talks had reached a “plateau”, with limited room for further concessions. The US remains a critical export destination for India, so a prolonged negotiating impasse matters for exporters, sector margins and investment decisions.
For companies, the appropriate response is scenario planning rather than a single tariff assumption: map US revenue/import dependencies, rules-of-origin exposure, alternative suppliers/markets, contract pass-through clauses and working-capital consequences under multiple tariff outcomes.
SEBI and investor-protection desk
On 5 October, SEBI announced the nationwide “Samajh Se Investing Simple” campaign under Project Jagrook, rolled out the MUST initiative, and announced its presence on WhatsApp and other investor-awareness initiatives. The same day, SEBI also announced a local office in Chandigarh.
The operational point for intermediaries is broader than communications: Project Jagrook already has a 1 October circular governing display of investor-awareness messages by stock brokers on websites and trading apps. Compliance teams should preserve exact approved wording, placement evidence, effective-date controls and change logs.
Direct tax, GST and compliance desk
For the covered AY 2026-27 audit category, CBDT extended the specified date for furnishing the audit report to 21 October 2026 and the related income-tax return due date to 21 November 2026. Those dates should replace superseded 30 September/31 October reminders in internal calendars.
Standard October GST/TDS dates remain important but applicability can differ by filing frequency, state, registration profile and specific extension. Finance teams should reconcile portal status, challans, books and return data before the due date rather than rely only on a generic compliance list.

What to watch next
- RBI on 7 October: repo decision, vote split, stance, inflation/growth forecasts and liquidity guidance.
- FII/DII flows: whether domestic buying continues to absorb foreign selling, and whether foreign selling moderates after eight weak weeks.
- Oil: whether Brent can sustain a move closer to/below US$100 as G7 stocks enter the market and Gulf exports normalise.
- USD/INR: whether RBI support and any rate action stabilise the rupee below 96.50 despite heavy importer hedging.
- Gold/silver: watch the dollar and US 10-year yield alongside Fed repricing; silver may remain more volatile.
- India-US trade: any movement beyond the reported negotiation plateau.
- Compliance: Project Jagrook implementation evidence, 7 October TDS deposit, 11 October GSTR-1, 20 October GSTR-3B and 21 October covered audit-report deadline.
October Compliance Calendar
| Date | Obligation/event | Who should care | Status/action |
|---|---|---|---|
| 05 Oct 2026 | SEBI Project Jagrook website display phase | Stock brokers | Website awareness messages + risk disclosures; follow exact SEBI circular/message set |
| 07 Oct 2026 | RBI monetary policy decision | Borrowers, banks, treasuries, investors | Decision pending; Reuters poll majority expects +25 bp, not a confirmed outcome |
| 07 Oct 2026 | TDS deposit for September - general monthly rule | Deductors / finance | Verify entity-specific exceptions and challan requirements |
| 11 Oct 2026 | GSTR-1 for September - monthly filers | GST teams | Standard due date unless applicable extension/category differs |
| 20 Oct 2026 | GSTR-3B for September - monthly filers | GST teams | Standard due date unless applicable extension/category differs |
| 21 Oct 2026 | Tax audit report - covered AY 2026-27 cases | Taxpayers / auditors | CBDT-extended specified date |
| 31 Oct 2026 | Q2 TDS statements - form/category dependent | Deductors / tax teams | Verify applicable statement/form and deductor category |
| 01 Nov 2026 | Project Jagrook app/landing-page phase | Stock brokers | Implement website/app placement requirements per SEBI circular |
| 21 Nov 2026 | ITR for same covered audit category | Taxpayers / finance | CBDT-extended due date |
Methodology & disclaimer
Primary regulators/exchanges and official releases are preferred for tax, regulatory and calendar items. Reuters is used for time-sensitive market/global reporting. GIFT Nifty is shown from the timestamped market screen used for this edition, with the level, 1D move and day range transcribed as displayed.
General information and education only. Not investment, trading, tax, legal or accounting advice. Verify current prices and the exact primary-source law/rule/circular applicable to your facts before acting.
Selected primary/global sources
- Reuters - India equities close
https://www.reuters.com/world/india/indian-shares-poised-rebound-fed-hike-fears-oil-prices-ease-2026-10-05/ - NSE - FII/FPI & DII trading activity
https://www.nseindia.com/reports/fii-dii - Reuters - Rupee close / RBI intervention
https://www.reuters.com/world/india/indian-rupee-set-mild-relief-dip-oil-fading-fed-october-hike-bets-2026-10-05/ - Reuters - RBI policy expectations
https://www.reuters.com/world/india/markets-bet-rbi-rate-hike-inflation-pressure-builds-2026-10-05/ - Reuters - India-US trade talks
https://www.reuters.com/world/india/india-us-have-reached-plateau-trade-talks-indian-finance-minister-says-2026-10-05/ - Reuters - Oil settlement update
https://www.reuters.com/business/energy/oil-climbs-after-yemeni-houthis-attack-saudi-aramco-sites-2026-10-04/ - Reuters - Gold/silver US-close update
https://www.reuters.com/world/india/gold-gains-october-fed-rate-hike-prospects-fade-2026-10-05/ - Reuters - Global markets
https://www.reuters.com/world/china/global-markets-global-markets-2026-10-05/ - US BLS - Employment Situation - September 2026
https://www.bls.gov/news.release/archives/empsit_10022026.htm - SEBI - Media & Notifications
https://www.sebi.gov.in/sebiweb/home/HomeAction.do?doListing=yes&sid=6 - SEBI - Project Jagrook broker display circular
https://www.sebi.gov.in/sebiweb/home/HomeAction.do?doListingAll=yes&search=To - CBDT / PIB - AY 2026-27 audit/ITR extension
https://www.pib.gov.in/PressReleasePage.aspx?PRID=2316050&lang=1®=48 - GIFT Nifty market screen - 01:08 AM snapshot
22,667.00; +91.00 (+0.40%); day range 22,501.00-22,723.00.