Week Ended 2 October 2026
Eight straight losing weeks for India, Brent above US$100, gold -3.4%, silver about -6%, and a ₹96+ rupee - while PMI, GST and equity fundraising show domestic resilience.
Edition cut: 4 October 2026, 19:12 IST. India cash-market week ended 1 Oct; global markets through 2 Oct; weekend developments through 4 Oct are separated.
2-Minute Weekly Read
India's market tape was distinctly risk-off, but the domestic macro tape was more resilient: September manufacturing PMI rose to 55.1, gross GST reached ₹2,03,521 crore (+14.7% YoY), and H1 FY27 equity fundraising hit a record ₹2.43 trillion.
India Equities: Breadth Confirms the Risk-Off Week
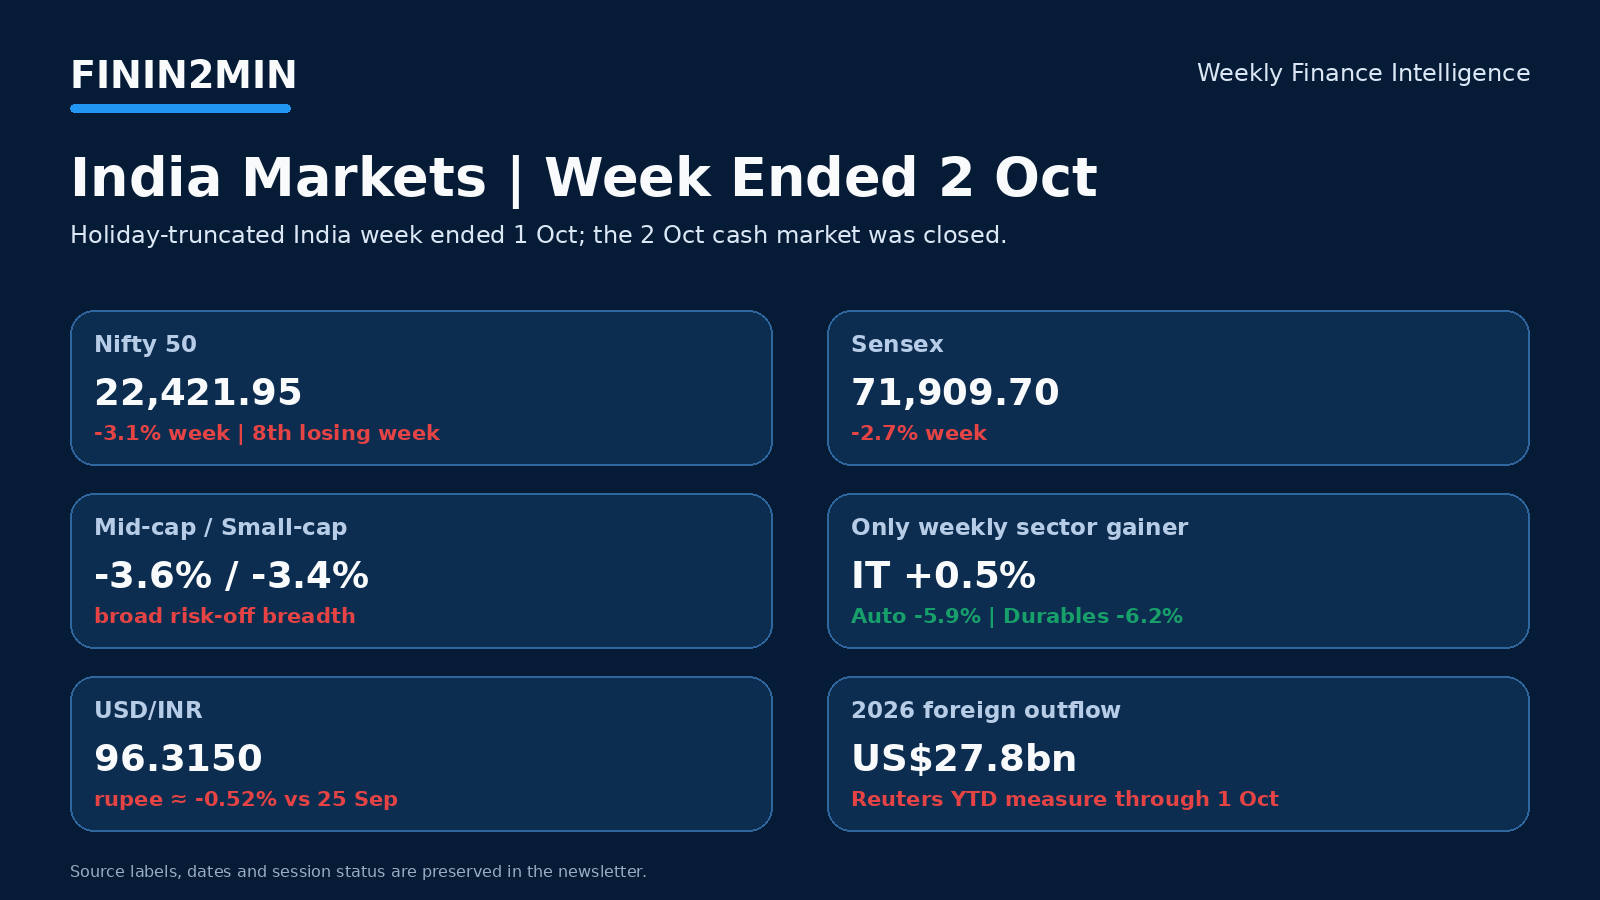
On Monday, Nifty fell 1.56% to 22,780.25 as Brent moved toward US$108. The final India session on Thursday ended with Nifty at 22,421.95 and Sensex at 71,909.70. Reuters put the weekly loss at 3.1% and 2.7%, respectively, extending both benchmarks to an eighth consecutive weekly decline.
Fifteen of 16 major sectors fell. Auto lost 5.9%, consumer durables 6.2%, mid-caps 3.6% and small-caps 3.4%. IT was the only weekly sector gainer at 0.5%. The useful confirmation set for a durable recovery is crude + yields + rupee + foreign flows, not a single green index session.
Flows, Rupee & RBI Liquidity
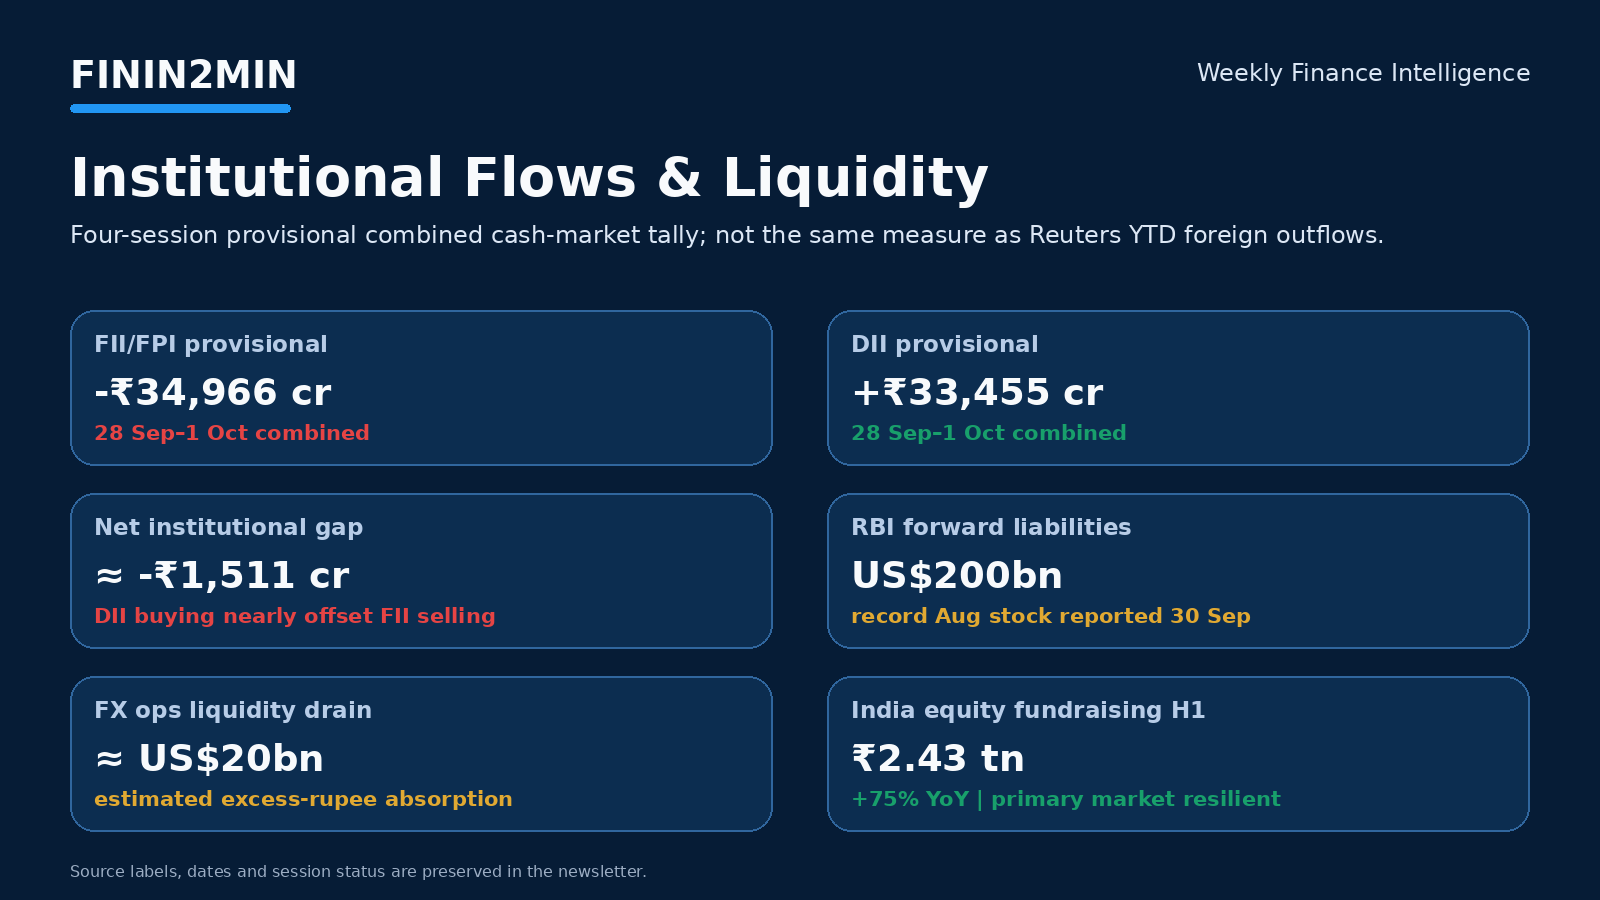
The four-session provisional combined exchange tally is FII/FPI -₹34,966.07 crore versus DII +₹33,455.30 crore. USD/INR ended at 96.3150 on 1 October versus 95.8125 on 25 September, about 0.52% rupee depreciation over the comparable endpoints.
Reuters also reported RBI net forward dollar liabilities at a record US$200 billion for August, while FX operations had absorbed an estimated US$20 billion of excess rupee liquidity. For businesses, this creates a combined FX, funding-cost and liquidity-management problem rather than a currency-only problem.
GIFT Nifty: Cross-Feed Discrepancy Means No Weekend Gap Call

Two independent historical displays for the Oct-26 contract disagree on the 1 October close: 22,624.50 versus 22,491.00, even though both show the same 22,278-22,700 day range. With 2 October an exchange holiday and the weekend following, Finin2min treats the contract as reconciliation-pending and does not manufacture a "latest" gap signal. The next valid reference should be a fresh timestamped live quote after reopening.
Crude: A Volatile US$100+ Week

Brent settled Friday at US$102.25/bbl, up 0.11% for the week, while WTI settled at US$91.11, down 1.6%. The path was much more dramatic than the endpoint: Brent was around US$108 on Monday, then eased as Europe moved toward diesel reserve releases and IEA crude-stock discussions. Refined-product tightness is now as important as crude availability.
Weekend layer: OPEC+ kept November production targets steady on 4 October. That headline belongs to the next trading session's risk map; it is not retroactively included in Friday's weekly return.
Gold, Silver, US Rates & Global Equities

Spot gold ended at US$4,140.06/oz, down about 3.4% for the week. Spot silver was US$60.36/oz, roughly 6.1% below the comparable prior-Friday Reuters snapshot. US payrolls rose only 29,000 in September against a 90,000 Reuters poll, but the US 10-year yield still finished around 5.281%, roughly 10 bps higher on the week.
Wall Street was mixed on a weekly basis: S&P 500 -0.27%, Nasdaq +0.45% and Dow -1.26%. Softer payrolls reduced immediate Fed-hike expectations without ending the long-bond repricing.
India Macro & Capital Formation
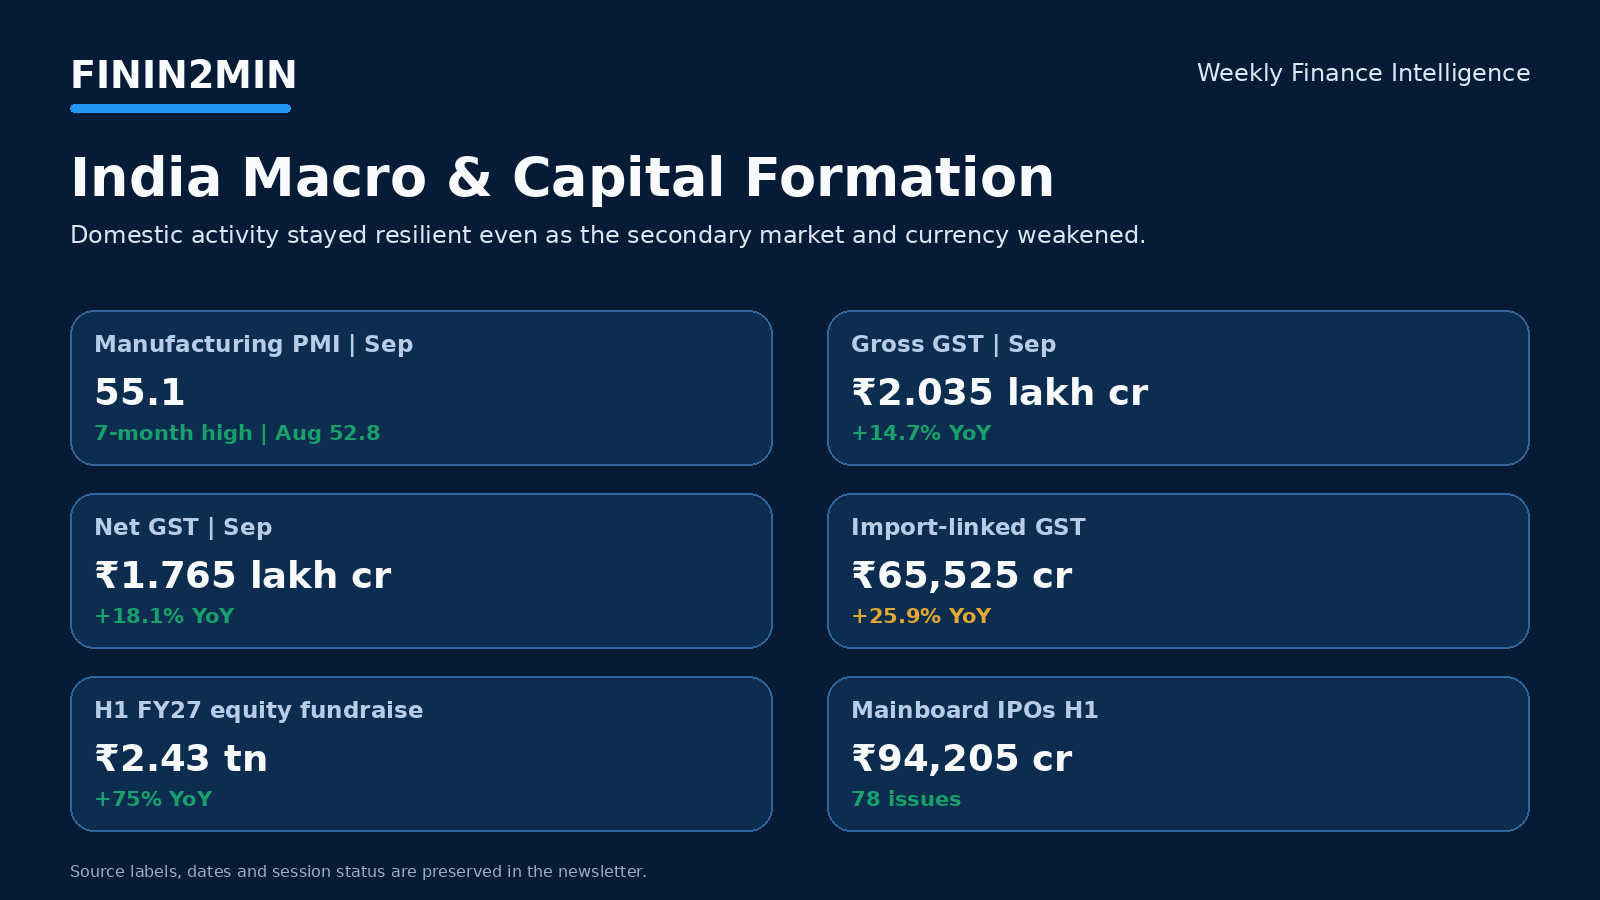
September manufacturing PMI rose to 55.1 from 52.8, the best since February. Gross GST revenue was ₹2,03,521 crore (+14.7% YoY), with gross domestic revenue ₹1,37,996 crore (+10.1%) and import-linked revenue ₹65,525 crore (+25.9%). Refunds were ₹27,001 crore and net GST revenue ₹1,76,520 crore (+18.1%).
Meanwhile, Indian companies raised a record ₹2.43 trillion in H1 FY27, up 75% YoY. Mainboard IPOs raised ₹942.05 billion across 78 issues and QIPs ₹615.53 billion - evidence that primary-market capital formation remained strong despite secondary-market weakness.
RBI: 7 October Is the Central Domestic Catalyst
The repo rate is currently 5.25%. A Reuters poll expects a 25 bp increase to 5.50% at the 7 October decision, but this is a forecast, not an official commitment. Watch the inflation forecast, oil assumptions, liquidity stance, FX language and guidance on whether any move is one-off or part of a sequence.
Tax & Compliance Desk
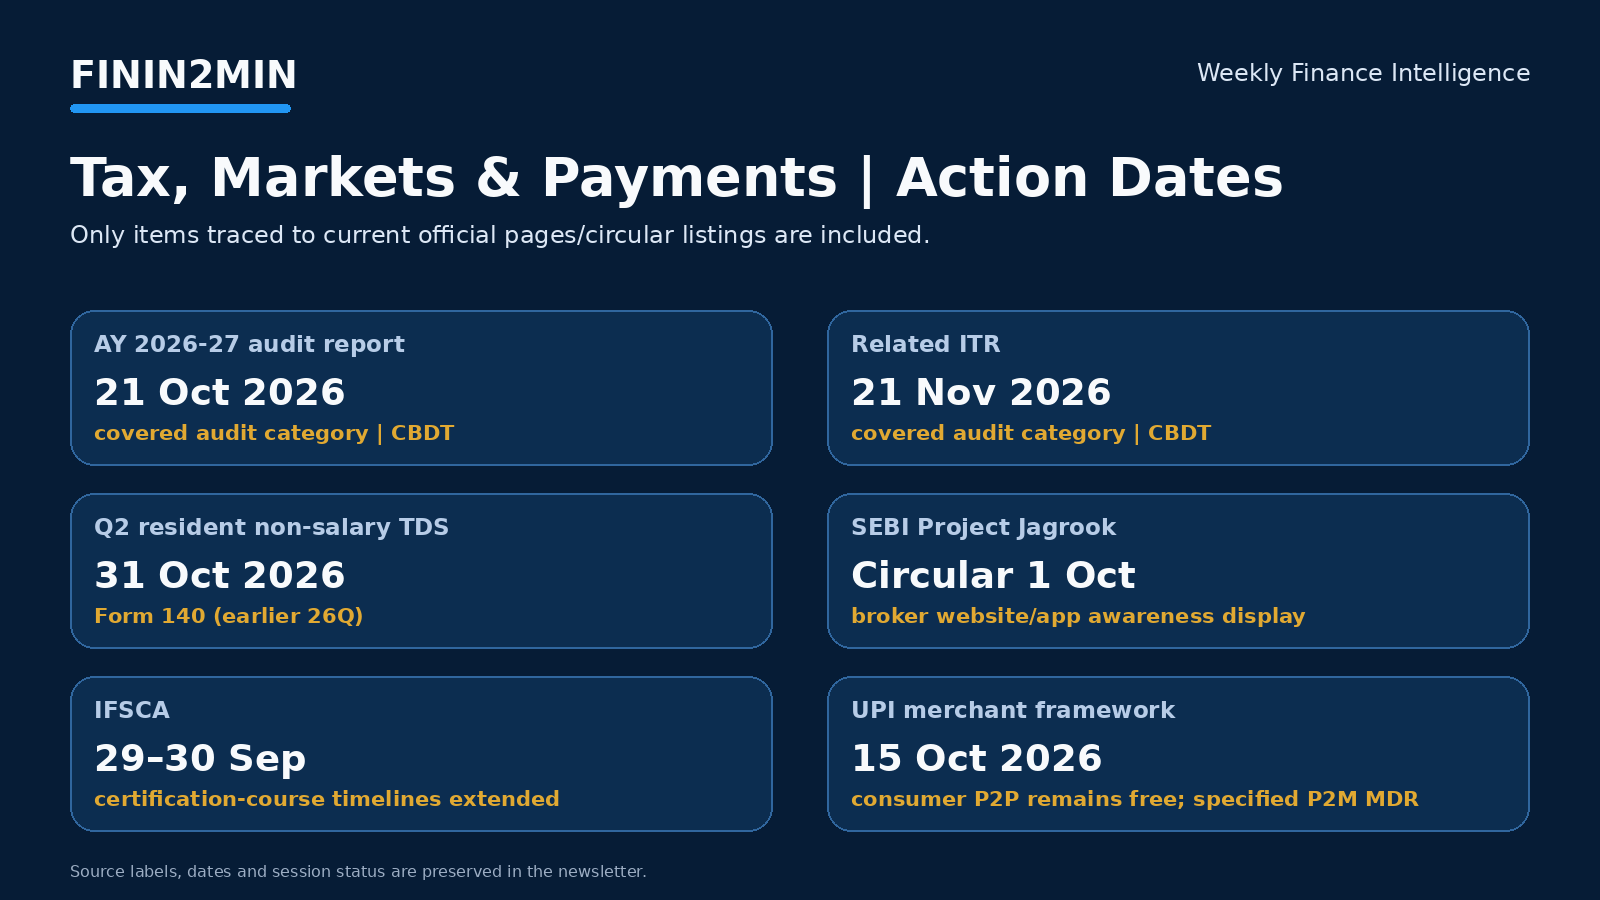
For the specified AY 2026-27 audit category, the Income Tax Department lists 21 October for the audit report and 21 November for the related ITR under Circular 07/2026. The official Form 140 user manual states 31 October for the Q2 resident non-salary TDS statement. These dates should not be generalised beyond their stated category.
SEBI, IFSCA & Payments
SEBI issued the Project Jagrook circular on 1 October for broker investor-awareness messages on trading apps/websites and a fresh Master Circular for Debenture Trustees on 28 September. IFSCA extended certification-course timelines for Fund Management Entity personnel on 29 September and Capital Market Intermediary personnel on 30 September; affected entities should use the circulars for the exact revised dates.
The new UPI merchant framework is due to take effect from 15 October under implementation reporting. The official Finance Ministry clarification says P2P remains free; specified P2M transactions above ₹2,000 attract merchant-side MDR, with special rates/caps for high-value, essential-sector and capital-market transactions. Customers do not pay MDR. Apple Pay also entered India on 30 September through Axis Bank, initially for eligible Visa/Mastercard credit cards.
Next Week: What to Watch
Fresh GIFT quote after reopening; Brent around US$100; USD/INR around 96; US 10Y around 5.3%; FII selling vs DII absorption.
RBI decision on 7 October and its inflation/oil/liquidity guidance.
Tax-audit closure before 21 Oct; Q2 Form 140 workflow before 31 Oct; Project Jagrook implementation; UPI merchant logic before 15 Oct.
Methodology
Weekly returns use completed sessions. India cash ends 1 Oct because 2 Oct was a market holiday. Weekend developments are separated. FII/DII data is provisional. GIFT Nifty cross-feed conflict is disclosed. Silver weekly change is calculated from comparable Reuters Friday spot snapshots. Public regulatory claims are tied to official source pages wherever available.