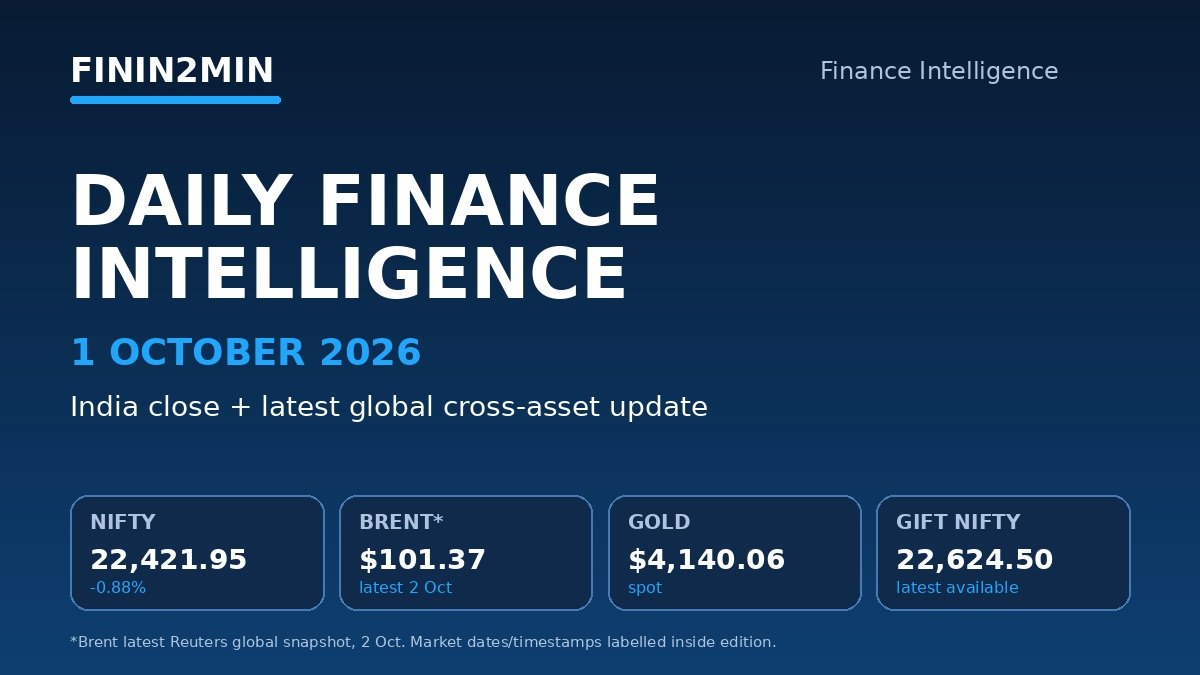
Daily Finance Intelligence - 1 October 2026
India close + latest global cross-asset update
2-Minute Summary
Market Dashboard
| Indicator | Level | Move | Status |
|---|---|---|---|
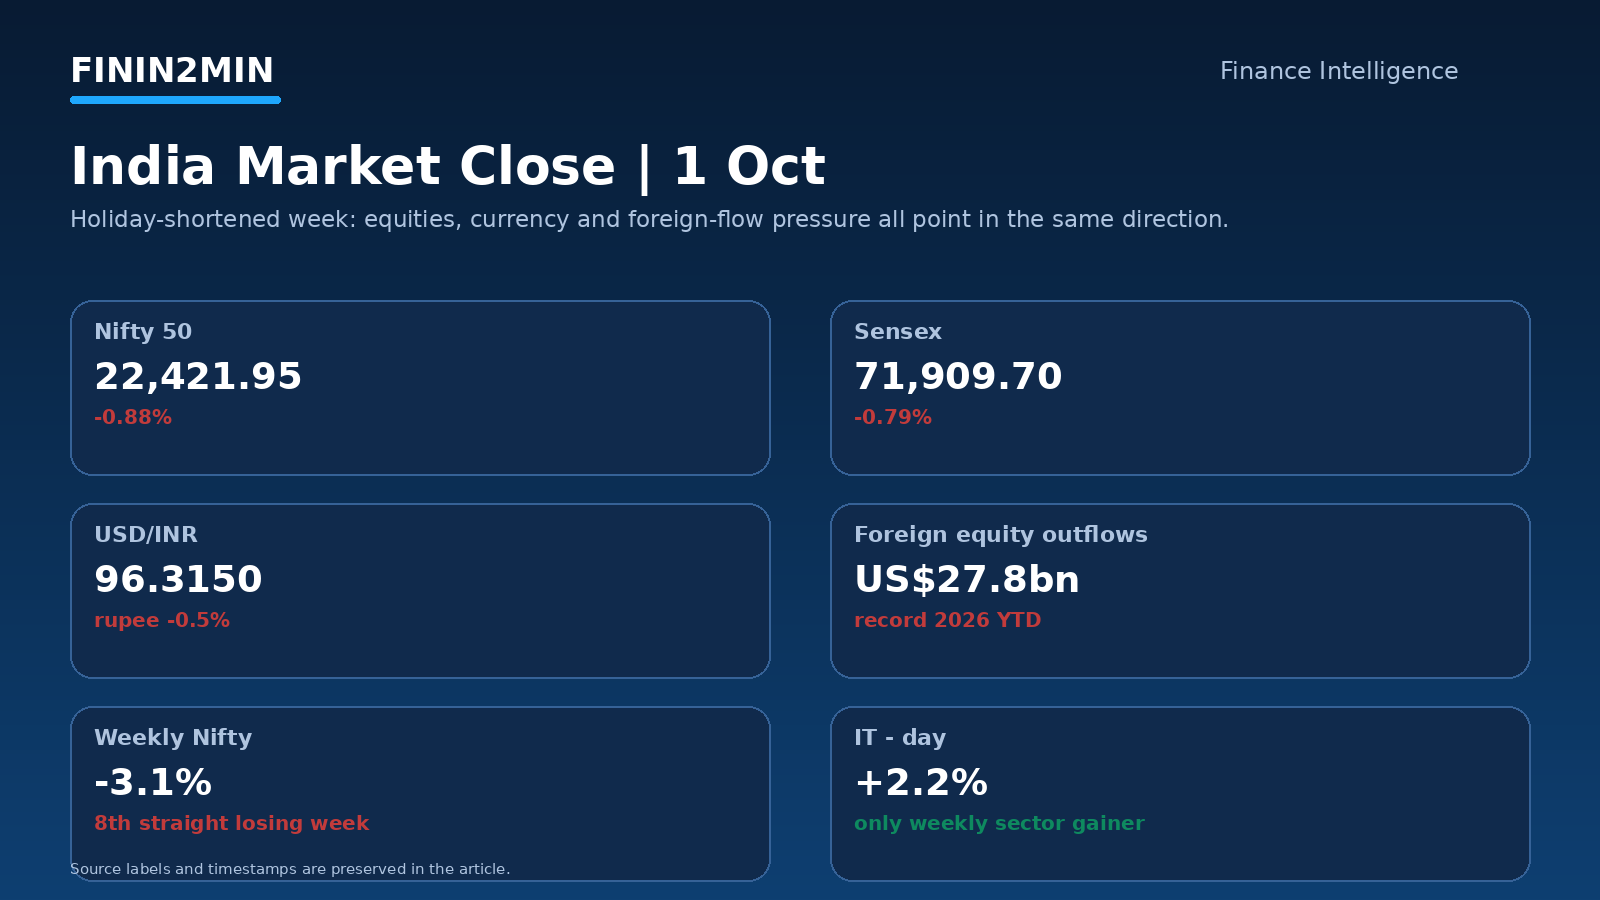
| Nifty 50 | 22,421.95 | -0.88% | 1 Oct India cash close |
| Sensex | 71,909.70 | -0.79% | 1 Oct India cash close |
| USD/INR | 96.3150 | rupee -0.5% | 1 Oct close |
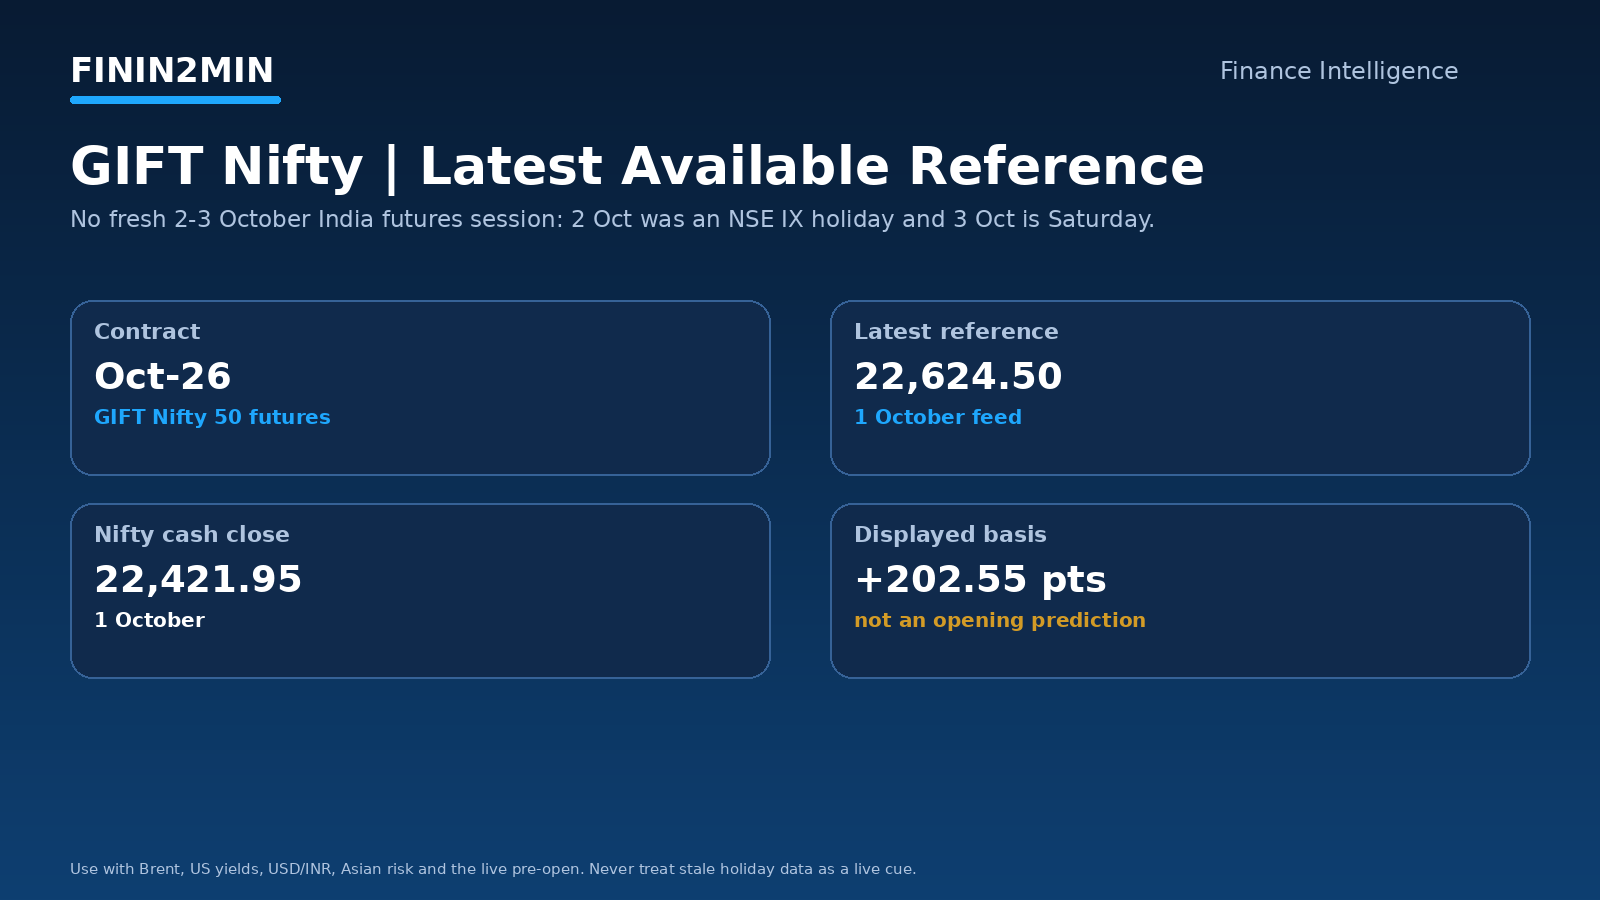
| GIFT Nifty Oct-26 | 22,624.50 | latest available reference | 1 Oct; 2 Oct holiday, 3 Oct weekend |
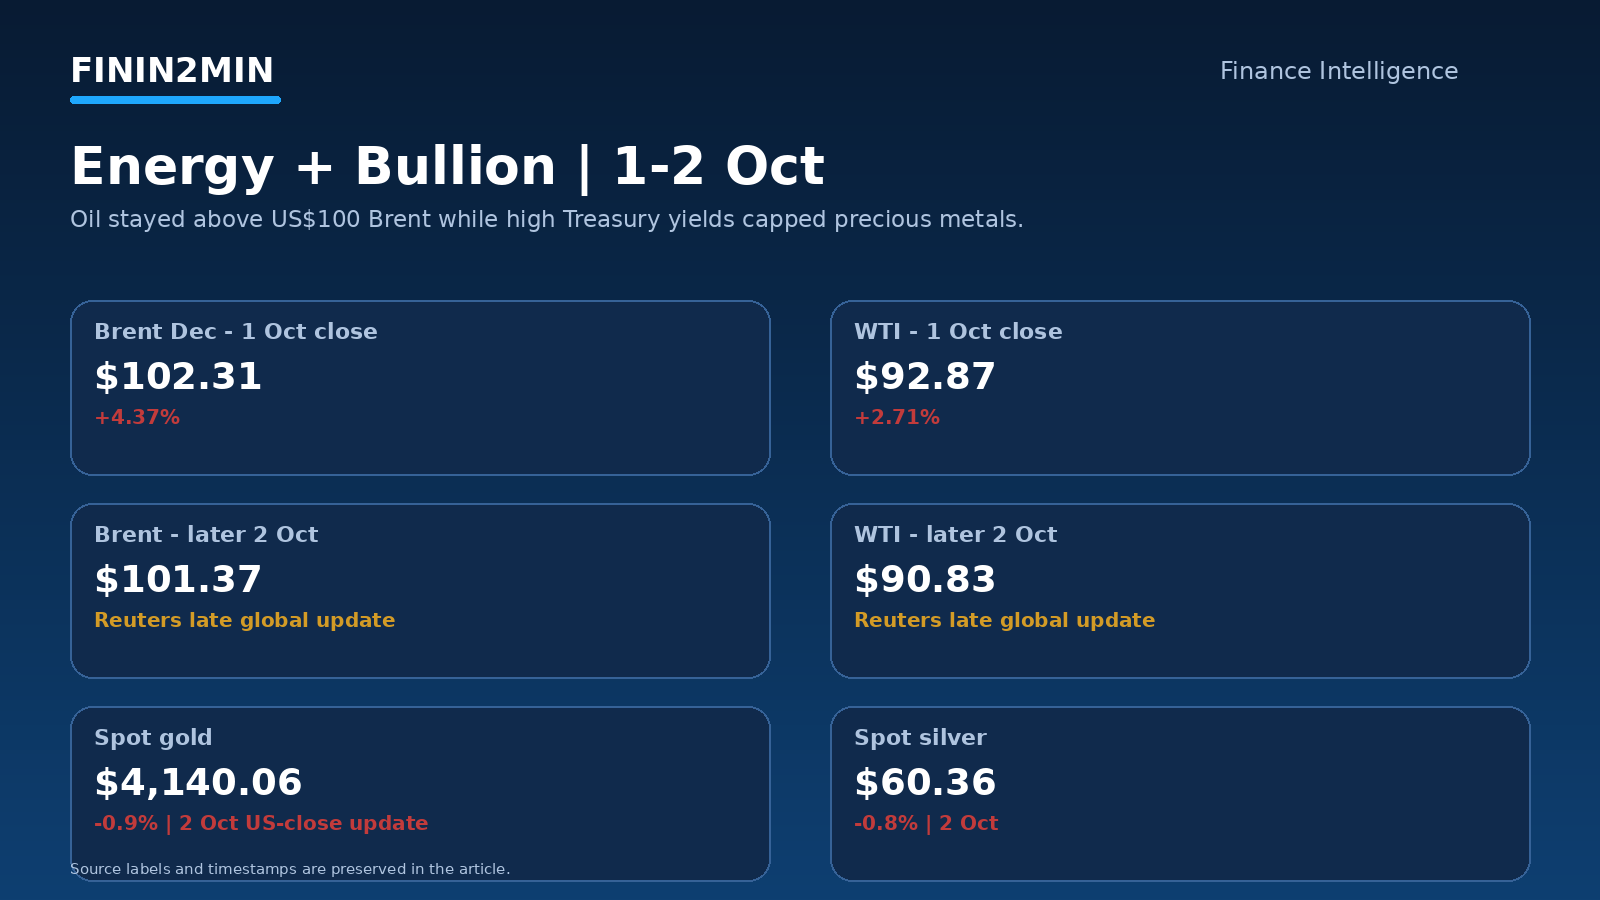
| Brent Dec-26 | $102.31/bbl | +4.37% | 1 Oct settlement |
| WTI | $92.87/bbl | +2.71% | 1 Oct settlement |
| Brent - later snapshot | $101.37/bbl | -0.92% | 2 Oct Reuters late-US update |
| WTI - later snapshot | $90.83/bbl | -2.15% | 2 Oct Reuters late-US update |
| Spot gold | $4,140.06/oz | -0.9% | 2 Oct 18:33 GMT / US close update |
| Spot silver | $60.36/oz | -0.8% | 2 Oct US close update |
| US 10Y Treasury | 5.256% | +2.18 bps | 2 Oct Reuters late-US update |
India equities: eight-week losing streak
What changed
Nifty 50 fell 0.88% to 22,421.95 and Sensex 0.79% to 71,909.70 on 1 October. Reuters reported an eighth consecutive weekly fall - Nifty -3.1% and Sensex -2.7% for the holiday-shortened week - taking the eight-week declines to 8.7% and 8.4%.
Breadth and leadership
Fifteen of 16 major sectors posted weekly losses. Auto fell 5.9% and consumer durables 6.2%; mid-caps fell 3.6% and small-caps 3.4%. IT rose 2.2% on the day and was the only sector with a weekly gain, +0.5%.
Flow signal
Foreign outflows reached a record US$27.8 billion for 2026 by the 1 October close. That remains the biggest market-structure headwind alongside expensive crude and elevated global yields.
Decision lens
For investors and CFOs, the useful question is not whether the index is “cheap” after a fall, but whether oil, yields, foreign flows and the rupee are stabilising together. A durable risk-on turn normally needs more than a single strong session.
Rupee and Indian rates: imported pressure
Rupee close
The rupee ended 0.5% weaker at ₹96.3150/$ on 1 October, its steepest daily fall in more than two months and the weakest level in two months. State-run bank dollar sales limited the decline.
Global rate shock
The US 10-year Treasury yield touched 5.34%, its highest since 2002. India's 10-year benchmark yield also moved to its highest in more than two years. Higher global yields raise the hurdle rate for emerging-market assets and can increase corporate borrowing costs.
Treasury implication
Importers face a double sensitivity when crude and USD/INR rise together. Exporters, importers and borrowers should separate operating exposure, balance-sheet exposure and financing exposure rather than rely on a single currency view.
GIFT Nifty: latest available, not “live”
Reference
The latest available Oct-26 GIFT Nifty reference in the independent global market-data feed is 22,624.50 from 1 October. Against the Nifty cash close of 22,421.95, that is a futures basis of about +202.55 points, but the two instruments do not share identical pricing mechanics or trading hours.
Holiday status
NSE cash and NSE IX were closed on Friday, 2 October for Mahatma Gandhi Jayanti. Saturday, 3 October is also outside the normal trading week. Therefore any screen still showing 22,624.50 should be treated as the last available reference, not a fresh Saturday signal.
How to use it
On the next live session, read GIFT Nifty together with Brent, US yields, USD/INR, Asian equities and overnight headlines. Do not translate futures basis mechanically into a guaranteed cash-market opening gap.
Crude oil: >$100 Brent remains the India macro variable
1 October settlement
New front-month December Brent settled at US$102.31/bbl, up 4.37%, while WTI settled at US$92.87, up 2.71%. The move followed renewed Middle East risk and China suspending oil-product exports beyond Hong Kong and Macau.
Latest global update
By the later 2 October Reuters global-markets snapshot, Brent was US$101.37 and WTI US$90.83 after European discussions around additional diesel and crude stock releases eased some immediate supply anxiety. A separate Reuters energy update said Europe agreed to release diesel supplies, although physical product markets remained tight.
India transmission
Oil near or above US$100 matters through the trade deficit, rupee, fuel and freight costs, aviation, chemicals, paints, logistics, inflation expectations and the RBI policy path. The refined-product shortage is as important as crude availability in the current episode.
Contract discipline
December Brent is now the front-month reference after the November contract expired. Comparing an expiring-contract spike with a new front month without labelling the roll can create a false price signal.
Gold, silver and rates
Latest bullion
Spot gold fell 0.9% to US$4,140.06/oz in Reuters' US-close update on 2 October; US gold futures settled at US$4,162.30. Spot silver fell 0.8% to US$60.36/oz.
Why metals did not simply rally on weak jobs
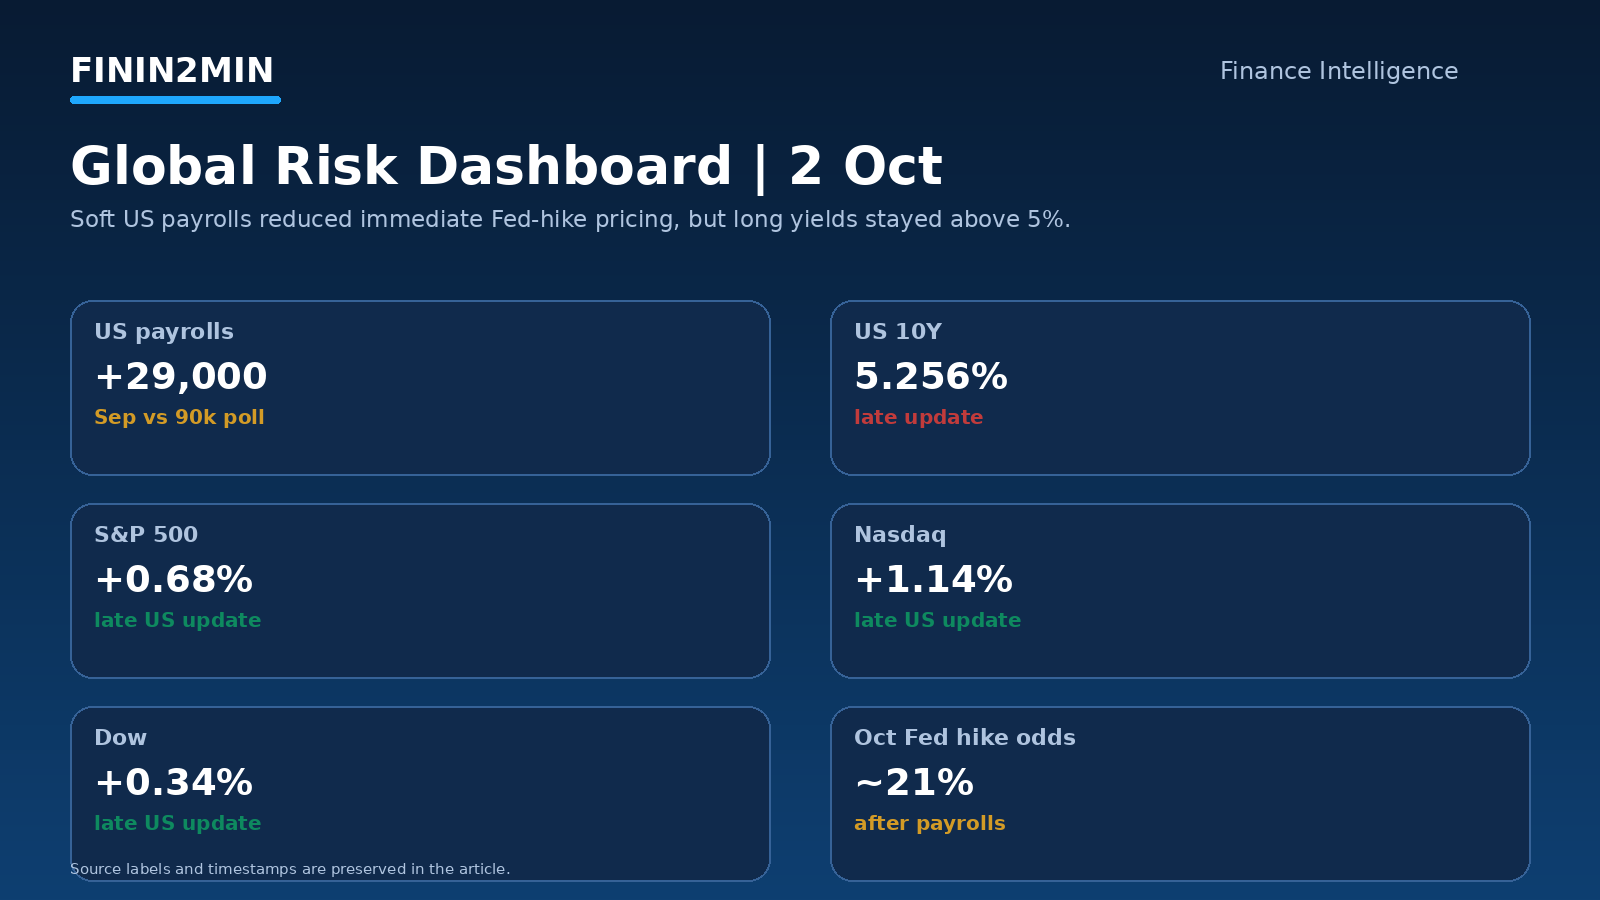
September US nonfarm payrolls rose by 29,000, below the 90,000 Reuters poll estimate, and rate-hike odds fell. But long Treasury yields remained very high and the dollar was still firm on the week, keeping the opportunity cost of holding non-yielding bullion elevated.
Portfolio lens
Gold is balancing safe-haven demand against real/nominal yield pressure. Silver adds industrial-demand sensitivity and can therefore show larger swings. Spot, futures and India retail prices should always be labelled separately.
Global markets: soft jobs, still-high yields
US labour report
US nonfarm payrolls increased by only 29,000 in September after a downwardly revised 133,000 gain in August. Reuters reported unemployment at 4.2% and traders cut the estimated probability of an October Fed hike to roughly 21% after the release.
Late market reaction
In Reuters' late US update, Dow was +0.34%, S&P 500 +0.68% and Nasdaq +1.14%. The US 10-year yield was 5.256% after initially falling on the jobs data, while the 2-year yield was 4.821%.
India read-through
The combination is mixed for India: softer US jobs reduce immediate Fed tightening pressure, but long yields above 5% still compete aggressively for global capital. Oil remains the swing factor that can turn a benign Fed repricing into an imported-inflation problem.
India economy: PMI and GST stay strong
Manufacturing PMI
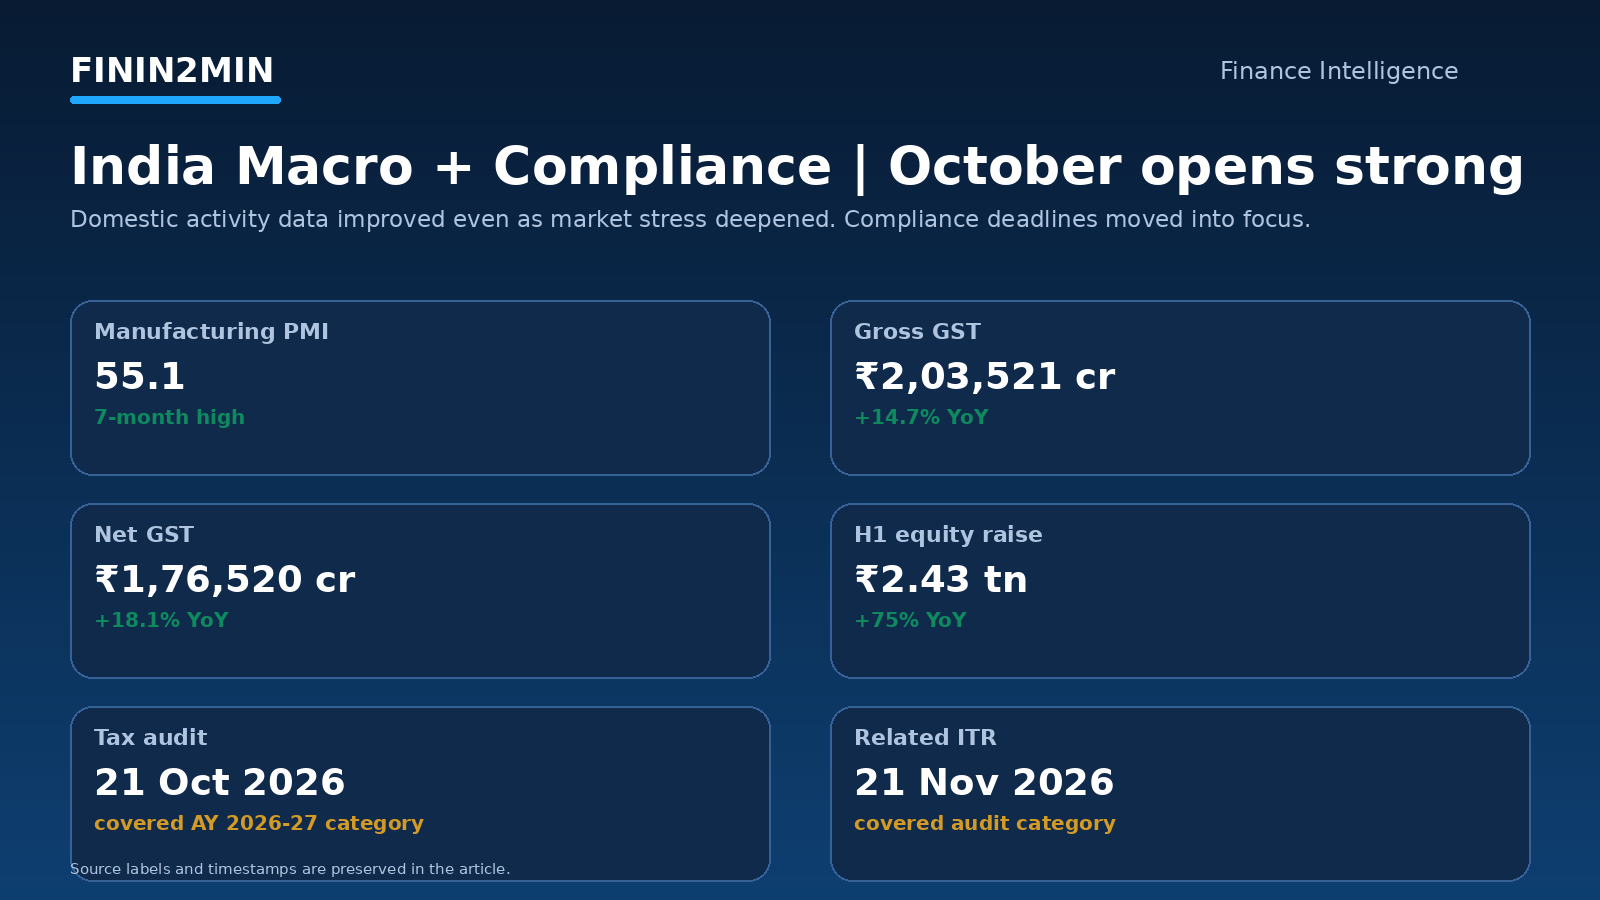
HSBC India Manufacturing PMI rose to 55.1 in September from 52.8 in August, its highest since February. New orders rose at the fastest pace since February, export demand improved and hiring resumed.
GST collections
September gross GST revenue was ₹2,03,521 crore, up 14.7% YoY. Gross domestic revenue rose 10.1% to ₹1,37,996 crore; import-linked revenue rose 25.9% to ₹65,525 crore. Refunds were ₹27,001 crore and net GST revenue rose 18.1% to ₹1,76,520 crore.
Interpretation
The domestic activity pulse is stronger than the secondary equity tape. However, the faster import-linked GST growth and elevated energy prices mean finance teams should track the quality of growth, input costs and working-capital pressure - not just headline tax receipts.
Capital markets: record primary fundraising
H1 FY27
Indian companies raised a record ₹2.43 trillion (US$25.27 billion) through equity markets in April-September, up 75% YoY, even as the secondary market weakened.
IPO/QIP detail
Mainboard IPOs raised ₹942.05 billion across 78 issues. Qualified institutional placements rose 36% to ₹615.53 billion, while secondary offerings increased sharply alongside government divestments.
CFO lens
The divergence between weak secondary-market momentum and strong primary issuance shows that domestic liquidity can remain available for differentiated issuers. Funding teams should focus on timing, dilution, investor mix, issue structure and post-listing liquidity rather than assume a weak index closes the equity window.
RBI banking change effective 1 October
What changed
RBI's Commercial Banks - Interest Rate on Deposits Second Amendment Directions, 2026 took effect on 1 October. Banks must disclose deposit interest rates in advance on their websites; bulk-deposit rates are to be posted at 10:00 am with a grace period to 10:10 am on each business day.
Pricing flexibility
The directions permit differential interest rates on bulk deposits by considering differential run-off rates under the Liquidity Coverage Ratio framework, for domestic rupee deposits and rupee deposits of non-residents.
Operational implication
Bank treasury, ALM, product and compliance teams should align rate-setting, website publishing, branch/customer uniformity controls and audit evidence. Corporates placing large deposits should compare same-day disclosed slabs rather than rely on historical negotiated rates.
Direct tax and GST compliance
Tax-audit extension
For the covered AY 2026-27 audit category, CBDT Circular No. 07/2026 moved the specified date for the audit report from 30 September to 21 October 2026 and the related return due date from 31 October to 21 November 2026.
Other Income-tax portal updates
The portal also lists Notification 121/2026 on TDS reporting for non-resident property transactions and Forms 132/141, and Notification 120/2026 extending registration for Registered Valuers and Authorised Income-tax Practitioners to 31 March 2027 with revised Forms 169/171.
GST filing discipline
For standard monthly filers, GSTR-1 and GSTR-3B due dates remain category-dependent statutory checkpoints. Entity-specific extensions, QRMP status and state/registration facts should be checked before relying on a generic calendar.
SEBI: Project Jagrook creates near-term broker obligations
Circular
SEBI's 1 October circular requires stock brokers to display investor-awareness messages under Project Jagrook, alongside the existing risk-disclosure framework.
5-31 October
From 5 October to 31 October, broker websites must display the investor-awareness messages and risk disclosures. Trading-app display of the awareness messages is voluntary during this phase.
From 1 November
From 1 November, specified awareness messages move to website landing pages; trading apps must display the awareness messages and risk disclosures on alternate days on their landing pages.
Action
Broker compliance, digital-product and legal teams should treat this as a content-placement/control requirement: source the exact SEBI message set, test landing-page/app rendering, preserve evidence and align change management before each effective date.
October Compliance Calendar
| Date | Obligation / event | Who should care | Status / action |
|---|---|---|---|
| 05 Oct 2026 | SEBI Project Jagrook website display phase begins | Stock brokers | Websites: awareness messages + risk disclosures through 31 Oct |
| 07 Oct 2026 | TDS deposit for September deductions - general monthly rule | Deductors / finance | Verify government/challan-statement and entity-specific exceptions |
| 11 Oct 2026 | GSTR-1 for September - monthly filers | GST monthly filers | Standard rule unless valid extension/applicability differs |
| 20 Oct 2026 | GSTR-3B for September - monthly filers | GST monthly filers | Standard rule unless valid extension/applicability differs |
| 21 Oct 2026 | Tax audit report - covered AY 2026-27 audit cases | Taxpayers / auditors | Extended from 30 Sep |
| 31 Oct 2026 | Q2 TDS statements - form/category dependent | Deductors / tax teams | Verify applicable form and deductor class |
| 01 Nov 2026 | Project Jagrook landing-page/app phase | Stock brokers | Website landing page; app messages/risk disclosures on alternate days |
| 21 Nov 2026 | ITR for same covered audit category | Taxpayers / finance | Extended from 31 Oct |
What finance users should watch next
- India reopening: crude, USD/INR and foreign-flow direction.
- US and India long yields ahead of the next RBI decision.
- Refined-product supply and European reserve-release follow-through.
- Project Jagrook implementation from 5 October and tax-audit execution before 21 October.
Source methodology
Primary regulators/exchanges and official government releases are preferred for law, tax and compliance. Reuters is used for time-sensitive global and market reporting. GIFT Nifty is labelled by contract/date and source status.
Disclaimer: General information and education only; not investment, trading, tax, legal or accounting advice. Verify live prices and primary-source law before acting.