Oil above $106, yields stay high; tax audit moves to 21 Oct as bank strike is deferred
Executive Brief
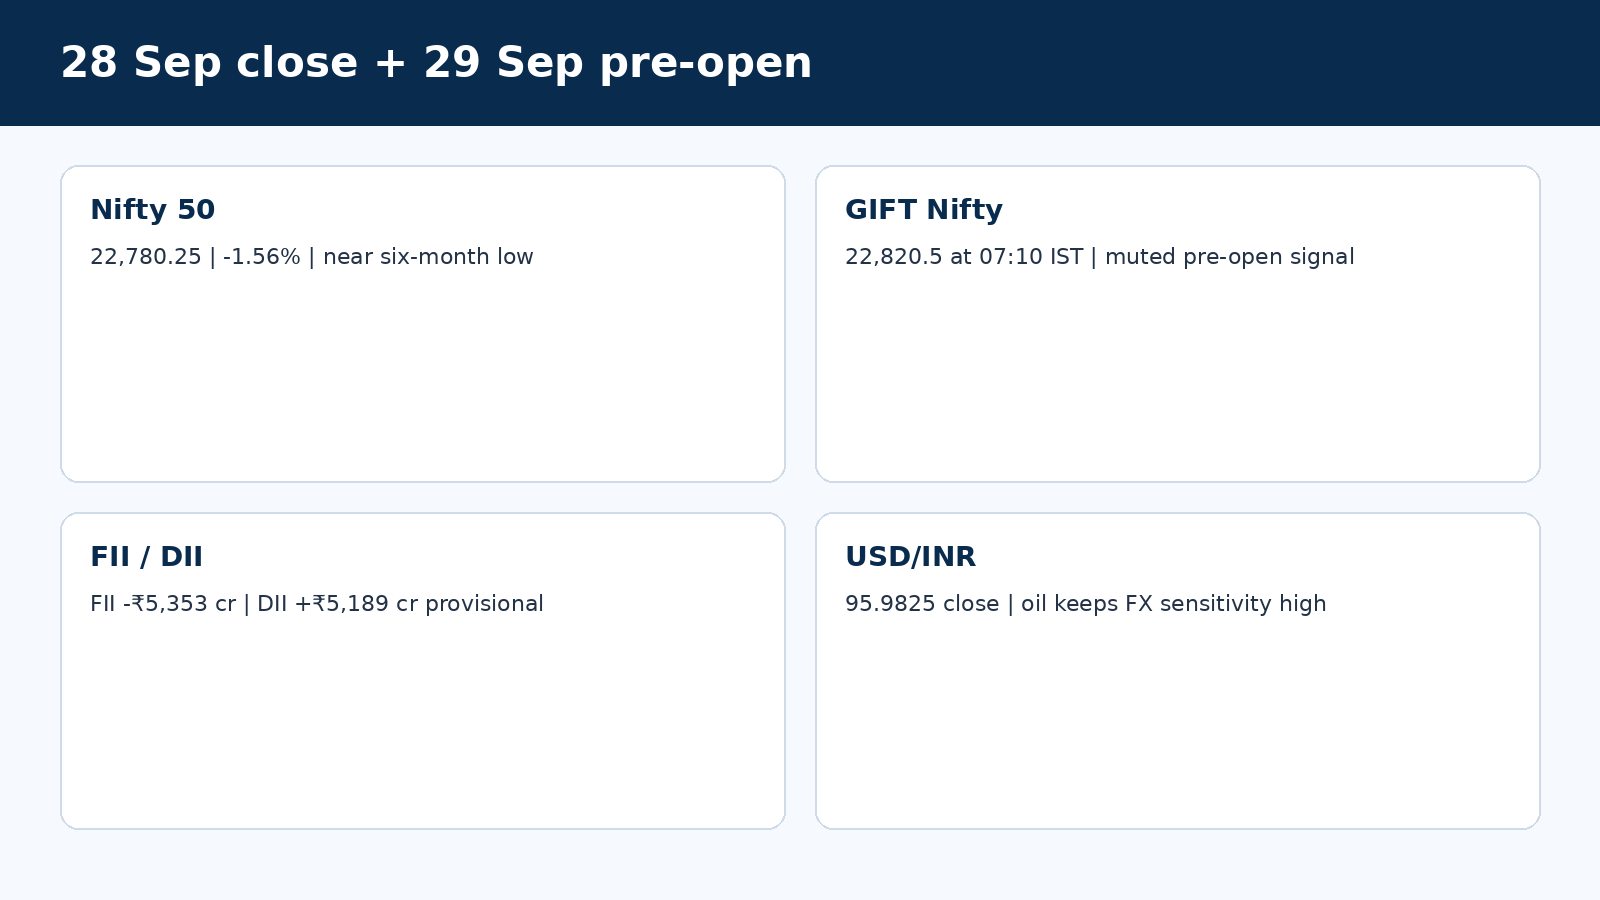
Indian risk assets entered Tuesday under pressure from a difficult cross-asset combination: crude above $106, US Treasury yields near multi-decade highs, a weaker rupee and persistent foreign selling. Monday’s Nifty 50 close at 22,780.25 was near a six-month low.
GIFT Nifty was around 22,820.5 at 07:10 IST on 29 September, signalling a muted start rather than a clear rebound. The futures/cash gap is basis, not a guaranteed opening move.
Gold and silver suffered a sharp global sell-off as higher oil reinforced inflation concerns and bond yields rose. Spot gold ended Monday around $4,136.81/oz and silver around $61.39/oz.
India’s operating economy remains stronger than the market tape: August IIP grew 8.0% YoY, led by manufacturing at 9.0% and electricity & gas at 12.3%, while mining contracted 5.6%.
The tax calendar changed materially: for covered audit cases, the specified audit-report date is 21 October 2026 and the related return-of-income due date is 21 November 2026.
The proposed nationwide bank strike for 28-30 September has been deferred after IBA-UFBU talks. Branches are operating normally; the five-day banking demand moves to a high-level committee.
India Markets & Flows
Nifty 50 fell 360.25 points to 22,780.25 (-1.56%) and Sensex declined 1.52% to 72,771.72. All 16 major sectors ended lower, with banks and financials among the biggest drags.
Foreign investors sold ₹5,353.22 crore in the provisional cash market while domestic institutions bought ₹5,189.02 crore. Domestic buying almost matched the day’s foreign outflow, but did not reverse the broader risk-off move.
The rupee closed at 95.9825 per US dollar. Reuters reported likely state-run bank dollar sales helped prevent a deeper fall through 96/$.
Crude Oil & India Impact
Brent settled Monday at $105.28 and WTI at $92.60 after an intraday surge above $108. In early Asian trade on Tuesday, Brent was back around $106.7 and WTI around $93.3 as Middle East supply risk remained elevated.
For India, oil above $100 directly affects the import bill, inflation expectations, rupee demand, refinery economics, freight costs and margins for energy-intensive businesses.
Finance teams should separate the intraday geopolitical spike from the official settlement and the next-session Asian quote; the direction and the volatility both matter for hedging and working capital.
Gold, Silver & Global Rates
Spot gold fell as much as 4% on Monday to $4,110.55 and finished around $4,136.81/oz. Silver fell 4.5% to about $61.39/oz.
The main pressure came from higher Treasury yields, a stronger dollar and expectations of additional Federal Reserve tightening. The US 10-year yield remained around 5.24%-5.27% in early Asia.
This episode shows that geopolitical stress does not guarantee higher bullion: when the same shock lifts oil, inflation expectations and real yields, the rates channel can overpower safe-haven demand.
India Economy
August 2026 IIP grew 8.0% YoY under the new 2022-23 base series. Manufacturing expanded 9.0%, electricity & gas 12.3%, water/waste 6.3%, while mining & quarrying contracted 5.6%.
Capital goods rose 16.9%, intermediate goods 13.7% and consumer durables 11.1%; consumer non-durables were softer at 2.1%. The data point to strong investment-linked production despite tighter financial conditions.
India’s trade minister Piyush Goyal is scheduled to visit the US from 29 September to 5 October for bilateral trade-agreement discussions and the G20 trade ministers meeting, making trade policy another near-term corporate watchpoint.
Tax & Direct-Tax Compliance
CBDT announced on 28 September that the return-of-income due date for AY 2026-27 for persons covered by Serial No. 2 of the table below Explanation 2 to section 139(1) moves from 31 October to 21 November 2026.
Accordingly, the “specified date” for furnishing the related audit report moves from 30 September to 21 October 2026. For ordinary covered tax-audit cases, this is the operative headline deadline.
Transfer-pricing cases remain a separate category unless covered by a specific subsequent order. Trusts/institutions filing Form 10B or 10BB should match their own return category and governing provision before assuming the same date.
CBDT Notification 121/2026 expands TDS reporting for non-resident property transactions and updates Forms 132 and 141. Notification 120/2026 extends the registration deadline for Registered Valuers and Authorised Income-tax Practitioners to 31 March 2027 and revises Forms 169 and 171.
Banking Operations
The proposed three-day nationwide bank strike for 28-30 September has been deferred after talks between the Indian Banks’ Association and the United Forum of Bank Unions on 27 September.
A high-level IBA-UFBU committee will examine the demand for declaring the remaining Saturdays as holidays. Discussions will also continue on the PLI framework and other residual issues.
Practical implication: businesses should not plan for a nationwide branch shutdown on 29-30 September. Normal branch operations continue, subject to local arrangements.
SEBI & Capital-Market Regulation
SEBI’s 28 September legal list includes a new Master Circular for Debenture Trustees. Listed-debt issuers, trustees and compliance teams should map current SOPs against the consolidated circular.
SEBI also issued final/settlement orders in the Adani Group public-float matter and other enforcement cases. Reuters reported that proceedings against Adani entities over alleged minimum-public-shareholding violations were disposed of without penalties on the companies, while two individuals received monetary penalties for disclosure-related issues.
Compliance teams should preserve the distinction between final orders, settlement orders and adjudication orders; they have different legal effects.
IFSCA, Bullion & Fund Management
IFSCA’s recent official updates include the 25 September framework for differential distribution in Venture Capital Schemes and Restricted Schemes, supporting blended-finance and differentiated economic-interest structures.
IFSCA also amended and updated its consolidated circular governing import of gold and silver through IIBX on 22 September. The change matters for bullion-import participants during a period of unusually high global price volatility.
RBI, Rates & Liquidity
Reuters reports a stronger case for RBI tightening at the October 5-7 policy meeting as inflation broadens, growth remains robust and global central banks turn more hawkish. A Reuters poll shows a majority of economists expecting a 25-bp hike to 5.50%.
Indian government bonds and the rupee remain vulnerable to oil and global yields. The 10-year government bond yield ended last week around 7.1194%, while foreign-exchange reserves had declined to about $765.9 billion after sustained intervention.
For CFOs, the practical message is higher hurdle rates, greater FX sensitivity and a need to re-test floating-rate debt and treasury assumptions.
Global Markets
US equities fell Monday as oil and Treasury yields rose: the S&P 500 lost about 0.8%, Nasdaq about 0.9% and Dow about 0.7%.
The global bond sell-off continued into Asia, with the US 10-year yield around a 19-year high. Higher sovereign yields are raising discount rates, corporate borrowing costs and refinancing risk globally.
Brent’s persistence above $100 remains the key cross-asset macro variable because it links geopolitics to inflation, monetary policy, currencies and equity valuations.
GIFT Nifty & Tuesday Setup
GIFT Nifty was around 22,820.5 at 07:10 IST on 29 September, roughly flat versus its own futures reference and only modestly above Monday’s Nifty cash close of 22,780.25.
Key variables into the open: Brent near $106-$107, the US 10-year near 5.25%, USD/INR around 96, FII selling, and whether the domestic market can stabilise after Monday’s broad decline.
No futures/cash basis comparison should be presented as a guaranteed opening gap.
Finance-Team Action Desk
Tax: use 21 October as the audit-report date only after confirming the taxpayer falls within the CBDT-covered category; schedule review, UDIN, portal acceptance and evidence retention well before the last day.
Treasury: refresh crude, FX and interest-rate sensitivities; check covenant headroom under a higher-rate scenario.
Banking: remove strike-contingency assumptions for 29-30 September, but continue to monitor the five-day-week negotiations.
Listed debt: review the 28 September SEBI Master Circular for Debenture Trustees where relevant.
Investment/IFSC: assess the IFSCA differential-distribution and IIBX circulars if your structure or operations are in GIFT IFSC.
Management reporting: keep operating growth (IIP +8%) separate from the tighter market discount-rate environment.
Sources
- CBDT due-date extension - PIB, 28 Sep 2026: source
- India equities 28 Sep - Reuters: source
- India pre-open 29 Sep - Reuters: source
- Oil 29 Sep - Reuters: source
- Gold 28 Sep - Reuters: source
- Rupee 28 Sep - Reuters: source
- RBI tightening backdrop - Reuters: source
- Global markets 29 Sep - Reuters: source
- India-US trade talks - Reuters: source
- August IIP - MoSPI official releases: source
- SEBI 28 Sep legal listing - SEBI: source
- SEBI orders 28 Sep - SEBI: source
- IFSCA latest updates - IFSCA: source
- Bank strike deferment - BEFI/UFBU circular listing: source
Disclaimer
Educational and informational content only. Not investment, tax or legal advice.