Functional currency
Currency of the primary economic environment.
Reviewed by CA Nikhil Gupta · Last reviewed 9 October 2026
Functional currency, foreign transactions, translation and lack of exchangeability. Prescribe how foreign-currency transactions and foreign operations are included in financial statements and how statements are translated into a presentation currency.
Prescribe how foreign-currency transactions and foreign operations are included in financial statements and how statements are translated into a presentation currency.
Currency of the primary economic environment.
Closing-rate translation; differences generally in profit or loss.
Closing-rate balance sheet, transaction-date income and OCI translation difference.
Estimate a spot rate reflecting an orderly exchange transaction.
| Paragraphs | Requirement and simple decode |
|---|---|
| 1–7 | Objective, scope and definitions Covers foreign transactions and operations and defines functional currency, monetary items, closing rate, net investment and presentation currency. |
| 8–14 | Functional currency Use primary sales-price and cost indicators, supported by financing, retained receipts and foreign-operation autonomy. Apply judgement when indicators conflict. |
| 15–15A | Net investment monetary items A long-term monetary item with no planned or likely settlement can form part of net investment; ordinary trade balances do not. |
| 16–19 | Functional versus presentation currency Measurement occurs in functional currency; financial statements can be presented in another currency. |
| 20–22 | Initial recognition Record at the transaction-date spot rate. Averages are acceptable only when they reasonably approximate actual rates. |
| 23–26 | Subsequent measurement Monetary items use closing rate; historical-cost non-monetary items use transaction-date rate; fair-value non-monetary items use valuation-date rate. |
| 27–34 | Exchange differences Recognise generally in profit or loss, except underlying OCI items and consolidated net-investment differences. |
| 35–37 | Functional-currency change Apply prospectively from the date economic facts and circumstances change. |
| 38–43 | Translation to presentation currency For non-hyperinflationary entities, use closing rate for assets and liabilities, transaction-date rates for income and expenses and OCI for translation differences. |
| 43 | Hyperinflation Restate under Ind AS 29 before translation. |
| 44–47 | Foreign operations in group reporting Apply translation procedures in consolidation and equity accounting, including goodwill and fair-value adjustments. |
| 48–49 | Disposal and partial disposal Recycle or reattribute cumulative translation amounts according to whether control, joint control or significant influence is lost. |
| 50–57 | Tax and disclosures Apply Ind AS 12 and disclose exchange differences, functional-currency changes and currency information. |
| 8A–8B | Exchangeability definition A currency is exchangeable when the other currency can be obtained through an enforceable market or mechanism within normal administrative delay. |
| 19A–19B | Purpose-specific assessment Assess exchangeability for each purpose, reporting date and amount. |
| 19C–19E | Estimated spot rate When not exchangeable, estimate a rate satisfying the orderly-exchange objective using suitable observable rates or another technique. |
| 57A–57B | Additional disclosures Explain nature and effects, rate, estimation process, risks and foreign-operation exposure. |
| 60L–60M | Effective date and transition Apply from periods beginning 1 April 2025 without comparative restatement; recognise specified opening adjustments. |
| Appendix B | Advance consideration Each non-monetary advance payment or receipt establishes its own transaction date for the related asset, expense or income. |
It follows economics rather than management preference.
Cash and receivables are monetary; inventory, PPE, goodwill and many advances are non-monetary.
A non-monetary prepayment fixes the rate for that portion of the later asset or expense.
Settlement intention and likelihood are critical.
A currency can be exchangeable for one purpose but not another.
Official, parallel-market or later rates are not automatic answers; they must meet the measurement objective.
Restate under Ind AS 29 before translating.
Editable SVG and high-resolution PNG are included in the batch assets.
Forty per cent advance is paid at ₹83/USD and the balance at delivery at ₹87/USD.
Sales are USD, costs INR and financing EUR.
Routine imports can be funded but a large dividend cannot be remitted.
An official rate exists but no enforceable conversion mechanism is available.
The parent sells 15% but retains control.
| Topic | Ind AS | IFRS | US GAAP |
|---|---|---|---|
| Functional currency | Primary economic environment. | Broadly aligned. | Similar concept. |
| Lack of exchangeability | Effective from 1 April 2025. | IAS 21 amendment effective from 1 January 2025. | Different currency-conversion guidance. |
| Hyperinflation | Restate then translate. | Same. | Parent reporting currency generally becomes functional for highly inflationary operations. |
| Net-investment CTA | OCI until qualifying disposal. | Broadly aligned. | Detailed disposal rules differ. |
| Advance consideration | Appendix B transaction-date model. | IFRIC 22 equivalent. | Detailed treatment differs. |
Map conversion mechanisms and restrictions.
Approve functional-currency and rate memoranda.
Assess withholding and deferred tax.
Track CTA, NCI and disposals.
Challenge estimated rates and disclosures.
Added and reviewed on 9 October 2026. This section adds worked examples and current-year controls to the guide above; where the two differ, follow the standard text and the latest notification.
| Position | Measurement | Typical account |
|---|---|---|
| Dollar trade payable | Closing rate at reporting date | P&L exchange gain/loss |
| Historical-cost inventory | Recognition-date rate | Inventory at historical cost |
| Non-monetary advance for machinery | Appropriate advance-date rate | Asset/prepayment |
| Foreign subsidiary translation | Closing/transaction-date translation | OCI translation reserve, as applicable |
Consider an Indian manufacturing subsidiary which buys machinery in dollars, sells goods mainly to Indian customers in rupees, pays most staff in rupees and borrows in rupees. Its functional currency is likely INR despite a large imported machinery programme. A group's preference to consolidate in USD does not override the entity's own primary economic environment. Keep a signed functional-currency assessment documenting sales prices, labour and input costs, financing, and the autonomy of any foreign operation. Only then identify each foreign-currency monetary and non-monetary line in the trial balance.
The accounting file needs four dates: transaction recognition, payment or settlement, reporting date, and any advance consideration date. Each date may produce a different exchange rate and different journal result. Do not mechanically use the bank's remittance rate for every recognition event. The appropriate spot or approximating rate depends on the applicable transaction date; an average is useful only when it reasonably approximates actual rates.
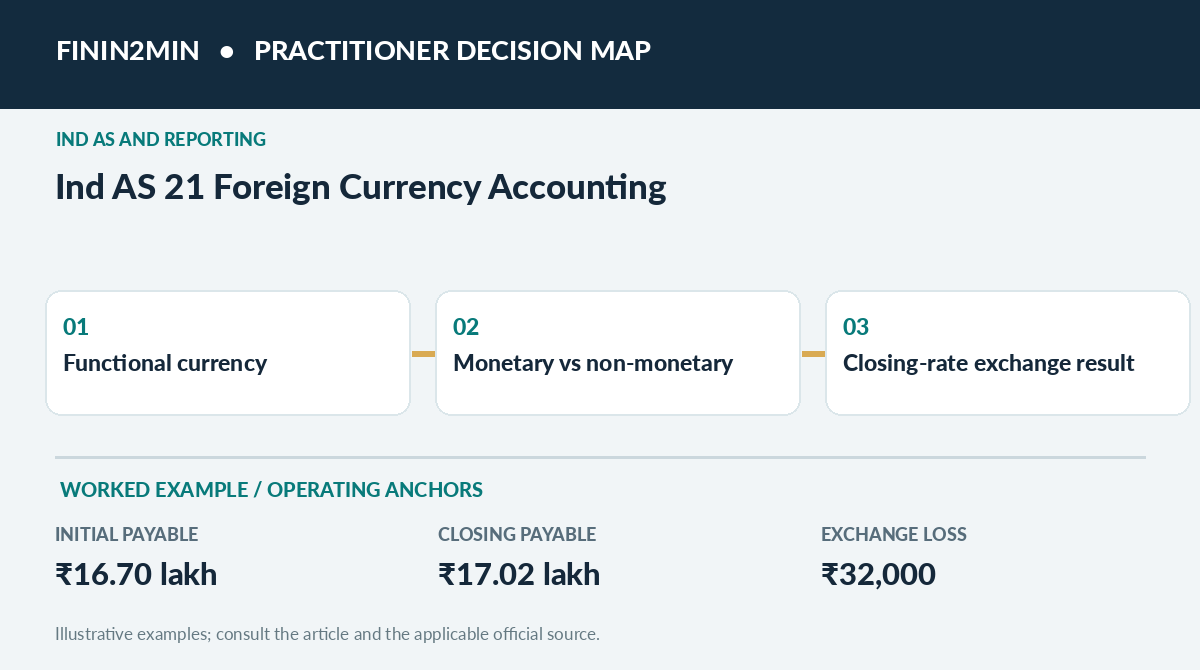
Suppose goods are purchased for USD 20,000 on 1 December when the spot rate is ₹83.50. The initial liability and inventory cost are ₹16,70,000, ignoring other directly attributable costs. At 31 March the supplier remains unpaid and the closing rate is ₹85.10. The monetary payable becomes ₹17,02,000. The ₹32,000 exchange loss goes through profit or loss in an ordinary trade-payable fact pattern; the inventory recorded at historical cost is not increased merely because the unpaid dollar liability moved. When the payable is settled, calculate the further exchange difference against the carrying amount at the last reporting date.
Contrast this with imported machinery where USD 8,000 was prepaid at ₹83 and USD 12,000 became payable on delivery at ₹86. If the advance met the conditions for a non-monetary prepayment, the relevant foreign-currency cost is locked at the advance-date exchange rate for that portion: ₹6,64,000 plus ₹10,32,000 for the unpaid portion, before other capitalisable charges. Do not assume that an advance is always monetary: read its settlement terms and what the payer is entitled to receive.
A foreign subsidiary with a different functional currency creates a second accounting layer. Translate assets and liabilities at the closing rate, and income and expenses at dates of the underlying transactions (or properly justified averages). The resulting translation difference is generally recognised in other comprehensive income and accumulated in equity, subject to the specific standard requirements. It is not the same as the rupee exchange gain on an Indian company's overseas debtor.
Where an intercompany long-term monetary item forms part of a net investment in a foreign operation, settlement plans and foreseeable likelihood of settlement matter. Do not label routine intercompany payables as net investments merely because repayment is delayed. Examine whether disposal or change in control triggers translation reserve treatment rather than assuming every sale recycles the entire amount.
A published official rate alone does not establish that an entity can obtain the currency for the intended purpose and amount. The amended standard addresses the assessment of exchangeability and estimation of a spot exchange rate when exchangeability is absent. The purpose, amount and measurement date are crucial. A currency may be exchangeable for purchases of essential imports but effectively unavailable for dividend remittances. The estimation method must seek the rate that reflects the measurement objective, supported by observable evidence where possible.
Disclosures should help users understand how lack of exchangeability affects the entity's financial position, performance and cash flows. Document restricted remittance channels, regulatory notices, observable transactions, estimates and estimation uncertainty. A rate scraped from an unauthorised marketplace is not by itself acceptable audit evidence.
Prepare an open-item listing of currency, original amount, transaction rate, settlement status, carrying amount and closing rate. Tie that list to AP, AR, treasury confirmations and the general ledger. Separate advances, inventory, PPE, loans, derivatives, intercompany balances and foreign subsidiary translation. If hedges exist, evaluate their accounting under Ind AS 109 instead of forcing all hedge movements through ordinary Ind AS 21 remeasurement.
Record the journal bridge explicitly: original payable ₹16,70,000; period-end payable ₹17,02,000; increase ₹32,000; expense ₹32,000. Keep source exchange rate evidence and a reviewer sign-off. Explain material differences between GST customs valuation, income-tax treatment and books rather than assuming the three use the same reference rate. A clean bridge prevents apparent FX gains from arising solely because an advance was reversed at the wrong rate.
A closing-rate translation should not revalue historical-cost furniture or an item of inventory merely because it was purchased overseas. An average rate should not substitute for transaction rates during extreme volatility. Net-investment treatment cannot be chosen for desired OCI presentation. Finally, the group's presentation currency does not automatically become every subsidiary's functional currency. Each error changes the story the financial statements tell and requires its own evidence trail.
Yes, depending on the whole primary economic environment. Assess primary and secondary factors; sales currency alone may be insufficient.
No. Translation of foreign operations and certain net-investment situations can affect OCI under the applicable requirements.
Analyse whether the advance is non-monetary. If so, it normally retains the advance-date rate for the covered portion.
A bank transaction rate may be evidence for actual settlements. It is not an automatic substitute for the appropriate recognition or reporting-date spot rate.
Not necessarily. Assess practical access for the relevant purpose, amount and measurement date.
A functional-currency memo, transactions ledger, outstanding foreign-currency balances, rate evidence, translations, management assumptions and a signed reconciliation.
Start with the currency that mainly influences sales prices, labour, materials and other operating costs. Financing currency and the currency in which receipts are retained are supporting indicators. For a foreign operation, autonomy, transaction volume with the reporting entity, cash-flow remittance and financing dependence also matter. When indicators conflict, document the economic evidence and judgement. A later change is accounted for prospectively from the date the underlying facts change; presentation currency can be different, but it does not replace the functional-currency assessment.
Cash, receivables and payables for a fixed or determinable number of currency units are monetary. They are retranslated at the reporting-date closing rate and exchange differences generally enter profit or loss, subject to specific net-investment and hedge rules. Inventory, property, goodwill and many advances are non-monetary. Historical-cost items use the transaction-date rate; fair-value items use the rate when fair value was measured. This classification prevents the common error of applying the closing rate to every foreign-currency balance.
Under the notified 2025 amendment, exchangeability is assessed for a specified purpose, amount and measurement date. If the entity cannot obtain more than an insignificant amount of the other currency through a market or exchange mechanism creating enforceable rights and obligations, it estimates the spot rate that would have applied in an orderly exchange transaction. The file should retain the market evidence, estimation technique, inputs and sensitivity. The amendment applies for annual periods beginning on or after 1 April 2025 and requires additional disclosures; comparative information is not mechanically restated under the transition provisions.
An Indian parent has a USD receivable of USD 100,000 recorded when USD/INR was 84.00. At year-end the closing rate is 86.20. Because the receivable is monetary, its carrying amount moves from Rs 84.00 lakh to Rs 86.20 lakh and the Rs 2.20 lakh exchange difference is recognised under the applicable Ind AS 21 rules. A USD advance paid for machinery is different: if it is a non-monetary prepayment, the rate attached to the advance portion is not simply replaced by the year-end closing rate.
No. Functional currency is determined from the entity’s economic environment.
Only when they reasonably approximate actual transaction-date rates; severe volatility can make averages inappropriate.
No. The estimated rate must meet the standard’s orderly-exchange objective and be supported by evidence.
No. Specific foreign-operation, net-investment and hedge circumstances can place amounts in OCI.
For periods affected by later notified amendments, read the compendium together with the applicable MCA notification listed by ICAI.
Use the current official instrument, portal or regulator publication before acting. Page-specific references are listed below.